Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
AI Content Detectors Software Market: $500M (2025), 25% CAGR
AI Content Detectors Software
AI Content Detectors Software Market: $500M (2025), 25% CAGR
AI Content Detectors Software by Component (Software Platforms, APIs and SDKs, Services), by Deployment Mode (Cloud-based, On-premise, Hybrid), by Enterprise Size (Large Enterprises, Small & Medium Enterprises (SMEs)), by Technology (Natural Language Processing (NLP), Machine Learning Algorithms, Deep Learning Models, Neural Networks, Computer Vision, Pattern Recognition Technology, Metadata Analysis, Others), by Application (Plagiarism & Academic Integrity, Deepfake & Synthetic Media Detection, Misinformation & Disinformation Detection, Toxicity & Hate Speech Moderation, Content Authenticity, Others), by Pricing Model (Subscription-Based, Freemium, Pay-per-Use), by End User (BFSI, Healthcare, IT & Telecom, Retail & E-commerce, Media & Entertainment, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 2, 2026|Base Year : 2025|Pages : 134
Key Insights on the AI Content Detectors Software Market
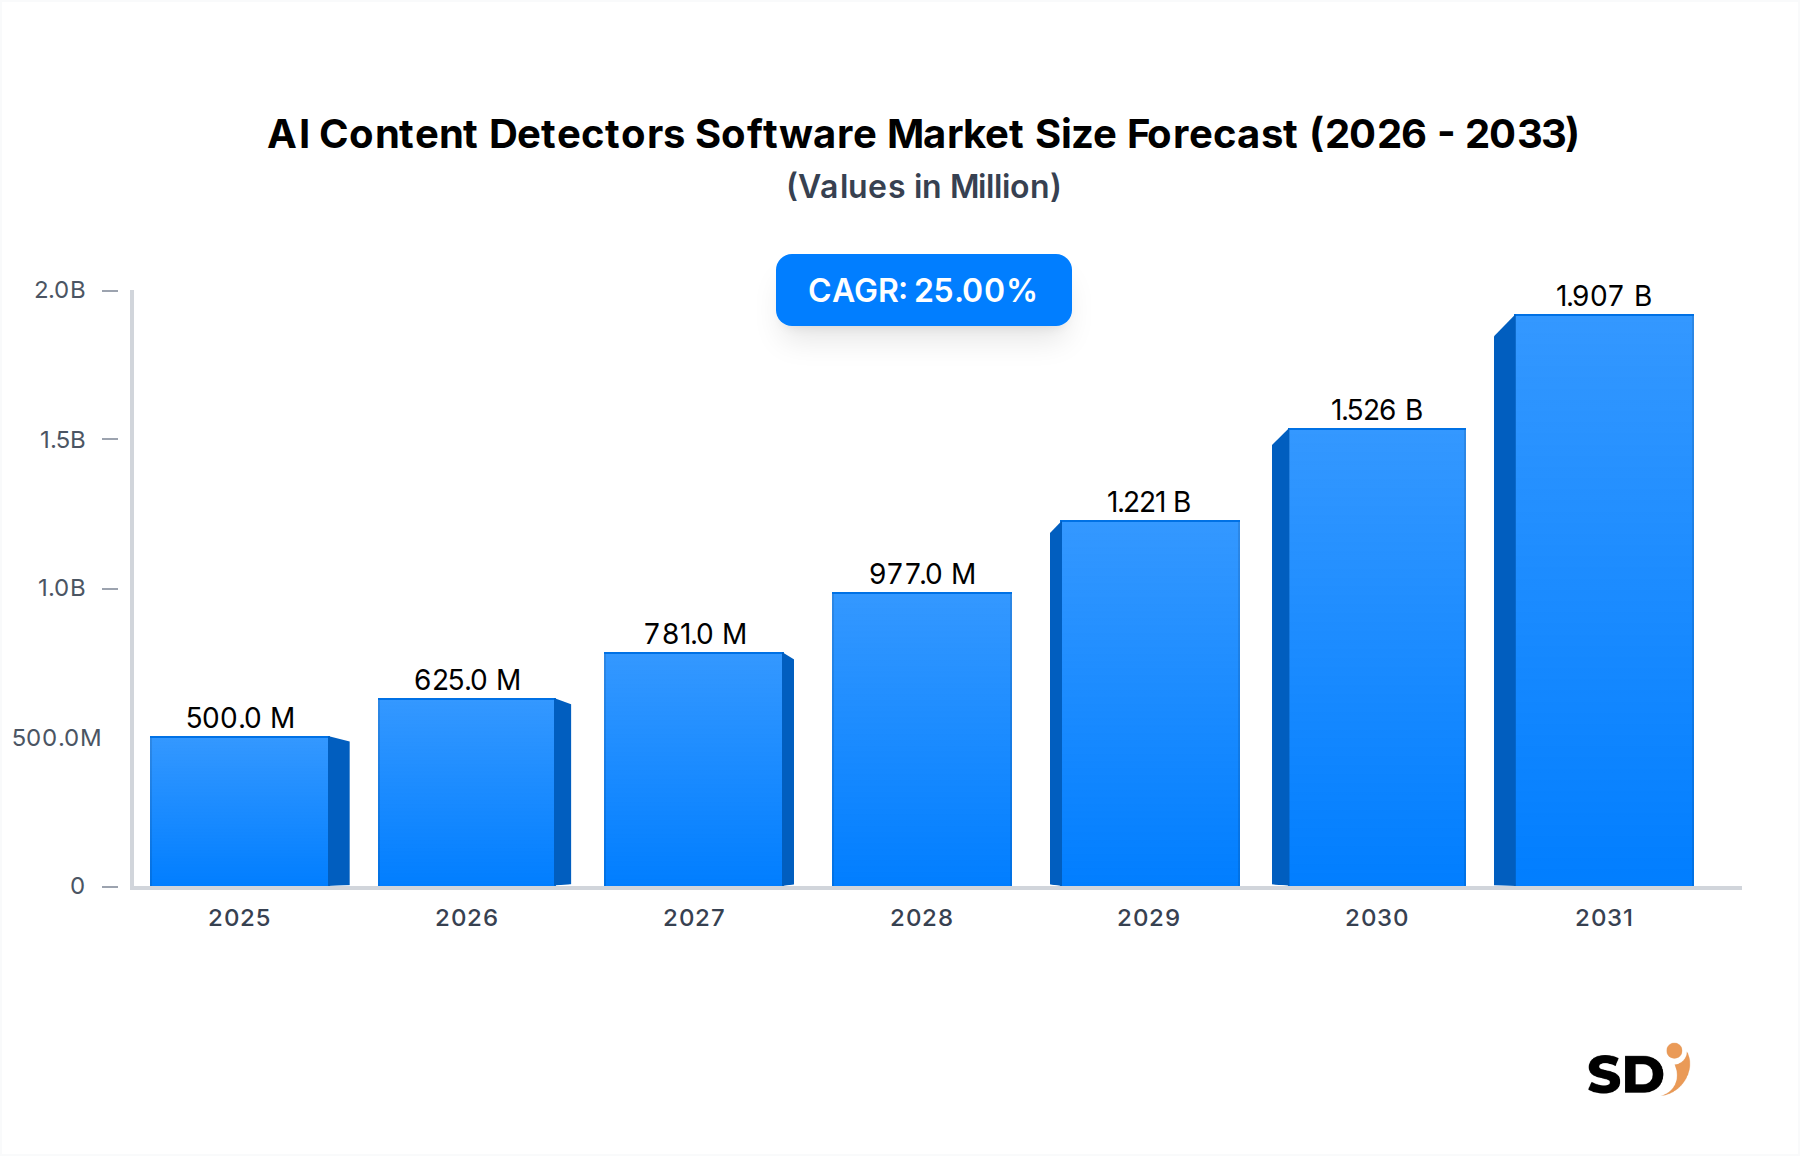
The AI Content Detectors Software Market is experiencing robust expansion, driven by the proliferation of AI-generated content across various sectors. Valued at USD 500 million in 2025, the market is projected to demonstrate a compound annual growth rate (CAGR) of 25% over the forecast period. This significant growth trajectory is primarily fueled by the escalating demand for authenticity verification, academic integrity solutions, and the critical need to combat misinformation and deepfakes. The rapid advancements in generative AI, while beneficial, have simultaneously heightened the urgency for sophisticated detection mechanisms, positioning this market as a crucial component of the broader Artificial Intelligence Software Market landscape. Key demand drivers include educational institutions striving to maintain academic standards, enterprises seeking to protect brand reputation and ensure content quality, and governmental bodies combating disinformation campaigns. The increasing sophistication of AI models necessitates equally advanced detection capabilities, leading to continuous innovation in the AI Content Detectors Software Market. Regulatory pressures concerning data authenticity and content governance are also providing a macro tailwind, compelling organizations across BFSI, Healthcare, IT & Telecom, and Media & Entertainment sectors to adopt robust detection solutions. The market outlook remains exceptionally positive, characterized by ongoing R&D in areas like Natural Language Processing Technology Market and Machine Learning Software Market, aimed at improving accuracy and reducing false positives. Further market penetration is expected as the integration of these tools becomes standardized across digital platforms and content creation workflows, underscoring the indispensable role of AI content detection in safeguarding digital trust and information integrity.
AI Content Detectors Software Market Size (In Million)
2.0B
1.5B
1.0B
500.0M
0
500.0 M
2025
625.0 M
2026
781.0 M
2027
977.0 M
2028
1.221 B
2029
1.526 B
2030
1.907 B
2031
Natural Language Processing (NLP) Technology in the AI Content Detectors Software Market
Within the multifaceted landscape of the AI Content Detectors Software Market, Natural Language Processing (NLP) technology stands out as a dominant segment by revenue share, forming the fundamental backbone for most advanced detection solutions. NLP enables software to understand, interpret, and generate human language, which is critical for analyzing text-based AI-generated content. Its dominance stems from the widespread application of AI in generating written content, from academic papers and marketing copy to news articles and social media posts. NLP algorithms are employed to scrutinize stylistic nuances, grammatical patterns, semantic coherence, and statistical anomalies that often differentiate human-authored text from machine-generated output. Key players like Copyleaks and Originality.AI heavily leverage sophisticated NLP models to provide granular analysis, identifying not just plagiarism but also the characteristic fingerprints of various large language models (LLMs). The segment’s growth is further propelled by the continuous refinement of NLP techniques, including transformer models and contextual embeddings, which enhance detection accuracy and reduce false positives. As generative AI models become more adept at producing human-like text, the NLP component of detection software must evolve in parallel, demanding significant R&D investment. This leads to a dynamic competitive environment where differentiation often comes from proprietary NLP model architectures and training data sets. The share of NLP-driven solutions is not only growing but also consolidating, as effective AI content detection is intrinsically linked to superior language understanding capabilities. This also drives innovation in the broader Natural Language Processing Technology Market, pushing the boundaries of what these algorithms can achieve. The reliance on NLP also intertwines this segment with the Deep Learning Software Market, as deep learning techniques are integral to developing state-of-the-art NLP models that can analyze complex linguistic patterns at scale. The capability to detect subtle machine-generated patterns across vast datasets positions NLP as the indispensable core of the AI Content Detectors Software Market.
Key Market Drivers in the AI Content Detectors Software Market
The AI Content Detectors Software Market is propelled by several critical drivers, each contributing significantly to its accelerated growth. Firstly, the exponential rise in sophisticated AI-generated content, particularly text and synthetic media, is a primary catalyst. With large language models (LLMs) becoming more accessible and powerful, there's an increasing volume of AI-generated articles, essays, and reports, necessitating tools for content authenticity verification. This drives the demand for specialized solutions within the Plagiarism Detection Software Market, especially in academic and publishing sectors. Secondly, the escalating global concern over misinformation, disinformation, and deepfakes is a potent driver. Governments, media organizations, and social platforms are increasingly investing in AI content detectors to identify and mitigate harmful synthetic media, impacting areas like the Cybersecurity Software Market. The integrity of information and public trust hinges on effective detection mechanisms, leading to significant uptake in sectors like Media & Entertainment. Thirdly, the imperative for academic integrity and plagiarism prevention in educational institutions remains a cornerstone. As students gain access to advanced AI writing tools, universities and schools require robust AI content detectors to ensure original work, thereby bolstering the Academic Integrity Software Market. Lastly, brand reputation management and content quality assurance for enterprises are significant factors. Businesses utilize these tools to ensure marketing copy, product descriptions, and customer service responses are human-authored and align with brand voice, preventing the inadvertent use of AI-generated content that could lack nuance or accuracy. This also creates a growing adjacent market for API Management Software Market as businesses integrate detection capabilities directly into their content pipelines.
Competitive Ecosystem of AI Content Detectors Software Market
The competitive landscape of the AI Content Detectors Software Market is characterized by a mix of established technology firms and agile startups, all vying for market share through innovation in detection accuracy and feature sets.
Sapling: This company offers AI-powered writing assistance and grammar checking, integrating detection features to identify AI-generated text, focusing on professional communication and content quality.
Winston AI: Specializes in AI content and plagiarism detection, providing high-accuracy results for educational institutions, content creators, and web publishers who prioritize original content.
Copyleaks: A prominent provider of AI content detection and plagiarism checker solutions, known for its advanced algorithms that analyze various content types and support numerous languages.
Writer: Offers an AI writing assistant that also includes features for detecting AI-generated content, aiming to help teams maintain brand consistency and quality across all written materials.
Humbot: Focuses on simplifying the detection of AI-written content, providing a user-friendly interface for quick scans and reports, catering to individual users and small businesses.
Originality.AI: Provides a comprehensive AI content and plagiarism detector designed for content marketers and publishers, emphasizing high accuracy and detailed analysis to ensure content originality.
GPTZero: Known for its early entry and strong focus on detecting content generated by large language models, particularly in academic settings and for journalists.
Content At Scale: Offers an AI content generation platform that also integrates its own AI detection capabilities, aiming to provide a full-cycle solution for content creation and verification.
Content Guardian: Aims to protect digital content integrity through advanced AI detection, focusing on preventing fraud and ensuring authenticity across online platforms.
AI Detector Pro: Provides a tool specifically designed to identify AI-generated text, targeting content creators, educators, and anyone needing to verify the originality of written material.
Corrector App: Primarily a grammar and spelling checker, it incorporates AI detection features to help users identify and refine content that may have been generated by AI.
Quetext: A well-established plagiarism checker that has expanded its capabilities to include AI content detection, serving academic and professional writing markets.
Recent Developments & Milestones in AI Content Detectors Software Market
Recent developments in the AI Content Detectors Software Market highlight continuous innovation driven by evolving AI generation capabilities and increased user demand for robust detection solutions.
May 2026: Leading AI detection platforms announced significant updates to their underlying Machine Learning Software Market algorithms, incorporating new training data sets from the latest generative AI models to enhance accuracy in identifying sophisticated AI-generated text, reducing false positives by an estimated 15%.
April 2026: A major educational technology provider partnered with a specialized AI content detector company to integrate advanced Plagiarism Detection Software Market capabilities directly into its learning management system, aiming to combat the rising use of AI tools in academic submissions.
March 2026: Several prominent players in the AI Content Detectors Software Market launched new API-first solutions, allowing seamless integration for enterprises into existing content management systems, signaling a maturation of the API Management Software Market within this sector.
February 2026: Research institutions published findings on novel Deep Learning Software Market architectures showing promise in detecting multimodal AI-generated content (combining text, image, and audio), pushing the boundaries beyond text-only analysis.
January 2026: A consortium of media organizations and tech companies announced a joint initiative to develop open standards for content authenticity and AI detection, aiming to establish industry-wide benchmarks for identifying deepfakes and misinformation, directly impacting the Content Moderation Software Market.
December 2025: Regulatory bodies in Europe began exploring guidelines for mandating AI content disclosures and promoting detection tools, indicating potential future legislation that could significantly expand the adoption of AI content detection across various industries.
Regional Market Breakdown for AI Content Detectors Software Market
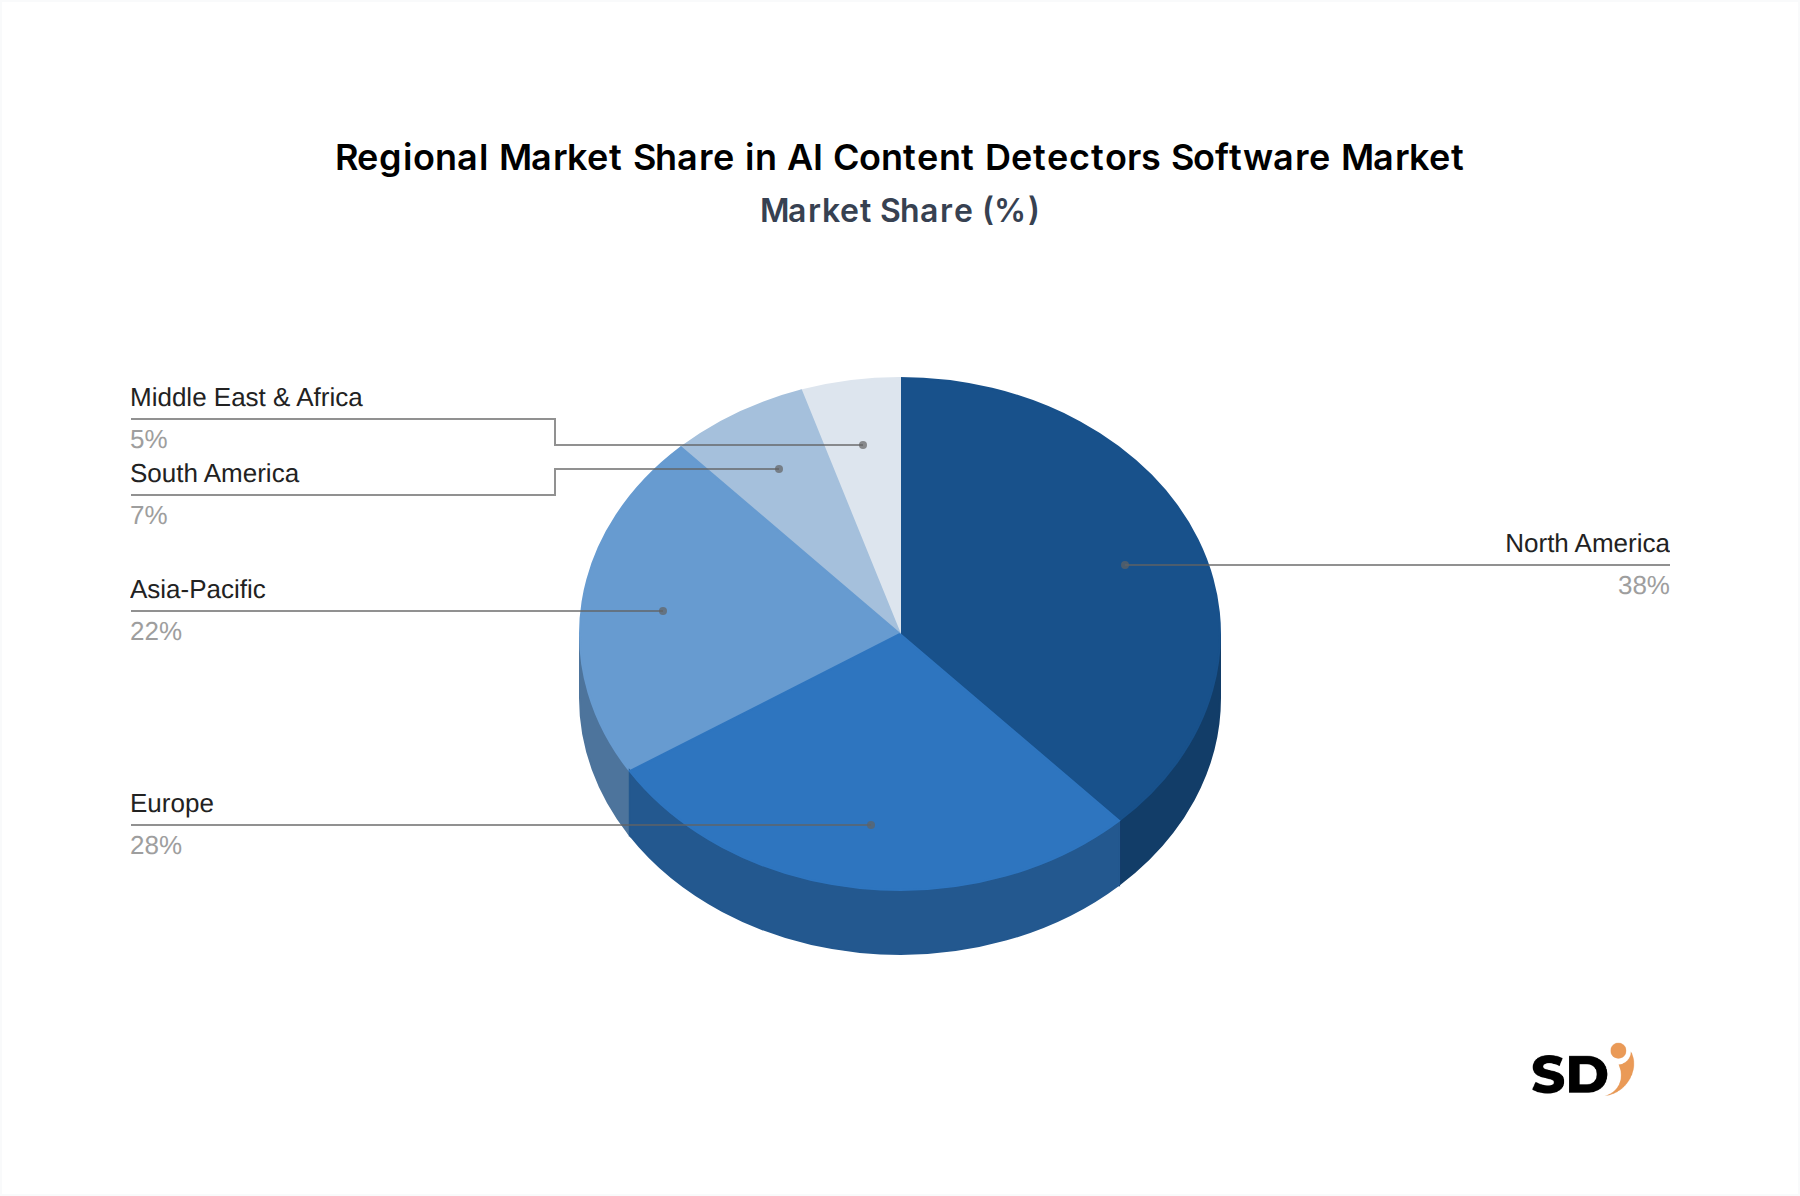
The global AI Content Detectors Software Market exhibits varied adoption rates and growth trajectories across different regions, influenced by technological readiness, regulatory frameworks, and the prevalence of AI content generation. North America currently holds the largest revenue share, primarily driven by early adoption in academic institutions and advanced enterprises, coupled with significant R&D investments in Artificial Intelligence Software Market solutions. The region benefits from a high concentration of tech companies and a proactive approach to combating misinformation and maintaining digital integrity. Europe follows closely, demonstrating strong growth due to increasing regulatory pressures, such as the EU AI Act, which emphasizes transparency and accountability for AI systems, thereby boosting the demand for detection tools. Countries like the UK, Germany, and France are key contributors, driven by a focus on data governance and ethical AI. The Asia Pacific region is poised for the fastest growth over the forecast period. This surge is attributed to rapid digital transformation, increasing internet penetration, and the booming content creation industry, particularly in countries like China, India, and Japan. The burgeoning use of generative AI in creative industries and local language content drives demand for localized AI content detection solutions. In the Middle East & Africa (MEA) and Latin America, the market is in an nascent stage but is expected to accelerate, particularly with the growth of e-learning platforms and efforts to modernize educational and corporate digital infrastructure. The primary demand driver in these emerging markets is the foundational need for digital trust and the prevention of plagiarism in expanding digital ecosystems. Each region contributes distinctly to the global landscape, with leading economies dictating innovation and regulatory trends, while developing economies represent significant untapped potential for growth in the AI Content Detectors Software Market.
Technology Innovation Trajectory in AI Content Detectors Software Market
The technology innovation trajectory within the AI Content Detectors Software Market is marked by relentless advancements, driven by the need to outpace the ever-evolving capabilities of generative AI. Two of the most disruptive emerging technologies include multimodal AI detection and explainable AI (XAI) for detection. Multimodal AI detection, which involves analyzing text, image, audio, and video content simultaneously, is rapidly gaining traction. Current solutions are largely text-centric, but as deepfakes and synthetic media become more sophisticated, the ability to correlate cues across different modalities will be crucial. This technology reinforces incumbent models by allowing them to expand their scope, but it also threatens those solely focused on single-modality detection, demanding significant R&D investment in areas like Computer Vision and advanced Neural Networks. Early adoption timelines suggest commercial offerings will become more prevalent within the next 2-3 years, with current R&D efforts focusing on improving computational efficiency and reducing latency. The second disruptive technology is Explainable AI (XAI) in detection. As AI content detectors classify content, there is a growing demand from users, particularly in legal and academic contexts, to understand why a piece of content was flagged. XAI aims to provide transparent insights into the detection process, offering auditability and trust. This directly reinforces incumbent business models by enhancing user confidence and regulatory compliance. R&D in XAI for this market involves developing more interpretable Deep Learning Software Market models and creating intuitive visualization tools. Adoption is slower due to the complexity of XAI implementation, but it is expected to become a standard feature in high-stakes applications within 3-5 years. Both innovations underscore a market moving towards more comprehensive, transparent, and robust detection capabilities, necessitating continuous integration of cutting-edge research from the broader Artificial Intelligence Software Market.
Investment & Funding Activity in AI Content Detectors Software Market
Investment and funding activity within the AI Content Detectors Software Market has seen a significant uptick over the past 2-3 years, reflecting the critical and growing importance of these solutions. Venture funding rounds have been robust, with several startups specializing in deepfake detection and academic integrity solutions securing substantial seed and Series A funding. For instance, companies focusing on sophisticated Natural Language Processing Technology Market models for text originality have attracted considerable capital, indicating investor confidence in specialized detection capabilities. Mergers and acquisitions (M&A) activity, while not yet at a frenetic pace, is beginning to emerge, particularly as larger cybersecurity firms and educational technology platforms look to integrate AI detection capabilities into their existing product portfolios. Strategic partnerships are also a key trend, with AI content detector providers collaborating with social media platforms, content management systems, and academic publishers to embed their technology directly where it's most needed. The sub-segments attracting the most capital are those addressing critical pain points: misinformation and deepfake detection, driven by geopolitical concerns and brand safety; and advanced plagiarism/academic integrity, fueled by the proliferation of generative AI in educational settings. Investors are keen on solutions that offer high accuracy, low false-positive rates, and scalability, with a particular emphasis on those leveraging cutting-on-edge Machine Learning Software Market techniques. The API Management Software Market segment, enabling seamless integration, is also seeing increased investment as companies prioritize frictionless adoption. This influx of capital underscores the market's perception as a high-growth sector essential for maintaining digital trust and content authenticity in an increasingly AI-driven world.
AI Content Detectors Software Segmentation
1. Component
1.1. Software Platforms
1.2. APIs and SDKs
1.3. Services
2. Deployment Mode
2.1. Cloud-based
2.2. On-premise
2.3. Hybrid
3. Enterprise Size
3.1. Large Enterprises
3.2. Small & Medium Enterprises (SMEs)
4. Technology
4.1. Natural Language Processing (NLP)
4.2. Machine Learning Algorithms
4.3. Deep Learning Models
4.4. Neural Networks
4.5. Computer Vision
4.6. Pattern Recognition Technology
4.7. Metadata Analysis
4.8. Others
5. Application
5.1. Plagiarism & Academic Integrity
5.2. Deepfake & Synthetic Media Detection
5.3. Misinformation & Disinformation Detection
5.4. Toxicity & Hate Speech Moderation
5.5. Content Authenticity
5.6. Others
6. Pricing Model
6.1. Subscription-Based
6.1.1. Monthly
6.1.2. Yearly
6.2. Freemium
6.3. Pay-per-Use
7. End User
7.1. BFSI
7.2. Healthcare
7.3. IT & Telecom
7.4. Retail & E-commerce
7.5. Media & Entertainment
7.6. Others
AI Content Detectors Software Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
AI Content Detectors Software REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 25% from 2020-2034
Segmentation
By Component
Software Platforms
APIs and SDKs
Services
By Deployment Mode
Cloud-based
On-premise
Hybrid
By Enterprise Size
Large Enterprises
Small & Medium Enterprises (SMEs)
By Technology
Natural Language Processing (NLP)
Machine Learning Algorithms
Deep Learning Models
Neural Networks
Computer Vision
Pattern Recognition Technology
Metadata Analysis
Others
By Application
Plagiarism & Academic Integrity
Deepfake & Synthetic Media Detection
Misinformation & Disinformation Detection
Toxicity & Hate Speech Moderation
Content Authenticity
Others
By Pricing Model
Subscription-Based
Monthly
Yearly
Freemium
Pay-per-Use
By End User
BFSI
Healthcare
IT & Telecom
Retail & E-commerce
Media & Entertainment
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Software Platforms
5.1.2. APIs and SDKs
5.1.3. Services
5.2. Market Analysis, Insights and Forecast - by Deployment Mode
5.2.1. Cloud-based
5.2.2. On-premise
5.2.3. Hybrid
5.3. Market Analysis, Insights and Forecast - by Enterprise Size
5.3.1. Large Enterprises
5.3.2. Small & Medium Enterprises (SMEs)
5.4. Market Analysis, Insights and Forecast - by Technology
5.4.1. Natural Language Processing (NLP)
5.4.2. Machine Learning Algorithms
5.4.3. Deep Learning Models
5.4.4. Neural Networks
5.4.5. Computer Vision
5.4.6. Pattern Recognition Technology
5.4.7. Metadata Analysis
5.4.8. Others
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Plagiarism & Academic Integrity
5.5.2. Deepfake & Synthetic Media Detection
5.5.3. Misinformation & Disinformation Detection
5.5.4. Toxicity & Hate Speech Moderation
5.5.5. Content Authenticity
5.5.6. Others
5.6. Market Analysis, Insights and Forecast - by Pricing Model
5.6.1. Subscription-Based
5.6.1.1. Monthly
5.6.1.2. Yearly
5.6.2. Freemium
5.6.3. Pay-per-Use
5.7. Market Analysis, Insights and Forecast - by End User
5.7.1. BFSI
5.7.2. Healthcare
5.7.3. IT & Telecom
5.7.4. Retail & E-commerce
5.7.5. Media & Entertainment
5.7.6. Others
5.8. Market Analysis, Insights and Forecast - by Region
5.8.1. North America
5.8.2. South America
5.8.3. Europe
5.8.4. Middle East & Africa
5.8.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Software Platforms
6.1.2. APIs and SDKs
6.1.3. Services
6.2. Market Analysis, Insights and Forecast - by Deployment Mode
6.2.1. Cloud-based
6.2.2. On-premise
6.2.3. Hybrid
6.3. Market Analysis, Insights and Forecast - by Enterprise Size
6.3.1. Large Enterprises
6.3.2. Small & Medium Enterprises (SMEs)
6.4. Market Analysis, Insights and Forecast - by Technology
6.4.1. Natural Language Processing (NLP)
6.4.2. Machine Learning Algorithms
6.4.3. Deep Learning Models
6.4.4. Neural Networks
6.4.5. Computer Vision
6.4.6. Pattern Recognition Technology
6.4.7. Metadata Analysis
6.4.8. Others
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Plagiarism & Academic Integrity
6.5.2. Deepfake & Synthetic Media Detection
6.5.3. Misinformation & Disinformation Detection
6.5.4. Toxicity & Hate Speech Moderation
6.5.5. Content Authenticity
6.5.6. Others
6.6. Market Analysis, Insights and Forecast - by Pricing Model
6.6.1. Subscription-Based
6.6.1.1. Monthly
6.6.1.2. Yearly
6.6.2. Freemium
6.6.3. Pay-per-Use
6.7. Market Analysis, Insights and Forecast - by End User
6.7.1. BFSI
6.7.2. Healthcare
6.7.3. IT & Telecom
6.7.4. Retail & E-commerce
6.7.5. Media & Entertainment
6.7.6. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Software Platforms
7.1.2. APIs and SDKs
7.1.3. Services
7.2. Market Analysis, Insights and Forecast - by Deployment Mode
7.2.1. Cloud-based
7.2.2. On-premise
7.2.3. Hybrid
7.3. Market Analysis, Insights and Forecast - by Enterprise Size
7.3.1. Large Enterprises
7.3.2. Small & Medium Enterprises (SMEs)
7.4. Market Analysis, Insights and Forecast - by Technology
7.4.1. Natural Language Processing (NLP)
7.4.2. Machine Learning Algorithms
7.4.3. Deep Learning Models
7.4.4. Neural Networks
7.4.5. Computer Vision
7.4.6. Pattern Recognition Technology
7.4.7. Metadata Analysis
7.4.8. Others
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Plagiarism & Academic Integrity
7.5.2. Deepfake & Synthetic Media Detection
7.5.3. Misinformation & Disinformation Detection
7.5.4. Toxicity & Hate Speech Moderation
7.5.5. Content Authenticity
7.5.6. Others
7.6. Market Analysis, Insights and Forecast - by Pricing Model
7.6.1. Subscription-Based
7.6.1.1. Monthly
7.6.1.2. Yearly
7.6.2. Freemium
7.6.3. Pay-per-Use
7.7. Market Analysis, Insights and Forecast - by End User
7.7.1. BFSI
7.7.2. Healthcare
7.7.3. IT & Telecom
7.7.4. Retail & E-commerce
7.7.5. Media & Entertainment
7.7.6. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Software Platforms
8.1.2. APIs and SDKs
8.1.3. Services
8.2. Market Analysis, Insights and Forecast - by Deployment Mode
8.2.1. Cloud-based
8.2.2. On-premise
8.2.3. Hybrid
8.3. Market Analysis, Insights and Forecast - by Enterprise Size
8.3.1. Large Enterprises
8.3.2. Small & Medium Enterprises (SMEs)
8.4. Market Analysis, Insights and Forecast - by Technology
8.4.1. Natural Language Processing (NLP)
8.4.2. Machine Learning Algorithms
8.4.3. Deep Learning Models
8.4.4. Neural Networks
8.4.5. Computer Vision
8.4.6. Pattern Recognition Technology
8.4.7. Metadata Analysis
8.4.8. Others
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Plagiarism & Academic Integrity
8.5.2. Deepfake & Synthetic Media Detection
8.5.3. Misinformation & Disinformation Detection
8.5.4. Toxicity & Hate Speech Moderation
8.5.5. Content Authenticity
8.5.6. Others
8.6. Market Analysis, Insights and Forecast - by Pricing Model
8.6.1. Subscription-Based
8.6.1.1. Monthly
8.6.1.2. Yearly
8.6.2. Freemium
8.6.3. Pay-per-Use
8.7. Market Analysis, Insights and Forecast - by End User
8.7.1. BFSI
8.7.2. Healthcare
8.7.3. IT & Telecom
8.7.4. Retail & E-commerce
8.7.5. Media & Entertainment
8.7.6. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Software Platforms
9.1.2. APIs and SDKs
9.1.3. Services
9.2. Market Analysis, Insights and Forecast - by Deployment Mode
9.2.1. Cloud-based
9.2.2. On-premise
9.2.3. Hybrid
9.3. Market Analysis, Insights and Forecast - by Enterprise Size
9.3.1. Large Enterprises
9.3.2. Small & Medium Enterprises (SMEs)
9.4. Market Analysis, Insights and Forecast - by Technology
9.4.1. Natural Language Processing (NLP)
9.4.2. Machine Learning Algorithms
9.4.3. Deep Learning Models
9.4.4. Neural Networks
9.4.5. Computer Vision
9.4.6. Pattern Recognition Technology
9.4.7. Metadata Analysis
9.4.8. Others
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Plagiarism & Academic Integrity
9.5.2. Deepfake & Synthetic Media Detection
9.5.3. Misinformation & Disinformation Detection
9.5.4. Toxicity & Hate Speech Moderation
9.5.5. Content Authenticity
9.5.6. Others
9.6. Market Analysis, Insights and Forecast - by Pricing Model
9.6.1. Subscription-Based
9.6.1.1. Monthly
9.6.1.2. Yearly
9.6.2. Freemium
9.6.3. Pay-per-Use
9.7. Market Analysis, Insights and Forecast - by End User
9.7.1. BFSI
9.7.2. Healthcare
9.7.3. IT & Telecom
9.7.4. Retail & E-commerce
9.7.5. Media & Entertainment
9.7.6. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Software Platforms
10.1.2. APIs and SDKs
10.1.3. Services
10.2. Market Analysis, Insights and Forecast - by Deployment Mode
10.2.1. Cloud-based
10.2.2. On-premise
10.2.3. Hybrid
10.3. Market Analysis, Insights and Forecast - by Enterprise Size
10.3.1. Large Enterprises
10.3.2. Small & Medium Enterprises (SMEs)
10.4. Market Analysis, Insights and Forecast - by Technology
10.4.1. Natural Language Processing (NLP)
10.4.2. Machine Learning Algorithms
10.4.3. Deep Learning Models
10.4.4. Neural Networks
10.4.5. Computer Vision
10.4.6. Pattern Recognition Technology
10.4.7. Metadata Analysis
10.4.8. Others
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Plagiarism & Academic Integrity
10.5.2. Deepfake & Synthetic Media Detection
10.5.3. Misinformation & Disinformation Detection
10.5.4. Toxicity & Hate Speech Moderation
10.5.5. Content Authenticity
10.5.6. Others
10.6. Market Analysis, Insights and Forecast - by Pricing Model
10.6.1. Subscription-Based
10.6.1.1. Monthly
10.6.1.2. Yearly
10.6.2. Freemium
10.6.3. Pay-per-Use
10.7. Market Analysis, Insights and Forecast - by End User
10.7.1. BFSI
10.7.2. Healthcare
10.7.3. IT & Telecom
10.7.4. Retail & E-commerce
10.7.5. Media & Entertainment
10.7.6. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Sapling
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Winston AI
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Copyleaks
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Writer
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Humbot
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Originality.AI
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. GPTZero
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Content At Scale
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Content Guardian
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. AI Detector Pro
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Corrector App
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Quetext
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Others
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: AI Content Detectors Software Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America AI Content Detectors Software Revenue (million), by Component 2026 & 2034
Figure 3: North America AI Content Detectors Software Revenue Share (%), by Component 2026 & 2034
Figure 4: North America AI Content Detectors Software Revenue (million), by Deployment Mode 2026 & 2034
Figure 5: North America AI Content Detectors Software Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 6: North America AI Content Detectors Software Revenue (million), by Enterprise Size 2026 & 2034
Figure 7: North America AI Content Detectors Software Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 8: North America AI Content Detectors Software Revenue (million), by Technology 2026 & 2034
Figure 9: North America AI Content Detectors Software Revenue Share (%), by Technology 2026 & 2034
Figure 10: North America AI Content Detectors Software Revenue (million), by Application 2026 & 2034
Figure 11: North America AI Content Detectors Software Revenue Share (%), by Application 2026 & 2034
Figure 12: North America AI Content Detectors Software Revenue (million), by Pricing Model 2026 & 2034
Figure 13: North America AI Content Detectors Software Revenue Share (%), by Pricing Model 2026 & 2034
Figure 14: North America AI Content Detectors Software Revenue (million), by End User 2026 & 2034
Figure 15: North America AI Content Detectors Software Revenue Share (%), by End User 2026 & 2034
Figure 16: North America AI Content Detectors Software Revenue (million), by Country 2026 & 2034
Figure 17: North America AI Content Detectors Software Revenue Share (%), by Country 2026 & 2034
Figure 18: South America AI Content Detectors Software Revenue (million), by Component 2026 & 2034
Figure 19: South America AI Content Detectors Software Revenue Share (%), by Component 2026 & 2034
Figure 20: South America AI Content Detectors Software Revenue (million), by Deployment Mode 2026 & 2034
Figure 21: South America AI Content Detectors Software Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 22: South America AI Content Detectors Software Revenue (million), by Enterprise Size 2026 & 2034
Figure 23: South America AI Content Detectors Software Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 24: South America AI Content Detectors Software Revenue (million), by Technology 2026 & 2034
Figure 25: South America AI Content Detectors Software Revenue Share (%), by Technology 2026 & 2034
Figure 26: South America AI Content Detectors Software Revenue (million), by Application 2026 & 2034
Figure 27: South America AI Content Detectors Software Revenue Share (%), by Application 2026 & 2034
Figure 28: South America AI Content Detectors Software Revenue (million), by Pricing Model 2026 & 2034
Figure 29: South America AI Content Detectors Software Revenue Share (%), by Pricing Model 2026 & 2034
Figure 30: South America AI Content Detectors Software Revenue (million), by End User 2026 & 2034
Figure 31: South America AI Content Detectors Software Revenue Share (%), by End User 2026 & 2034
Figure 32: South America AI Content Detectors Software Revenue (million), by Country 2026 & 2034
Figure 33: South America AI Content Detectors Software Revenue Share (%), by Country 2026 & 2034
Figure 34: Europe AI Content Detectors Software Revenue (million), by Component 2026 & 2034
Figure 35: Europe AI Content Detectors Software Revenue Share (%), by Component 2026 & 2034
Figure 36: Europe AI Content Detectors Software Revenue (million), by Deployment Mode 2026 & 2034
Figure 37: Europe AI Content Detectors Software Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 38: Europe AI Content Detectors Software Revenue (million), by Enterprise Size 2026 & 2034
Figure 39: Europe AI Content Detectors Software Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 40: Europe AI Content Detectors Software Revenue (million), by Technology 2026 & 2034
Figure 41: Europe AI Content Detectors Software Revenue Share (%), by Technology 2026 & 2034
Figure 42: Europe AI Content Detectors Software Revenue (million), by Application 2026 & 2034
Figure 43: Europe AI Content Detectors Software Revenue Share (%), by Application 2026 & 2034
Figure 44: Europe AI Content Detectors Software Revenue (million), by Pricing Model 2026 & 2034
Figure 45: Europe AI Content Detectors Software Revenue Share (%), by Pricing Model 2026 & 2034
Figure 46: Europe AI Content Detectors Software Revenue (million), by End User 2026 & 2034
Figure 47: Europe AI Content Detectors Software Revenue Share (%), by End User 2026 & 2034
Figure 48: Europe AI Content Detectors Software Revenue (million), by Country 2026 & 2034
Figure 49: Europe AI Content Detectors Software Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa AI Content Detectors Software Revenue (million), by Component 2026 & 2034
Figure 51: Middle East & Africa AI Content Detectors Software Revenue Share (%), by Component 2026 & 2034
Figure 52: Middle East & Africa AI Content Detectors Software Revenue (million), by Deployment Mode 2026 & 2034
Figure 53: Middle East & Africa AI Content Detectors Software Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 54: Middle East & Africa AI Content Detectors Software Revenue (million), by Enterprise Size 2026 & 2034
Figure 55: Middle East & Africa AI Content Detectors Software Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 56: Middle East & Africa AI Content Detectors Software Revenue (million), by Technology 2026 & 2034
Figure 57: Middle East & Africa AI Content Detectors Software Revenue Share (%), by Technology 2026 & 2034
Figure 58: Middle East & Africa AI Content Detectors Software Revenue (million), by Application 2026 & 2034
Figure 59: Middle East & Africa AI Content Detectors Software Revenue Share (%), by Application 2026 & 2034
Figure 60: Middle East & Africa AI Content Detectors Software Revenue (million), by Pricing Model 2026 & 2034
Figure 61: Middle East & Africa AI Content Detectors Software Revenue Share (%), by Pricing Model 2026 & 2034
Figure 62: Middle East & Africa AI Content Detectors Software Revenue (million), by End User 2026 & 2034
Figure 63: Middle East & Africa AI Content Detectors Software Revenue Share (%), by End User 2026 & 2034
Figure 64: Middle East & Africa AI Content Detectors Software Revenue (million), by Country 2026 & 2034
Figure 65: Middle East & Africa AI Content Detectors Software Revenue Share (%), by Country 2026 & 2034
Figure 66: Asia Pacific AI Content Detectors Software Revenue (million), by Component 2026 & 2034
Figure 67: Asia Pacific AI Content Detectors Software Revenue Share (%), by Component 2026 & 2034
Figure 68: Asia Pacific AI Content Detectors Software Revenue (million), by Deployment Mode 2026 & 2034
Figure 69: Asia Pacific AI Content Detectors Software Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 70: Asia Pacific AI Content Detectors Software Revenue (million), by Enterprise Size 2026 & 2034
Figure 71: Asia Pacific AI Content Detectors Software Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 72: Asia Pacific AI Content Detectors Software Revenue (million), by Technology 2026 & 2034
Figure 73: Asia Pacific AI Content Detectors Software Revenue Share (%), by Technology 2026 & 2034
Figure 74: Asia Pacific AI Content Detectors Software Revenue (million), by Application 2026 & 2034
Figure 75: Asia Pacific AI Content Detectors Software Revenue Share (%), by Application 2026 & 2034
Figure 76: Asia Pacific AI Content Detectors Software Revenue (million), by Pricing Model 2026 & 2034
Figure 77: Asia Pacific AI Content Detectors Software Revenue Share (%), by Pricing Model 2026 & 2034
Figure 78: Asia Pacific AI Content Detectors Software Revenue (million), by End User 2026 & 2034
Figure 79: Asia Pacific AI Content Detectors Software Revenue Share (%), by End User 2026 & 2034
Figure 80: Asia Pacific AI Content Detectors Software Revenue (million), by Country 2026 & 2034
Figure 81: Asia Pacific AI Content Detectors Software Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: AI Content Detectors Software Revenue million Forecast, by Component 2020 & 2034
Table 2: AI Content Detectors Software Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 3: AI Content Detectors Software Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 4: AI Content Detectors Software Revenue million Forecast, by Technology 2020 & 2034
Table 5: AI Content Detectors Software Revenue million Forecast, by Application 2020 & 2034
Table 6: AI Content Detectors Software Revenue million Forecast, by Pricing Model 2020 & 2034
Table 7: AI Content Detectors Software Revenue million Forecast, by End User 2020 & 2034
Table 8: AI Content Detectors Software Revenue million Forecast, by Region 2020 & 2034
Table 9: North America AI Content Detectors Software Revenue million Forecast, by Component 2020 & 2034
Table 10: North America AI Content Detectors Software Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 11: North America AI Content Detectors Software Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 12: North America AI Content Detectors Software Revenue million Forecast, by Technology 2020 & 2034
Table 13: North America AI Content Detectors Software Revenue million Forecast, by Application 2020 & 2034
Table 14: North America AI Content Detectors Software Revenue million Forecast, by Pricing Model 2020 & 2034
Table 15: North America AI Content Detectors Software Revenue million Forecast, by End User 2020 & 2034
Table 16: North America AI Content Detectors Software Revenue million Forecast, by Country 2020 & 2034
Table 17: United States AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 18: Canada AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 19: Mexico AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 20: South America AI Content Detectors Software Revenue million Forecast, by Component 2020 & 2034
Table 21: South America AI Content Detectors Software Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 22: South America AI Content Detectors Software Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 23: South America AI Content Detectors Software Revenue million Forecast, by Technology 2020 & 2034
Table 24: South America AI Content Detectors Software Revenue million Forecast, by Application 2020 & 2034
Table 25: South America AI Content Detectors Software Revenue million Forecast, by Pricing Model 2020 & 2034
Table 26: South America AI Content Detectors Software Revenue million Forecast, by End User 2020 & 2034
Table 27: South America AI Content Detectors Software Revenue million Forecast, by Country 2020 & 2034
Table 28: Brazil AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 29: Argentina AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 30: Rest of South America AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 31: Europe AI Content Detectors Software Revenue million Forecast, by Component 2020 & 2034
Table 32: Europe AI Content Detectors Software Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 33: Europe AI Content Detectors Software Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 34: Europe AI Content Detectors Software Revenue million Forecast, by Technology 2020 & 2034
Table 35: Europe AI Content Detectors Software Revenue million Forecast, by Application 2020 & 2034
Table 36: Europe AI Content Detectors Software Revenue million Forecast, by Pricing Model 2020 & 2034
Table 37: Europe AI Content Detectors Software Revenue million Forecast, by End User 2020 & 2034
Table 38: Europe AI Content Detectors Software Revenue million Forecast, by Country 2020 & 2034
Table 39: United Kingdom AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 40: Germany AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 41: France AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 42: Italy AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 43: Spain AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 44: Russia AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 45: Benelux AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 46: Nordics AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 47: Rest of Europe AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 48: Middle East & Africa AI Content Detectors Software Revenue million Forecast, by Component 2020 & 2034
Table 49: Middle East & Africa AI Content Detectors Software Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 50: Middle East & Africa AI Content Detectors Software Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 51: Middle East & Africa AI Content Detectors Software Revenue million Forecast, by Technology 2020 & 2034
Table 52: Middle East & Africa AI Content Detectors Software Revenue million Forecast, by Application 2020 & 2034
Table 53: Middle East & Africa AI Content Detectors Software Revenue million Forecast, by Pricing Model 2020 & 2034
Table 54: Middle East & Africa AI Content Detectors Software Revenue million Forecast, by End User 2020 & 2034
Table 55: Middle East & Africa AI Content Detectors Software Revenue million Forecast, by Country 2020 & 2034
Table 56: Turkey AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 57: Israel AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 58: GCC AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 59: North Africa AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 60: South Africa AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 61: Rest of Middle East & Africa AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 62: Asia Pacific AI Content Detectors Software Revenue million Forecast, by Component 2020 & 2034
Table 63: Asia Pacific AI Content Detectors Software Revenue million Forecast, by Deployment Mode 2020 & 2034
Table 64: Asia Pacific AI Content Detectors Software Revenue million Forecast, by Enterprise Size 2020 & 2034
Table 65: Asia Pacific AI Content Detectors Software Revenue million Forecast, by Technology 2020 & 2034
Table 66: Asia Pacific AI Content Detectors Software Revenue million Forecast, by Application 2020 & 2034
Table 67: Asia Pacific AI Content Detectors Software Revenue million Forecast, by Pricing Model 2020 & 2034
Table 68: Asia Pacific AI Content Detectors Software Revenue million Forecast, by End User 2020 & 2034
Table 69: Asia Pacific AI Content Detectors Software Revenue million Forecast, by Country 2020 & 2034
Table 70: China AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 71: India AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 72: Japan AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 73: South Korea AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 74: ASEAN AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 75: Oceania AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Table 76: Rest of Asia Pacific AI Content Detectors Software Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our primary research constitutes the cornerstone of our market analysis, accounting for approximately 75% of the total research effort. This rigorous approach ensures that the insights are current, granular, and directly reflective of market realities and stakeholder perspectives. We conduct in-depth interviews and discussions with a diverse range of industry participants across the value chain.
Digital Forensics & Cybersecurity Firms specializing in content analysis
Key Stakeholders Engaged:
Head of Content Integrity / Trust & Safety Director
Chief Technology Officer (CTO) / VP of Engineering, AI/ML Division
Director of Academic Affairs / Dean of Students (for educational segment)
Head of Product Management (AI-powered Solutions)
These interviews are semi-structured, allowing for flexibility to explore emerging trends and unique market dynamics specific to AI Content Detectors Software. The insights gathered provide critical qualitative and quantitative data points, including market sentiments, competitive landscapes, technological advancements, adoption drivers, and challenges.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Head of Content Integrity / Trust & Safety Director
30%
Chief Technology Officer (CTO) / VP of Engineering, AI/ML Division
Secondary research complements our primary efforts, making up approximately 25% of our overall methodology. This stage involves extensive data collection from reliable and authoritative sources to build a robust foundational understanding of the market. Our process includes:
Financial & Corporate Databases: Leveraging premium platforms such as Bloomberg, Factiva, Hoovers, and PitchBook to extract company financial performance, investment trends, patent filings, and strategic initiatives.
Government & Regulatory Publications: Accessing reports and guidelines from relevant government bodies focusing on AI ethics, digital content regulation, and data privacy. Examples include:
Industry Associations & Non-Profit Organizations: Reviewing publications, whitepapers, and reports from leading industry consortiums and advocacy groups dedicated to digital media integrity and AI standards. Notable sources include:
Coalition for Content Provenance and Authenticity (C2PA) [https://c2pa.org/]
Academic Research & Scientific Journals: Analyzing peer-reviewed studies and scientific literature on AI, NLP, deep learning, and digital forensics to understand underlying technological advancements and theoretical frameworks.
Company Filings & Investor Presentations: Scrutinizing annual reports, investor calls, and SEC filings of publicly traded companies within the AI software and content technology sectors.
This multi-faceted secondary research approach provides essential data for market sizing, competitive intelligence, technological trends, and validation of primary research findings.
Demand Modeling & Market Estimation
Our market sizing and forecasting employ a rigorous combination of top-down and bottom-up methodologies, enhanced by multi-level data triangulation to ensure robustness and accuracy.
Bottom-Up Approach: This involves aggregating granular market data. For AI Content Detectors, key variables include:
Number of enterprise subscriptions or licenses sold (segmented by enterprise size, component, and deployment mode)
Average Selling Price (ASP) per license, API call, or platform tier, considering different pricing models
Growth in the volume of AI-generated content requiring detection across various applications and end-user industries
Number of active content creators/publishers leveraging these tools.
These micro-level estimations are then summed up to derive segment-specific and overall market values.
Top-Down Approach: This method begins with macro-level market data, such as the total addressable market for content technologies or digital integrity solutions, and then segments it down based on specific market drivers, penetration rates, and adoption curves for AI content detectors.
Multi-Level Data Triangulation: All market figures are triangulated across primary insights, secondary data from multiple sources, and internal proprietary databases. This cross-validation process helps mitigate biases and enhances the reliability of our estimations by ensuring consistency and coherence across various data points and methodologies. The forecast period extends from 2026 to 2034, incorporating historical data analysis and forward-looking growth projections based on anticipated technological evolution and market adoption rates. Every report is updated up to the date of purchase to reflect the latest market dynamics.
Data Accuracy & Quality Check
We are committed to delivering the highest standard of data accuracy and analytical integrity. Our rigorous quality control process ensures an estimated data accuracy level of 85-90%. This is achieved through:
Expert Validation: All market insights, forecasts, and qualitative findings are subjected to validation by a panel of internal subject matter experts and external industry consultants.
Peer Review: The entire research report undergoes a comprehensive peer review process by senior analysts to scrutinize methodology, data interpretation, and conclusions.
Statistical Analysis & Modeling: Advanced statistical techniques are applied to detect outliers, identify trends, and ensure the robustness of our quantitative models.
Continuous Feedback Loop: Insights gathered from ongoing market monitoring and client engagements are continuously integrated into our research processes, ensuring that our data remains current and relevant.
This comprehensive quality check mechanism ensures that our clients receive reliable, actionable, and meticulously verified market intelligence.
Frequently Asked Questions
1. What are the sustainability and ESG considerations for AI Content Detectors Software?
AI Content Detectors Software is primarily digital, resulting in minimal direct environmental impact from raw material sourcing. Key ESG considerations relate to data center energy consumption and responsible AI development practices, ensuring algorithmic fairness and data privacy.
2. Which region is exhibiting the fastest growth in the AI Content Detectors Software market?
Asia-Pacific is projected to be a rapidly growing region for AI Content Detectors Software. This is driven by expanding digital economies, increased academic integrity demands, and rising concerns over misinformation across countries like China and India.
3. What raw material sourcing and supply chain factors impact AI Content Detectors Software?
AI Content Detectors Software is a digital product, thus direct raw material sourcing is not applicable. The supply chain primarily involves software development talent, cloud infrastructure providers, and data providers for model training.
4. What significant challenges constrain the AI Content Detectors Software market?
Key challenges include the rapid evolution of generative AI models, leading to a continuous need for detector updates. Issues such as false positives, detection accuracy, user adoption, and data privacy concerns also present notable restraints.
5. How does the regulatory environment influence the AI Content Detectors Software market?
Regulatory frameworks like GDPR and CCPA significantly impact data handling and privacy within AI content detection. Furthermore, evolving academic integrity policies and ethical AI guidelines influence feature development and market adoption for compliance-focused applications.
6. What is the projected market size and CAGR for AI Content Detectors Software through 2033?
The AI Content Detectors Software market, valued at $500 million in 2025, is projected to grow at a 25% CAGR. This expansion is expected to result in a market valuation of approximately $4.66 billion by 2033, driven by sustained demand.