Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Gas Pooling Mechanism Market: Size, CAGR & 2034 Forecast
Gas Pooling Mechanism Market
Gas Pooling Mechanism Market: Size, CAGR & 2034 Forecast
Gas Pooling Mechanism Market by Pool Type (Voluntary Pooled, Forced Pooled, Hybrid Pooling, Drilling, Proration, Field Enhanced Recovery, Specially Defined), by Gas Type (Natural Gas, Liquefied Natural Gas, Liquefied Petroleum Gas), by Purpose (Risk Management, Cost Optimization, Enhanced Market Access, Improved Liquidity), by Market Structure (Centralized Pooling, Decentralized Pooling, Multi-Pool Model), by Technology (Electronic Trading Platforms, Data Analytics, Smart Contracts), by End Use (Power Generation, Transportation, Industrial, Fertilizers, Hydrogen Production, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands, Spain, Turkey, Russia), by Asia Pacific (China, Japan, India, South Korea, Singapore, Australia, Indonesia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Egypt, Israel) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 264
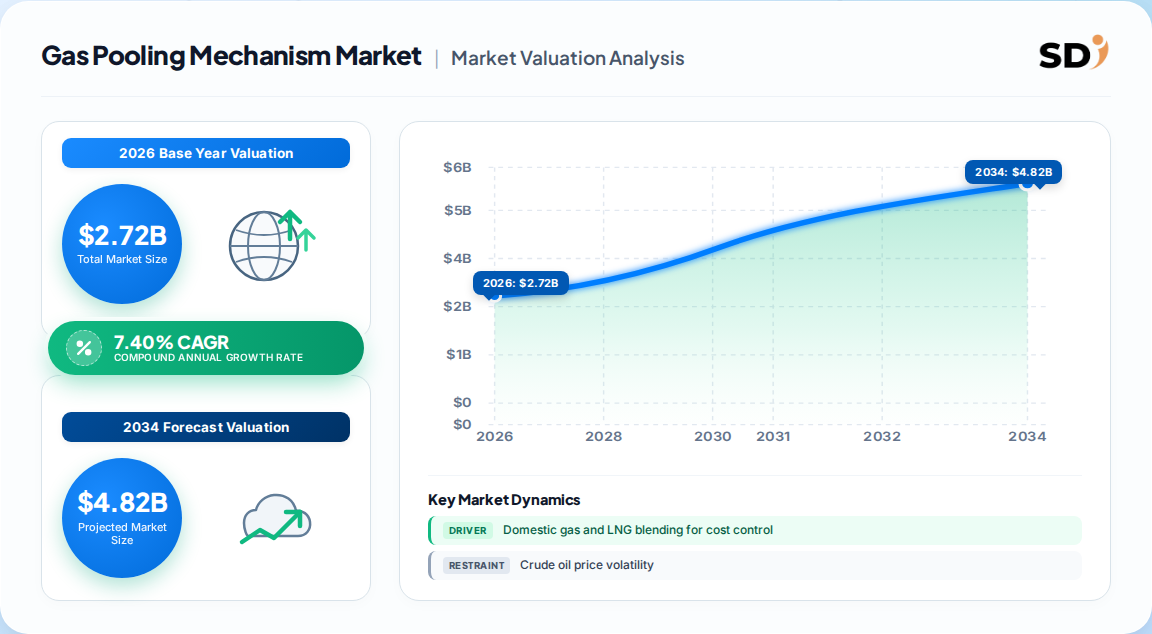
2.72 Billion is our base-year (2026) valuation for the Global Gas Pooling Mechanism Market, up from 2.53 Billion in 2025.
Forecast growth runs at a 7.40% CAGR (2026–2034), taking the market to roughly 4.82 Billion by 2034.
Voluntary pooling is the leading type, accounting for about 41.5% of type revenue; forced pooling grows fastest.
Power generation is the largest end-use pool; fertilizers and hydrogen production are the fastest-moving applications.
North America leads with roughly 30% regional share; Asia-Pacific is the fastest-growing region on urbanization and agricultural gas demand.
Concentration is high: Shell, ExxonMobil, Chevron, Saudi Aramco, Gazprom, PetroChina, ONGC and GAIL dominate the pool-operator tier.
Why this matters for decision-makers: Pool operators that master domestic-plus-LNG blending economics now will lock in multi-year fertilizer and power off-take contracts before regulated uniform pricing compresses margins.
Gas Pooling Mechanism Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.530 B
2025
2.720 B
2026
2.920 B
2027
3.140 B
2028
3.370 B
2029
3.620 B
2030
3.890 B
2031
Gas Pooling Mechanism Market Size (In Billion)
Year
Market Size
2025
2.530 B
2026
2.720 B
2027
2.920 B
2028
3.140 B
2029
3.370 B
2030
3.620 B
2031
3.890 B
What is the Gas Pooling Mechanism Market?
The gas pooling mechanism market covers the systems, platforms and operator services that aggregate natural gas from multiple domestic fields and imported LNG terminals into a single blended supply, then allocate it at coordinated pooled pricing to priority sectors such as power generation, fertilizers and industry.
Scope: what this report covers and excludes
This report covers global pooling frameworks across voluntary, forced, proration, drilling and field-enhanced recovery structures, spanning physical, financial and hybrid pooling models and their enabling technology: electronic trading platforms, data analytics and smart contracts. It covers end-use pools in power generation, transportation, industrial, fertilizer and hydrogen production. This analysis does not cover upstream exploration and production expenditure, standalone LNG liquefaction capex, pipeline construction markets, or retail gas distribution tariffs.
How big is the market for Gas Pooling Mechanism Market?
Estimates diverge sharply because analysts disagree on whether financial pooling and gas-trading volumes belong inside the boundary. Our analysis favors the 2.53 Billion (2025) base, which anchors a defensible 7.40% trajectory to 4.82 Billion by 2034.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
2.53 Billion
2025
2034
7.40%
Physical pooling of domestic gas + LNG, operator services
Physical, financial and hybrid pooling plus trading
A competing analysis
The 2.5 Billion cluster is the most defensible because it measures operator-mediated pooling services rather than gross traded gas value. The 10 Billion tier appears to double-count gas commodity value already captured in wholesale pricing. This divergence implies buyers must fix the definitional boundary before comparing vendor contracts or national policy impact.
How is the market segmented?
Segmentation splits along four axes: pool type (which governs how operators are compelled or choose to join), gas type, purpose of pooling, and the market structure that administers allocation.
Parent
Children
By Pool Type
Voluntary Pooled, Forced Pooled, Hybrid Pooling, Drilling, Proration, Field Enhanced Recovery, Specially Defined
By Gas Type
Natural Gas, Liquefied Natural Gas (LNG), Liquefied Petroleum Gas (LPG)
Centralized Pooling, Decentralized Pooling, Multi-Pool Model
By Technology
Electronic Trading Platforms, Data Analytics, Smart Contracts
By End Use
Power Generation, Transportation, Industrial, Fertilizers, Hydrogen Production, Others
Voluntary pooling dominates because operators retain allocation discretion, while forced pooling accelerates where regulators mandate supply security. Centralized models are gaining share as pool operators coordinate blending, pricing and delivery in one place — a structural shift that favors incumbents with terminal access.
Which region leads in Gas Pooling Mechanism Market?
North America leads with roughly 30% revenue share, underpinned by shale gas depth, dense pipeline networks and mature wholesale trading; Asia-Pacific is the fastest-growing region, driven by urbanization, fertilizer subsidy reform and rising LNG imports.
Gas Pooling Mechanism Market Regional Market Share
Loading chart...
Gas Pooling Mechanism Market Regional Market Share
Region
Market Share (%)
North America
0.3%
Asia-Pacific
0.27%
Europe
0.21%
Middle East & Africa
0.14%
South America
0.08%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Netherlands, Spain, Turkey, Russia
Asia Pacific — China, Japan, India, South Korea, Singapore, Australia, Indonesia
Latin America — Brazil, Argentina, Mexico
Middle East & Africa — Saudi Arabia, UAE, South Africa, Egypt, Israel
Region
Share
North America
30%
Asia-Pacific
27%
Europe
21%
Middle East & Africa
14%
South America
8%
Our analysis suggests the Asia-Pacific figure understates momentum: India's 2026 fertilizer pooling order and China's import growth could add 200–300 basis points of share by 2030, pressuring North American dominance.
What is driving growth — and what is holding it back?
The decisive driver is affordability: blending cheap domestic gas with expensive LNG keeps fertilizer and power feedstock viable without subsidy escalation. Restraints are price volatility and tightening environmental regulation.
Factor
Direction
Evidence strength
Mechanism
Domestic + LNG blending for cost control
Driver
High
Lowers blended feedstock cost for priority sectors
Industrialization and population growth
Driver
High
Raises baseline gas consumption and pool volumes
Gas-as-bridge-fuel decarbonization
Driver
Medium
Substitutes coal/oil in power and industry
Regulatory support and pooling mandates
Driver
High
Creates compulsory pool participation
Crude oil price volatility
Restraint
Medium
Undermines long-term pooling cost models
Environmental and depletion regulation
Restraint
Medium
Raises compliance cost and pricing uncertainty
The balance favors growth, but the mechanism is policy-dependent rather than purely commercial. Where pooling is voluntary, adoption tracks LNG price spreads; where mandated, volumes arrive but margins thin. This implies operators should hedge policy risk, not just commodity risk.
Who are the leading vendors?
The competitive field splits into integrated majors that supply pooled volumes, national oil companies that anchor domestic supply, and utilities or specialized operators that run the pooling and allocation function.
Company
Category
Pooling position
Shell plc
Integrated major
Global LNG and trading pool participation
ExxonMobil
Integrated major
Production plus terminal-linked pooling
Chevron
Integrated major
Upstream and LNG supply aggregation
Saudi Aramco
National oil company
Domestic allocation and priority-sector supply
Gazprom
National oil company
Pipeline pooling and export coordination
PetroChina / Sinopec
National oil company
Domestic field plus import blending
ONGC / GAIL
National oil company / operator
India fertilizer pooling coordination
Petronet LNG
LNG terminal operator
Regasification-fed pool supply
Differentiation rests on terminal access, regulatory relationships and allocation software. The moat is structural: whoever controls regasification capacity and the allocation algorithm controls the blended price. Our analysis suggests digital platforms and smart-contract settlement will become the sharpest differentiator by 2030, eroding pure asset-based advantage.
What do buyers and operators need to know?
Selection should hinge on four criteria: verified pool volume availability, transparent blending formulas, settlement and audit capability, and regulatory compliance across jurisdictions. Buyers should insist on contractual clarity over how LNG price spikes are socialized across pool participants — the single largest source of dispute. Switching costs are high once a buyer's pipeline nominations and tariff schedules are embedded in a pool operator's system, so onboarding terms matter more than headline pricing. Operators, conversely, face compliance risk from uniform-pricing mandates and must model regulatory scenarios before committing terminal capacity. Mission-critical risk: pool dependency concentrates supply risk if a single terminal or domestic field underperforms.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the conservative 2.5 Billion base and 7.4% trajectory, and we judge the 10 Billion tier an overstatement from double-counted commodity value. The strongest counter-argument is that financial pooling and traded gas volumes genuinely expand the addressable market; if regulators formalize financial pooling contracts, the larger figure gains credibility. Absent that, it misleads capital allocation.
Second-order effects matter more than headline CAGR. Mandated pooling compresses operator margins while expanding volume, favoring asset-heavy incumbents over trading intermediaries. Simultaneously, the fertilizer-to-hydrogen end-use migration could reprice pool premiums upward after 2029 as hydrogen projects compete for the same blended supply.
Actionable strategy:
Investors should weight exposure toward pool operators with owned regasification capacity and allocation software, not pure traders.
Operators should lock multi-year fertilizer and power off-take contracts before uniform pricing rules tighten margins.
Vendors of analytics and smart-contract platforms should target Asia-Pacific state-linked pool operators where digitization is earliest-stage.
What would change our conclusion: a credible regulator-backed financial pooling framework, or verifiable data showing traded gas volumes are contracted directly through pooling mechanisms. Either would justify migrating toward the higher estimate band. Precise sub-segment forecasting and country-level policy scenario modeling require the full report.
Gas Pooling Mechanism Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Gas Pooling Mechanism Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.40% from 2020-2034
Segmentation
By Pool Type
Voluntary Pooled
Forced Pooled
Hybrid Pooling
Drilling
Proration
Field Enhanced Recovery
Specially Defined
By Gas Type
Natural Gas
Liquefied Natural Gas
Liquefied Petroleum Gas
By Purpose
Risk Management
Cost Optimization
Enhanced Market Access
Improved Liquidity
By Market Structure
Centralized Pooling
Decentralized Pooling
Multi-Pool Model
By Technology
Electronic Trading Platforms
Data Analytics
Smart Contracts
By End Use
Power Generation
Transportation
Industrial
Fertilizers
Hydrogen Production
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Netherlands
Spain
Turkey
Russia
Asia Pacific
China
Japan
India
South Korea
Singapore
Australia
Indonesia
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Pool Type
5.1.1. Voluntary Pooled
5.1.2. Forced Pooled
5.1.3. Hybrid Pooling
5.1.4. Drilling
5.1.5. Proration
5.1.6. Field Enhanced Recovery
5.1.7. Specially Defined
5.2. Market Analysis, Insights and Forecast - by Gas Type
5.2.1. Natural Gas
5.2.2. Liquefied Natural Gas
5.2.3. Liquefied Petroleum Gas
5.3. Market Analysis, Insights and Forecast - by Purpose
5.3.1. Risk Management
5.3.2. Cost Optimization
5.3.3. Enhanced Market Access
5.3.4. Improved Liquidity
5.4. Market Analysis, Insights and Forecast - by Market Structure
5.4.1. Centralized Pooling
5.4.2. Decentralized Pooling
5.4.3. Multi-Pool Model
5.5. Market Analysis, Insights and Forecast - by Technology
5.5.1. Electronic Trading Platforms
5.5.2. Data Analytics
5.5.3. Smart Contracts
5.6. Market Analysis, Insights and Forecast - by End Use
5.6.1. Power Generation
5.6.2. Transportation
5.6.3. Industrial
5.6.4. Fertilizers
5.6.5. Hydrogen Production
5.6.6. Others
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Pool Type
6.1.1. Voluntary Pooled
6.1.2. Forced Pooled
6.1.3. Hybrid Pooling
6.1.4. Drilling
6.1.5. Proration
6.1.6. Field Enhanced Recovery
6.1.7. Specially Defined
6.2. Market Analysis, Insights and Forecast - by Gas Type
6.2.1. Natural Gas
6.2.2. Liquefied Natural Gas
6.2.3. Liquefied Petroleum Gas
6.3. Market Analysis, Insights and Forecast - by Purpose
6.3.1. Risk Management
6.3.2. Cost Optimization
6.3.3. Enhanced Market Access
6.3.4. Improved Liquidity
6.4. Market Analysis, Insights and Forecast - by Market Structure
6.4.1. Centralized Pooling
6.4.2. Decentralized Pooling
6.4.3. Multi-Pool Model
6.5. Market Analysis, Insights and Forecast - by Technology
6.5.1. Electronic Trading Platforms
6.5.2. Data Analytics
6.5.3. Smart Contracts
6.6. Market Analysis, Insights and Forecast - by End Use
6.6.1. Power Generation
6.6.2. Transportation
6.6.3. Industrial
6.6.4. Fertilizers
6.6.5. Hydrogen Production
6.6.6. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Pool Type
7.1.1. Voluntary Pooled
7.1.2. Forced Pooled
7.1.3. Hybrid Pooling
7.1.4. Drilling
7.1.5. Proration
7.1.6. Field Enhanced Recovery
7.1.7. Specially Defined
7.2. Market Analysis, Insights and Forecast - by Gas Type
7.2.1. Natural Gas
7.2.2. Liquefied Natural Gas
7.2.3. Liquefied Petroleum Gas
7.3. Market Analysis, Insights and Forecast - by Purpose
7.3.1. Risk Management
7.3.2. Cost Optimization
7.3.3. Enhanced Market Access
7.3.4. Improved Liquidity
7.4. Market Analysis, Insights and Forecast - by Market Structure
7.4.1. Centralized Pooling
7.4.2. Decentralized Pooling
7.4.3. Multi-Pool Model
7.5. Market Analysis, Insights and Forecast - by Technology
7.5.1. Electronic Trading Platforms
7.5.2. Data Analytics
7.5.3. Smart Contracts
7.6. Market Analysis, Insights and Forecast - by End Use
7.6.1. Power Generation
7.6.2. Transportation
7.6.3. Industrial
7.6.4. Fertilizers
7.6.5. Hydrogen Production
7.6.6. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Pool Type
8.1.1. Voluntary Pooled
8.1.2. Forced Pooled
8.1.3. Hybrid Pooling
8.1.4. Drilling
8.1.5. Proration
8.1.6. Field Enhanced Recovery
8.1.7. Specially Defined
8.2. Market Analysis, Insights and Forecast - by Gas Type
8.2.1. Natural Gas
8.2.2. Liquefied Natural Gas
8.2.3. Liquefied Petroleum Gas
8.3. Market Analysis, Insights and Forecast - by Purpose
8.3.1. Risk Management
8.3.2. Cost Optimization
8.3.3. Enhanced Market Access
8.3.4. Improved Liquidity
8.4. Market Analysis, Insights and Forecast - by Market Structure
8.4.1. Centralized Pooling
8.4.2. Decentralized Pooling
8.4.3. Multi-Pool Model
8.5. Market Analysis, Insights and Forecast - by Technology
8.5.1. Electronic Trading Platforms
8.5.2. Data Analytics
8.5.3. Smart Contracts
8.6. Market Analysis, Insights and Forecast - by End Use
8.6.1. Power Generation
8.6.2. Transportation
8.6.3. Industrial
8.6.4. Fertilizers
8.6.5. Hydrogen Production
8.6.6. Others
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Pool Type
9.1.1. Voluntary Pooled
9.1.2. Forced Pooled
9.1.3. Hybrid Pooling
9.1.4. Drilling
9.1.5. Proration
9.1.6. Field Enhanced Recovery
9.1.7. Specially Defined
9.2. Market Analysis, Insights and Forecast - by Gas Type
9.2.1. Natural Gas
9.2.2. Liquefied Natural Gas
9.2.3. Liquefied Petroleum Gas
9.3. Market Analysis, Insights and Forecast - by Purpose
9.3.1. Risk Management
9.3.2. Cost Optimization
9.3.3. Enhanced Market Access
9.3.4. Improved Liquidity
9.4. Market Analysis, Insights and Forecast - by Market Structure
9.4.1. Centralized Pooling
9.4.2. Decentralized Pooling
9.4.3. Multi-Pool Model
9.5. Market Analysis, Insights and Forecast - by Technology
9.5.1. Electronic Trading Platforms
9.5.2. Data Analytics
9.5.3. Smart Contracts
9.6. Market Analysis, Insights and Forecast - by End Use
9.6.1. Power Generation
9.6.2. Transportation
9.6.3. Industrial
9.6.4. Fertilizers
9.6.5. Hydrogen Production
9.6.6. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Pool Type
10.1.1. Voluntary Pooled
10.1.2. Forced Pooled
10.1.3. Hybrid Pooling
10.1.4. Drilling
10.1.5. Proration
10.1.6. Field Enhanced Recovery
10.1.7. Specially Defined
10.2. Market Analysis, Insights and Forecast - by Gas Type
10.2.1. Natural Gas
10.2.2. Liquefied Natural Gas
10.2.3. Liquefied Petroleum Gas
10.3. Market Analysis, Insights and Forecast - by Purpose
10.3.1. Risk Management
10.3.2. Cost Optimization
10.3.3. Enhanced Market Access
10.3.4. Improved Liquidity
10.4. Market Analysis, Insights and Forecast - by Market Structure
10.4.1. Centralized Pooling
10.4.2. Decentralized Pooling
10.4.3. Multi-Pool Model
10.5. Market Analysis, Insights and Forecast - by Technology
10.5.1. Electronic Trading Platforms
10.5.2. Data Analytics
10.5.3. Smart Contracts
10.6. Market Analysis, Insights and Forecast - by End Use
10.6.1. Power Generation
10.6.2. Transportation
10.6.3. Industrial
10.6.4. Fertilizers
10.6.5. Hydrogen Production
10.6.6. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Shell plc
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. ExxonMobil
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Chevron
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Saudi Aramco
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Gazprom
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. PetroChina
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Sinopec
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. ONGC
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. GAIL India Limited
11.1.9.1. Company Overview
11.1.9.2. Products
12. Research Methodology
List of Figures
Figure 1: Gas Pooling Mechanism Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Gas Pooling Mechanism Market Revenue (Billion), by Pool Type 2026 & 2034
Figure 3: North America Gas Pooling Mechanism Market Revenue Share (%), by Pool Type 2026 & 2034
Figure 4: North America Gas Pooling Mechanism Market Revenue (Billion), by Gas Type 2026 & 2034
Figure 5: North America Gas Pooling Mechanism Market Revenue Share (%), by Gas Type 2026 & 2034
Figure 6: North America Gas Pooling Mechanism Market Revenue (Billion), by Purpose 2026 & 2034
Figure 7: North America Gas Pooling Mechanism Market Revenue Share (%), by Purpose 2026 & 2034
Figure 8: North America Gas Pooling Mechanism Market Revenue (Billion), by Market Structure 2026 & 2034
Figure 9: North America Gas Pooling Mechanism Market Revenue Share (%), by Market Structure 2026 & 2034
Figure 10: North America Gas Pooling Mechanism Market Revenue (Billion), by Technology 2026 & 2034
Figure 11: North America Gas Pooling Mechanism Market Revenue Share (%), by Technology 2026 & 2034
Figure 12: North America Gas Pooling Mechanism Market Revenue (Billion), by End Use 2026 & 2034
Figure 13: North America Gas Pooling Mechanism Market Revenue Share (%), by End Use 2026 & 2034
Figure 14: North America Gas Pooling Mechanism Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Gas Pooling Mechanism Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Gas Pooling Mechanism Market Revenue (Billion), by Pool Type 2026 & 2034
List of Tables
Table 1: Gas Pooling Mechanism Market Revenue Billion Forecast, by Pool Type 2020 & 2034
Table 2: Gas Pooling Mechanism Market Revenue Billion Forecast, by Gas Type 2020 & 2034
Table 3: Gas Pooling Mechanism Market Revenue Billion Forecast, by Purpose 2020 & 2034
Table 4: Gas Pooling Mechanism Market Revenue Billion Forecast, by Market Structure 2020 & 2034
Table 5: Gas Pooling Mechanism Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 6: Gas Pooling Mechanism Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 7: Gas Pooling Mechanism Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Gas Pooling Mechanism Market Revenue Billion Forecast, by Pool Type 2020 & 2034
Table 9: North America Gas Pooling Mechanism Market Revenue Billion Forecast, by Gas Type 2020 & 2034
Table 10: North America Gas Pooling Mechanism Market Revenue Billion Forecast, by Purpose 2020 & 2034
Table 11: North America Gas Pooling Mechanism Market Revenue Billion Forecast, by Market Structure 2020 & 2034
Table 12: North America Gas Pooling Mechanism Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 13: North America Gas Pooling Mechanism Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 14: North America Gas Pooling Mechanism Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Gas Pooling Mechanism Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Gas Pooling Mechanism Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the Gas Pooling Mechanism Market?
The market was valued at 2.53 Billion in 2025 and is estimated at 2.72 Billion in 2026, projected to reach 4.82 Billion by 2034 at a 7.40% CAGR. Figures measure operator-mediated pooling services rather than gross traded gas value.
2. Which segment leads the Gas Pooling Mechanism Market?
Voluntary pooling leads with about 41.5% of type revenue because operators retain allocation flexibility without regulatory compulsion. Power generation is the largest end-use pool, while fertilizers and hydrogen production grow fastest.
3. Which region dominates gas pooling adoption?
North America leads with roughly 30% regional share, supported by shale production, dense pipelines and mature wholesale trading. Asia-Pacific is the fastest-growing region, driven by urbanization, fertilizer reform and rising LNG imports.
4. Who are the leading players in the Gas Pooling Mechanism Market?
Integrated majors including Shell, ExxonMobil and Chevron compete with national oil companies such as Saudi Aramco, Gazprom, PetroChina and ONGC. GAIL and Petronet LNG anchor India's fertilizer pooling and regasification-linked allocation.
5. Why is gas pooling important for fertilizer and power producers?
Pooling blends low-cost domestic gas with expensive imported LNG, producing a stable blended price that keeps feedstock affordable. This reduces subsidy dependence and shields priority sectors from spot LNG volatility, which is the market's core value proposition.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. We conducted structured depth interviews with stakeholders across the pooling value chain: domestic gas producers, LNG regasification terminal operators, pool administrators and allocation-software vendors, industrial gas consumers, and energy regulators. Within these organizations we engaged decision-makers holding VP of Gas Sourcing, Head of Commercial Operations, Terminal Allocation Director, and Regulatory Affairs Lead designations. Interviews probed blending economics, contract structures, allocation disputes and policy exposure.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Gas Sourcing & Procurement
38%
Commercial Operations Leads
30%
Terminal Allocation Directors
18%
Regulatory Affairs Managers
14%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Domestic Gas Producers
35%
LNG Terminal & Regasification Operators
30%
Pool Administrators & Utilities
22%
Allocation Software & Analytics Vendors
13%
Secondary Benchmarking & Public Trade Validation
We validated findings against UN Comtrade gas trade flows, WTO energy services documentation, US ITC filings, Eurostat energy statistics, corporate 10-K and annual investor disclosures, patent databases covering allocation and smart-contract systems, and recognized industry associations including the International Gas Union and national petroleum federations.
Demand Modeling & Market Sizing Triangulation
We triangulated a Top-Down allocation from macroeconomic gas consumption and sector demand against a Bottom-Up model of operator capacity, pooled volumes and service pricing, reconciling both to a fixed base-year boundary that excludes gross traded commodity value.


 Gas Pooling Mechanism Market