 Air Electrode Battery Market
 Size & 2030 Forecast
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 190

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Air Electrode Battery Market
Sandeep Singh
Research Analyst
| Year | Market Size |
|---|---|
| 2024 | 1.500 B |
| 2025 | 1.700 B |
| 2026 | 1.800 B |
| 2027 | 2.100 B |
| 2028 | 2.300 B |
| 2029 | 2.500 B |
| 2030 | 2.800 B |

The air electrode battery market covers energy storage devices that use oxygen from ambient air as the cathode reactant, paired with a metal or fuel anode. Dominant chemistries include zinc-air, lithium-air, aluminum-air, and iron-air, spanning primary, rechargeable, and fuel-cell configurations.
This report covers the global air electrode battery market across primary (non-rechargeable), secondary (rechargeable), and fuel-cell types, and applications in transportation, medical devices, military devices, and stationary or other uses. It covers value forecasts through 2030–2034 across five regions.
This analysis does not cover conventional lithium-ion cell manufacturing, lead-acid batteries, flow batteries, or upstream mining of lithium, zinc, and iron ores except where directly relevant to electrode cost structures.
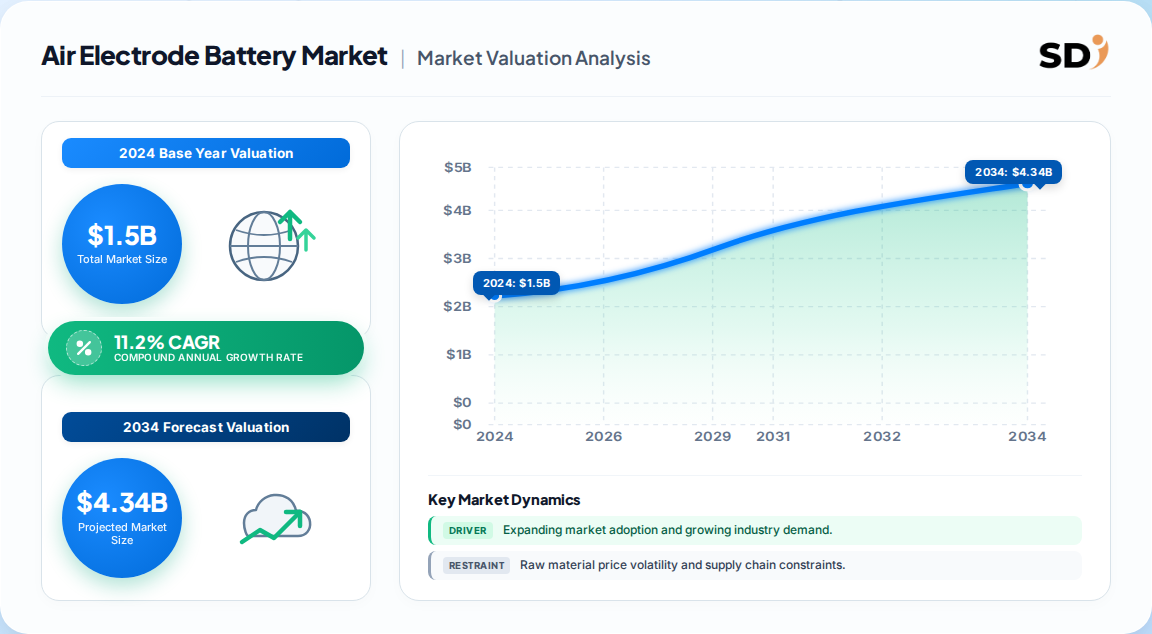
The most defensible base figure is approximately USD 1.5 billion for 2024, with the 2030 forecast split between USD 2.8 billion (11.2% CAGR) and USD 2.9 billion (7.31% CAGR, 2034 horizon). Divergence stems from whether fuel-cell stacks are counted as air electrode batteries.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.5B → USD 2.8B | 2024 | 2030 | 11.2% | Rechargeable, fuel cell, and non-rechargeable air electrode batteries; transportation, medical, military | One published estimate |
| USD 1.5B → USD 2.9B | 2025 | 2034 | 7.31% | Primary rechargeable, secondary rechargeable, fuel cells; medical, transportation, military, others | A competing analysis |
| USD 135.2B → USD 431.2B | 2024 | 2034 | 12.3% | Broad metal-air and air-electrode systems including grid storage and EV platforms | A competing analysis |
Our analysis suggests the USD 1.5 billion base is credible for the narrow device-level market. The USD 135.2 billion figure almost certainly embeds system-level grid storage and EV battery value, not electrode-level revenue. Buyers should reject blended figures when sizing addressable electrode demand.
Segmentation splits by battery type and application. Fuel cells led in 2024 at 45.2% by one estimate, while rechargeable chemistries lead in broader metal-air definitions at 58.9%, reflecting classification inconsistency buyers must normalize.
| Parent Segment | Children | 2024 Share / Growth |
|---|---|---|
| By Type | Primary (non-rechargeable), Secondary (rechargeable), Fuel Cells | Fuel cells 45.2%; rechargeable CAGR 10.3% |
| By Application | Transportation, Medical Devices, Military Devices, Others | Transportation ~42.6%; military CAGR ~11.1% |
Asia-Pacific leads the global air electrode battery market, holding an estimated 33.7% to 43.9% revenue share in 2024, driven by EV manufacturing density in China, Japan, and South Korea. Exact sub-regional shares require the full report.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.44% |
| North America | 0.27% |
| Europe | 0.19% |
| Latin America | 0.06% |
| Middle East & Africa | 0.04% |
| Region | 2024 Share (consensus range) | Direction |
|---|---|---|
| Asia-Pacific | 33.7%–43.9% | Leading |
| North America | ~27% | Significant |
| Europe | ~19% | Growing at ~10.2% CAGR |
| Latin America | ~6% | Emerging |
| Middle East & Africa | ~4% | Nascent |
Growth is driven by EV adoption, renewable-integration storage demand, and clean-energy policy. Restraints center on round-trip efficiency, air-electrode durability, catalyst cost, and long project-qualification cycles. The driver set is stronger near-term; the restraint set governs which chemistries reach scale.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| EV and sustainable transport mandates | Driver | High | Pulls high-energy-density lithium-air and zinc-air demand |
| Renewable integration and grid storage | Driver | High | Utilities need multi-hour and multi-day storage |
| Government incentives and R&D funding | Driver | High | Lowers capex and de-risks pilot lines |
| Round-trip efficiency gap vs lithium-ion | Restraint | Medium | Limits daily-cycling use cases |
| Air-electrode durability and catalyst cost | Restraint | Medium | Raises lifecycle cost and slows bankability |
| Long utility qualification cycles | Restraint | Medium | Delays volume electrode orders by 2–3 years |
Vendor leadership is fragmented across fuel-cell incumbents, metal-air specialists, and vertically integrated iron-air developers. Differentiation rests on air-electrode catalyst durability, manufacturing yield at multi-GWh scale, and long-duration project pipelines rather than laboratory energy density.
| Player Type | Representative Focus | Strategic Moat |
|---|---|---|
| Fuel-cell incumbents | Stationary and transport stacks | Installed base and service networks |
| Metal-air specialists | Zinc-air and lithium-air cells | Catalyst IP and cycle-life data |
| Iron-air developers | Multi-day grid storage | Long-duration project pipeline and DoE-backed capacity |
| Medical-device battery suppliers | Primary zinc-air button cells | Regulatory certifications and reliability |
Procurement decisions hinge on four criteria: demonstrated cycle life under real duty cycles, air-electrode catalyst durability, supplier manufacturing scale, and regulatory certification for medical or transport use. Switching costs are high once a chemistry is designed into a device or project.
Operators should demand third-party lifetime evidence rather than datasheet energy density, because air-electrode degradation under repeated oxygen reduction and evolution remains the dominant failure mode. Regulatory exposure includes EU battery directives, UN transport testing for lithium-air prototypes, and medical-device quality-system requirements. Single-source risk is elevated in catalyst supply; dual-sourcing air-electrode catalyst lots is prudent.
The balance of evidence favors the narrow, device-level definition of the air electrode battery market at roughly USD 1.5 billion in 2024, growing near 10–11% annually. The strongest counter-argument is that iron-air long-duration storage pipelines — expanding into tens of GWh — could make the broader metal-air definition the economically relevant one within five years.
Our analysis suggests the 2026–2027 window is decisive. Iron-air electrode manufacturing is moving from batch fabrication to semi-automated lines, and a US-backed 20 GWh capacity target by 2027 would validate the high-CAGR case. Until then, the 7.31% CAGR view is the conservative floor, not the central scenario.
Evidence that would change this conclusion: sustained iron-air project cancellations, or a step-change in lithium-ion cost that erodes the long-duration storage case.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.2% from 2020-2034 |
| Segmentation |
|
The global air electrode battery market was valued at approximately USD 1.5 billion in 2024 and is projected to reach USD 2.8 billion by 2030 at an 11.2% CAGR under the narrow device-level definition.
Asia-Pacific leads, holding an estimated 33.7% to 43.9% of global revenue in 2024, driven by EV manufacturing concentration in China, Japan, and South Korea, ahead of North America and Europe.
Military devices are projected to grow fastest at roughly 11.1% CAGR, while rechargeable chemistries grow near 10.3% CAGR as lithium-air and zinc-air systems scale for EVs and grid storage.
Air electrode batteries use oxygen from ambient air as the cathode reactant. Metal-air batteries are the largest sub-family, pairing that air electrode with zinc, lithium, aluminum, or iron anodes.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split. In-depth interviews were conducted with raw material suppliers, specialized cell and electrode producers, contract manufacturers, and global distributors across the air electrode battery value chain. Decision-maker interviews included VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring demand, cost, and technology signals are triangulated at the point of decision.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Quality Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Metal Powder Suppliers | 25% |
| Cell & Electrode Producers | 40% |
| Contract Manufacturers | 20% |
| Distributors & Integrators | 15% |
Secondary validation draws on UN Comtrade and US ITC trade flows for zinc, lithium, and iron-based inputs, Eurostat industrial statistics, corporate 10-K and SEC filings, patent databases, and recognized technical standards from IEC and UL for cell safety and transport testing.
We run simultaneous top-down allocation from macroeconomic and end-use segment data and bottom-up modeling from manufacturer capacity, product pricing, and end-use consumption to reconcile market value and volume.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
