 Fluid Power Pump And Motor Market
 Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 272

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Fluid Power Pump And Motor Market
Sandeep Singh
Research Analyst
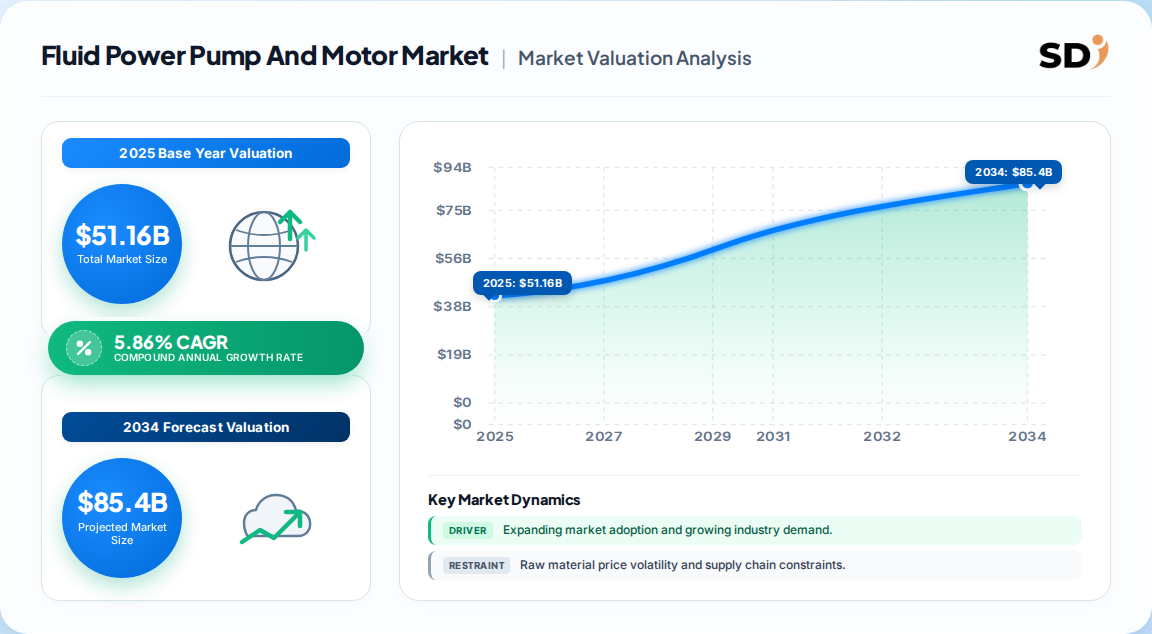
| Year | Market Size |
|---|---|
| 2025 | 51.16 B |
| 2026 | 54.16 B |
| 2027 | 57.33 B |
| 2028 | 60.69 B |
| 2029 | 64.25 B |
| 2030 | 68.01 B |
| 2031 | 72.00 B |

The Fluid Power Pump And Motor market covers hydraulic and pneumatic components that convert mechanical energy into fluid power and back into rotary or linear motion — gear, piston and vane pumps plus matched motors — sold into off-highway vehicles, mining, marine, aerospace and military applications.
It is a component market, not a system market. Buyers purchase displacement, pressure rating, contamination tolerance and control architecture rather than a finished machine, which makes specification behaviour the single strongest predictor of vendor selection. Our analysis suggests procurement teams increasingly bundle pumps, motors and electronic control units into one award, compressing the addressable field to suppliers with full fluid-power portfolios.
This analysis covers hydraulic and pneumatic pumps and motors by type (gear, piston, vane, other), by application (military, aerospace, mining, off-highway vehicles, marine and other), and by power transmission type (hydraulics and pneumatics) across five regions.
This analysis does not cover complete hydraulic power units, valves, cylinders, accumulators, fluid connectors, lubricants, or electric actuators as standalone categories. It also excludes automotive volume pumps, municipal water/wastewater pumps and semiconductor vacuum pumps, which belong to adjacent pump taxonomies with different duty profiles, buyers and certification regimes. Readers sizing those categories should treat the figures here as directional only.
Published estimates diverge sharply because the category boundary is defined differently. Definitions that include pneumatic components and aerospace/military motors land near USD 51 Billion in 2025; analyses restricted to hydraulic pumps alone land between USD 11 Billion and USD 15 Billion for the same year.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 51.16 Billion | 2025 | 2034 | 5.86% | Hydraulic + pneumatic pumps and motors; includes military, aerospace, marine | One published estimate |
| USD 14.82 Billion | 2025 | 2035 | 5.7% | Hydraulic pumps only, all end verticals | A competing analysis |
| USD 11.3 Billion | 2025 | 2033 | 4.2% | Hydraulic pumps, narrower type coverage | A competing analysis |
| USD 57.6 Billion | 2025 | 2035 | 4.9% | All industrial pumps incl. water, HVAC, vacuum | A competing analysis |
Our assessment: the USD 51 Billion figure is the most defensible anchor for this keyword, because it is the only estimate whose stated scope matches the keyword's own segmentation — pumps and motors, hydraulics and pneumatics, military and aerospace included. The tight clustering of 5.7%–5.9% CAGR across two independent hydraulic-focused analyses is the strongest signal in the dataset: forecast velocity is not seriously contested, only the denominator is. This divergence implies buyers comparing quotes across vendors are often comparing different scopes, a recurring source of tender disputes.
Segmentation runs along three axes — pump type, application, and power transmission medium — with hydraulics carrying the dominant share of value and gear pumps the dominant share of units.
| Parent segment | Children |
|---|---|
| By Type | Gear Pump, Piston Pump, Vane Pump, Other |
| By Application | Military, Aerospace, Mining, Off-Highway Vehicles, Marine, Other |
| By Power Transmission | Hydraulics, Pneumatics |
Gear pumps hold the volume base because they are inexpensive, contamination-tolerant and serviceable in the field. Piston pumps, by contrast, are the growth engine: closed-loop transmissions and load-sensing architectures demand higher pressure and better volumetric efficiency, and piston designs are advancing at roughly 6.9% annually in comparable hydraulic-only analyses. Pneumatics retains a defensible niche where speed and cleanliness matter more than force density, but it is losing share in mobile equipment.
Asia Pacific leads with roughly 41% of global revenue, driven by Chinese construction machinery output, Indian agricultural mechanisation and ASEAN industrial build-out; North America and Europe follow on high-specification demand.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.41% |
| North America | 0.24% |
| Europe | 0.21% |
| Middle East & Africa | 0.07% |
| South America | 0.07% |
| Parent region | Countries covered |
|---|---|
| Asia Pacific | China, India, Japan, South Korea, Australia, Rest of Asia Pacific |
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Rest of Europe |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Rest of MEA |
| South America | Brazil, Argentina, Rest of South America |
The regional spread is not uniform in character. Asia Pacific competes on volume and price sensitivity; Europe on efficiency specification and remanufacturing mandates; North America on oil-and-gas workover activity and reshored manufacturing. The Middle East & Africa is the fastest-growing block at roughly 6.6% CAGR as Gulf giga-projects and Saudi mining licences absorb high-pressure equipment. Our analysis suggests the commercial implication is that a single global product platform will underperform — regional duty cycles and emissions rules diverge too far.
Infrastructure renewal and energy-transition capital expenditure are the dominant growth mechanisms; the principal drag is electro-mechanical actuator substitution below roughly 20 kN of force.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Infrastructure renewal and fleet expansion | Growth | Strong | Public works obligations convert directly into excavator, crane and paver hours |
| Energy-transition capex | Growth | Strong | Wind pitch/yaw, electrolyser skids, grid-battery thermal loops need high-cycle hydraulics |
| Factory automation and retrofit | Growth | Moderate | Each automated cell adds one to three servo-hydraulic power units |
| Emissions and efficiency regulation | Growth | Strong | Stage V / Tier 4 Final force smaller engines and load-sensing circuits |
| Electro-mechanical actuator substitution | Restraint | Moderate | Ball-screw and roller-screw drives displace hydraulics in mid-force duty |
| Input-cost volatility | Restraint | Moderate | Steel and casting swings compress OEM and tier-one margins |
| Skilled technician shortage | Restraint | Moderate | Slows aftermarket conversion and rebuild throughput |
The balance favours growth, but with a caveat our analysis emphasises: regulation is simultaneously the strongest driver and the strongest channel for substitution. Emissions rules shrink engine displacement, which rewards variable-displacement hydraulics — yet the same rules push machine designers to evaluate electrified alternatives on total cost of ownership. Vendors that present efficiency in tender documentation, not as a claim, convert this tension into share gains.
A moderately concentrated field: a handful of global fluid-power majors hold significant share through full portfolios and distribution reach, while regional specialists serve custom and price-sensitive niches.
| Company | Portfolio strength | Notable positioning |
|---|---|---|
| Bosch Rexroth | Full hydraulic range, electronic controls | Reference vendor for mobile and industrial hydraulics |
| Parker Hannifin | Pumps, motors, motion systems | Broadest cross-segment coverage and aftermarket network |
| Bucher Hydraulics | Mobile hydraulics, valves, pumps | Strong European OEM penetration |
| Oilgear | High-pressure piston pumps | Process and heavy-industry niches |
| Sulzer | Rotating equipment, specialised pumps | Industrial process and marine exposure |
| Gardner Denver | Blowers, compressors, pneumatic-adjacent | Pneumatic transmission relevance |
| Hydro-Gear | Hydrostatic transmissions | Compact off-highway and turf equipment |
Differentiation rests increasingly on software and service rather than metallurgy. Condition-monitoring subscriptions, remanufacturing programmes and documented fuel savings of 12%–18% on excavator duty cycles are becoming tender requirements in Europe. This implies the moat is shifting from manufacturing scale to installed-base data and authorised service density — an advantage regional players can contest only through partnership.
Selection criteria are dominated by duty-cycle fit, not headline price. Buyers should specify displacement, continuous versus peak pressure, contamination tolerance and control architecture against a measured duty profile; mismatched specification is the largest source of premature failure and warranty dispute in this category.
Procurement risk concentrates in three areas. First, scope ambiguity — quotes may reference hydraulic pumps only while competitors bundle motors and controls, making like-for-like comparison unreliable. Second, switching costs: changing pump architecture typically forces re-validation of the whole circuit, filters and cooling, so operators rarely switch mid-platform. Third, regulatory compliance: Stage V / Tier 4 Final and EU circular-economy procurement rules increasingly require documented efficiency and remanufacturing pathways, and non-compliant designs face tender exclusion rather than price penalty.
Operators should also weight aftermarket factors: rebuild interval depends heavily on fleet utilisation, and above roughly 70% utilisation rebuild cycles shorten measurably. Service coverage density therefore carries real economic value, particularly in mining and marine where unplanned downtime costs dwarf component price.
The balance of evidence favours growth, but not uniform growth. The 5.7%–5.9% CAGR consensus across independent hydraulic analyses is robust; what is contested is where the value accrues. Our position is that the market will grow in revenue while quietly de-rating fixed-displacement hardware, because efficiency has crossed from a sales claim into a specification requirement in Europe and increasingly in North America.
The strongest counter-argument is substitution: below roughly 20 kN, electric actuators are already cheaper to operate and maintain, and each capability improvement removes another hydraulic application. We accept this, but note it addresses the low-force tail, not the high-force core where fluid power's force density remains unchallenged through the forecast window.
What would change this conclusion: a step-change in electric actuator force density beyond 40 kN at comparable cost, or a sustained collapse in construction capex across Asia Pacific. Either would compress the forecast materially. Precise sub-segment forecasting — particularly piston versus gear value migration by country — requires the full dataset beyond this overview.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the fluid-power value chain — alloy and casting suppliers, specialist pump and motor manufacturers, hydraulic system integrators, authorised service networks and global industrial distributors. Decision-maker designations interviewed include VP Sourcing, Heads of Engineering and R&D, Technical Directors, and Commercial Operations Leads responsible for OEM and aftermarket channels.
Cross-validation draws on UN Comtrade and Eurostat bilateral trade flows for pumps and fluid-power components, US ITC tariff and shipment statistics, corporate annual filings and investor presentations, patent databases for variable-displacement and condition-monitoring innovation, and technical standards published by ISO and national fluid-power industry associations.
Top-down allocation from macroeconomic machinery capital-expenditure indices was run simultaneously with bottom-up modelling of manufacturer capacity, unit pricing and end-use consumption by application. Divergence between the two tracks was reconciled against trade flow data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.86% from 2020-2034 |
| Segmentation |
|
The global market was valued at USD 51.16 Billion in 2025 and is projected to reach USD 85.42 Billion by 2034, registering a 5.86% CAGR. The figure covers hydraulic and pneumatic pumps and motors across military, aerospace, mining, off-highway, marine and other applications.
Asia Pacific leads with roughly 41% of global revenue, driven by Chinese construction machinery output and Indian agricultural mechanisation. North America and Europe follow on high-specification industrial and mobile demand, while the Middle East & Africa is the fastest-growing block at about 6.6% CAGR.
Hydraulics dominates the category because it delivers far higher force density and precise control under load, making it standard in off-highway, mining and marine equipment. Pneumatics retains a defensible niche where fast actuation and clean operation matter more than force output.
Estimates differ because category boundaries differ. Analyses including motors, pneumatics and aerospace land near USD 51 Billion; hydraulic-pumps-only studies land between USD 11 Billion and USD 15 Billion. Forecast growth rates cluster far more tightly at 5.7%–5.9%, suggesting only scope is contested.
Electro-mechanical actuator substitution below roughly 20 kN is the clearest structural threat, alongside steel and casting cost volatility and a shortage of skilled fluid-power technicians that slows aftermarket conversion and rebuild throughput in North America and Europe.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the fluid-power value chain — alloy and casting suppliers, specialist pump and motor producers, hydraulic system integrators, authorised remanufacturing and service networks, and global industrial distributors. Decision-maker designations interviewed include VP Sourcing, Heads of Engineering and R&D, Technical Directors, and Commercial Operations Leads accountable for OEM and aftermarket channel performance.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Engineering & R&D Directors | 38% |
| Procurement & Sourcing Leads | 32% |
| Technical & Operations Managers | 20% |
| Commercial & Channel Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Pump & Motor Manufacturers | 40% |
| Component & Casting Suppliers | 25% |
| System Integrators & OEMs | 22% |
| Distributors & Service Networks | 13% |
Cross-validation draws on UN Comtrade and Eurostat bilateral trade flows for pumps and fluid-power components, US ITC tariff and shipment statistics, corporate annual filings and investor presentations, patent databases tracking variable-displacement and condition-monitoring innovation, and technical standards published by ISO and national fluid-power industry associations.
Top-down allocation from macroeconomic machinery capital-expenditure indices ran simultaneously with bottom-up modelling of manufacturer capacity, unit pricing and end-use consumption by application. Divergence between tracks was reconciled against cross-border trade flow data and installed-base attrition models.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
