 Oil Gas Corrosion Protection Market
: $12.5B by 2034
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 198

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Oil Gas Corrosion Protection Market
Sandeep Singh
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 9.960 B |
| 2025 | 10.19 B |
| 2026 | 10.42 B |
| 2027 | 10.66 B |
| 2028 | 10.91 B |
| 2029 | 11.16 B |
| 2030 | 11.42 B |

The oil and gas corrosion protection market covers coatings, paints, corrosion inhibitors, cathodic protection and related services that prevent metal degradation in pipelines, storage tanks, offshore platforms, refineries and drilling equipment. It spans upstream, midstream and downstream operations, onshore and offshore, and is procured to extend asset life, cut downtime and satisfy safety and environmental regulation.
This analysis covers the global market for corrosion protection products and services sold to oil and gas operators across four product types (coatings, paints, corrosion inhibitors, other), two locations (offshore, onshore) and three sectors (upstream, midstream, downstream). This analysis does not cover general industrial protective coatings outside oil and gas, water/wastewater infrastructure protection, or oilfield chemicals outside the corrosion function.
Published estimates diverge by a factor of nearly five, from roughly USD 10–12 Billion to USD 53 Billion, because definitions of "protection" differ sharply — some count only materials, others bundle inspection, monitoring and service contracts. The table below reconciles the most-cited benchmarks.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 9.96 Billion | 2024 | 2034 (12.54B) | 2.3% | Coatings, paints, inhibitors, others; onshore + offshore | One published estimate (Polaris) |
| 11.6 Billion | 2025 | 2034 (16.7B) | 4.02% | Coatings, paints, inhibitors, others; all sectors | One published estimate (IMARC) |
| 11.65 Billion | 2023 | 2030 (11.65B) | 2.4% | Coatings, paints, inhibitors; upstream–downstream | One published estimate (Grand View) |
| 9.78 Billion | 2023 | 2033 (11.98B) | 2.05% | Coatings, paints, inhibitors; upstream + midstream | One published estimate (Spherical) |
| 52.73 Billion | 2024 | 2035 (79.57B) | 3.81% | Broad coatings, cathodic protection, surface modification, services | One published estimate (MRFR) |
Our analysis suggests the USD 9.8–12.5 Billion band is the most defensible material-only reading, and the 2.3–2.4% CAGR is the most likely consensus trajectory. The USD 52.7 Billion figure almost certainly bundles third-party inspection, asset integrity management and service contracts — a valid but different market definition. Buyers should verify which definition they are pricing before committing procurement budgets.
Segments are typically defined by product type, operating location and value-chain sector, with product type and sector doing most of the commercial work. The table below summarizes the non-geographic structure used in this report.
| Parent | Children |
|---|---|
| By Type | Coatings, Paints, Corrosion Inhibitors, Others |
| By Location | Offshore, Onshore |
| By Sector | Upstream, Midstream, Downstream |
| By Corrosion Type | Sweet, Sour, Microbial-Induced, Other |
Coatings are the largest type segment, typically accounting for close to 38–40% of revenue, because they are specified across pipelines, tanks and platforms. Inhibitors are the fastest-accelerating niche but remain smaller. Downstream is the fastest-growing sector as refiners and petrochemical plants confront increasingly corrosive feedstocks and tighter environmental rules.
The Middle East & Africa region leads global revenue share (~33%), followed by North America (~26%) and Asia-Pacific (~18%). Europe and South America split the remainder, with Europe growing fastest on asset-integrity and decarbonization spending.
| Region | Market Share (%) |
|---|---|
| Middle East & Africa | 0.33% |
| North America | 0.26% |
| Asia-Pacific | 0.18% |
| Europe | 0.15% |
| South America | 0.08% |
Our analysis suggests the Middle East's dominance is structural, not cyclical: vast reserves, high-sour service conditions and state-backed capex keep protection demand sticky. North America's second-placed position is more sensitive to shale activity, so a mild US onshore slowdown would disproportionately knock regional growth.
Growth is driven by aging infrastructure, regulatory tightening, offshore exploration and chemical corrosion from sour and microbial service. Restraints are capital discipline, price competition from low-cost suppliers and substitution toward longer-life materials that reduce repurchase frequency.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Aging infrastructure | Driver | High | Extends replacement and maintenance budgets |
| Regulation & safety standards | Driver | High | Mandates inspection and protection spend |
| Offshore exploration | Driver | Medium | Specifies premium coatings and inhibitors |
| Sour / microbial corrosion | Driver | Medium | Requires specialized inhibitors |
| Capex discipline | Restraint | Medium | Defers non-critical coating projects |
| Low-cost substitutes | Restraint | Medium | Pressures prices and shortens replacement cycles |
Our analysis suggests the balance tilts toward growth, but not evenly: premium offshore and downstream sub-segments will outgrow the headline CAGR, while mature onshore midstream protection is likely to grow at or below 2%. That split is the single most important dynamic for vendors planning capacity or portfolio moves.
No single vendor holds more than a low-teens share, and the field splits between diversified coatings majors and specialist corrosion-chemical and service players. The table below summarizes the main competitive archetypes.
| Vendor | Archetype | Notable strength |
|---|---|---|
| SLB | Integrated energy services | Digital + chemical integration |
| 3M | Diversified materials | Coatings and tapes portfolio |
| AkzoNobel | Coatings major | Industrial protective coatings scale |
| PPG | Coatings major | Global specification reach |
| Axalta | Coatings specialist | Pipeline and offshore coatings |
| Hempel | Marine/protective coatings | Offshore track record |
| BASF | Chemical major | Inhibitor chemistry and R&D |
| Cortec | Corrosion specialist | VpCI and inhibitor niche |
Differentiation rests on specification approval, field-service capability and, increasingly, digital monitoring and predictive maintenance. Service bundling — where a coatings supplier also offers inspection and asset-integrity analytics — is the strongest moat, and it is where integrated players such as SLB are pulling ahead of pure coatings vendors.
Selection criteria center on specification approval, field performance under sour or microbial conditions, and total cost of ownership rather than unit price. Operators should stress-test vendor claims against regional service conditions — a coating qualified for North Sea offshore may underperform in high-sour Middle East service.
Procurement risk is concentrated in single-source dependence and specification lock-in. Switching a qualified coating or inhibitor mid-asset-life triggers requalification cost, downtime and warranty exposure, so multi-sourcing by asset class is prudent. Regulatory compliance — particularly around volatile organic compounds, environmental discharge and worker safety — is non-negotiable and is a rising share of total protection spend.
The biggest blind spot for buyers is the gap between headline market CAGR and the specific sub-segment they actually procure. A buyer budgeting on a 2.3% inflation assumption may be under-provisioning if they operate in downstream or offshore, where real cost growth has run materially higher.
The balance of evidence favors a modest but durable growth story: roughly 2.3–2.4% CAGR on a material-only definition, with premium sub-segments growing two to three times faster. Investors should treat the USD 52+ Billion estimates with caution — they measure a service-inclusive market that most buyers do not actually procure as a single line item.
The strongest counter-argument is that decarbonization and asset retirement in mature basins could shrink the installed base faster than new offshore projects replace it, capping growth below consensus. We consider this a real risk in Europe and parts of North America, though it is offset by Middle East and Asia-Pacific capex.
Actionable Strategy
Evidence that would change our conclusion: a sustained rise in upstream capex above USD 600 Billion annually, or regulatory mandates requiring cathodic protection retrofits across aging midstream networks, would push growth materially above the 2.3% consensus.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 2.3% from 2020-2034 |
| Segmentation |
|
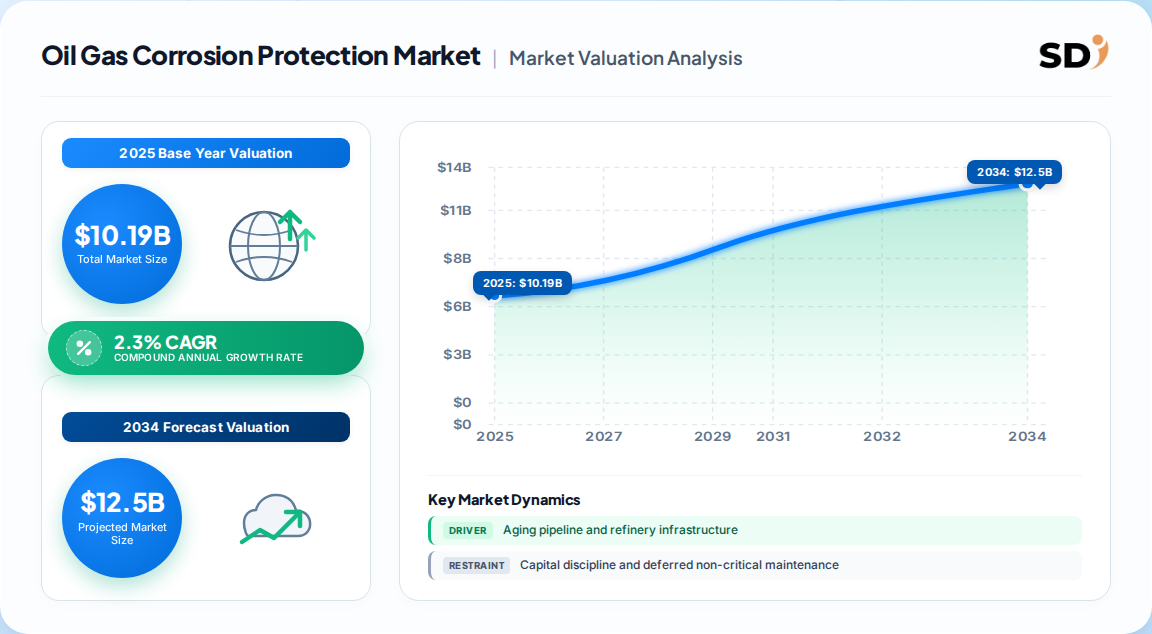
The material-only market is roughly USD 10.2 Billion in 2025, reaching about USD 12.54 Billion by 2034. Broader service-inclusive definitions run far higher, above USD 50 Billion, so buyers must confirm scope before comparing estimates.
Consensus growth is approximately 2.3% CAGR from 2025 to 2034 on a material-only definition. Premium sub-segments such as downstream and offshore protection are growing two to three times faster than the headline rate.
The Middle East & Africa leads with roughly 33% of global revenue, driven by vast reserves and sour service conditions. North America follows at about 26%, with Asia-Pacific emerging as the fastest-growing region.
The main types are coatings, paints, corrosion inhibitors and other solutions such as cathodic protection. Coatings hold the largest share because they are specified across pipelines, tanks and offshore platforms.
Leading companies include SLB, 3M, AkzoNobel, PPG, Axalta, Hempel, BASF and Cortec. No single vendor holds more than a low-teens share, and competition increasingly hinges on service bundling and digital monitoring.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split, with structured interviews conducted across the value chain. We spoke with raw material and specialty chemical suppliers, protective coating formulators, corrosion inhibitor blenders, contract applicators, and global industrial distributors. Within those organizations, we targeted decision-makers including VP-level Sourcing leads, Heads of R&D and Formulation, Technical Directors responsible for specification approval, and Commercial Operations Leads managing regional pricing.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical & Coatings Producers | 45% |
| Formulators & Inhibitor Blenders | 30% |
| Distributors & Service Providers | 25% |
We triangulate primary findings against official multilateral trade data (UN Comtrade, WTO, US ITC, Eurostat) to validate cross-border flows of coating and inhibitor inputs. Corporate annual filings including 10-K and SEC disclosures, investor presentations and patent databases are used to benchmark capacity, pricing and innovation. Technical standards and non-profit industry bodies provide specification and compliance context.
Sizing combines a Top-Down macroeconomic and industry-segment allocation with a Bottom-Up model of manufacturer capacity, product pricing and end-use consumption by sector. Divergences between the two approaches are reconciled through iterative validation rather than averaging.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |