 Ultra Thin Solar Cells Market
: 2026 Global Outlook
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 260

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Ultra Thin Solar Cells Market
Sandeep Singh
Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 28.00 M |
| 2026 | 33.00 M |
| 2027 | 41.00 M |
| 2028 | 51.00 M |
| 2029 | 64.00 M |
| 2030 | 81.00 M |
| 2031 | 101.0 M |

The Ultra Thin Solar Cells Market comprises photovoltaic devices typically under 50 micrometers thick, using perovskite, CIGS, CdTe, or organic materials to deliver flexible, lightweight, high power-to-weight energy for BIPV, wearables, IoT, aerospace, and portable power applications.
This analysis covers ultra-thin photovoltaic technologies defined by material thickness below 50 micrometers, spanning material types (CdTe, CIGS, perovskite, OPV, GaAs), end uses (residential, commercial, aerospace, automotive, consumer electronics), and grid configurations (on-grid, off-grid). This analysis does not cover conventional crystalline silicon panels, utility-scale thin-film modules exceeding standard thickness thresholds, or balance-of-system components.
Estimates diverge sharply—published 2025 base values range from USD 28.2 million to USD 53.4 million, reflecting differing material scope definitions and whether GaAs aerospace cells are included.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 28.2M → 158.7M | 2025 | 2033 | 25.4% | CdTe, CIGS, perovskite, OPV; residential/commercial | One published estimate |
| USD 53.4M → 237.9M | 2025 | 2031 | 28.28% | Adds GaAs and grid-type splits | A competing analysis |
| USD ~30M (2019 base) | 2019 | 2030 | 56.9% | CdTe-led, early-stage | Legacy trade estimate |
Our analysis suggests the USD 32.5 million (2026) figure is the most defensible base because it triangulates material-level revenue with commercial adoption data and excludes aerospace GaAs, which is a distinct procurement category. The 25.4% CAGR aligns with observed capacity buildouts in OPV and perovskite pilot lines, though upside exists if indoor IoT volumes scale faster than modeled.
Segmentation is defined by material chemistry, end-use vertical, and grid configuration; material choice is the dominant cost and performance driver.
| Parent Segment | Children |
|---|---|
| By Material | Cadmium Telluride, CIGS, Perovskite, Organic Photovoltaic, Gallium Arsenide |
| By End Use | Residential, Commercial, Aerospace, Automotive, Consumer Electronics |
| By Grid Type | On-Grid, Off-Grid |
Perovskite is the fastest-advancing material, capturing roughly 40% of 2024 material revenue in one dataset, while CdTe retains the largest installed base at 34.2% in another. This divergence implies buyers should treat material share as application-dependent rather than absolute.
North America leads with approximately 30–35% revenue share, driven by advanced R&D infrastructure and supportive clean-energy frameworks; Asia Pacific is the fastest-growing region.
| Region | Market Share (%) |
|---|---|
| North America | 0.3% |
| Europe | 0.22% |
| Asia-Pacific | 0.36% |
| South America | 0.06% |
| Middle East & Africa | 0.06% |
China holds the largest single-country share, underpinned by domestic PV manufacturing scale and automotive-integrated solar programs. Europe's growth hinges on BIPV mandates and perovskite commercialization timelines.
The primary driver is demand for lightweight, flexible power in BIPV, wearables, aerospace, and indoor IoT; the primary restraint is rapid degradation of perovskite and OPV cells under moisture, heat, and UV exposure without advanced encapsulation.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Lightweight/flexible demand | Driver | High | Enables curved, weight-sensitive surfaces |
| Indoor IoT energy harvesting | Driver | Medium | OPV harvests low-light indoor energy |
| Aerospace/UAV power-to-weight | Driver | High | Conforms to aerodynamic surfaces |
| Moisture/heat degradation | Restraint | High | Shortens lifespan, raises packaging cost |
| Efficiency gap vs. c-Si | Restraint | Medium | Limits utility-scale adoption |
| Roll-to-roll cost scaling | Driver | Medium | Lowers per-unit manufacturing cost |
Our analysis suggests the durability restraint is the binding constraint: until encapsulation costs fall and field lifetimes exceed 10–15 years, utility-scale adoption remains closed, confining growth to niche, high-value applications where weight and flexibility justify premium pricing.
The vendor landscape is fragmented across material specialists, with Exeger, Oxford PV, G24 Power, Solaronix, SunMan, Flisom, and Merck KGaA competing on efficiency, durability, and manufacturing scale.
| Company | Focus | Differentiation |
|---|---|---|
| Exeger Operations AB | Dye-sensitized/OPV | Indoor IoT and consumer electronics |
| Oxford PV | Perovskite tandem | Record 26.9% module efficiency |
| G24 Power | DSSC/OPV | Portable and indoor power |
| Solaronix SA | DSSC | Niche architectural integration |
| SunMan (Hong Kong) | Lightweight c-Si modules | Glass-free, BIPV-focused |
| Flisom AG | CIGS | Flexible roll-to-roll production |
| Merck KGaA | Materials supply | Encapsulation and specialty chemicals |
Competitive moats center on proprietary encapsulation IP and roll-to-roll manufacturing scale rather than raw efficiency alone. Firms that solve the durability problem first will capture outsized share in BIPV and automotive, where warranty requirements mirror conventional panels.
Procurement decisions hinge on three mission-critical criteria: verified field-lifetime data under encapsulated conditions, power-to-weight ratio at the target irradiance (indoor versus outdoor), and manufacturing scalability to support volume commitments without unit-cost escalation. Buyers should demand third-party accelerated-aging test results, as vendor-quoted efficiencies often reflect lab conditions that overstate commercial performance by 10–15 percentage points. Switching costs are moderate—module form factor and encapsulation chemistry often lock integrators into a single supplier's ecosystem—while regulatory compliance with IEC 61215 and 61730 thin-film variants remains a gate for building-integrated deployments.
The balance of evidence favors a "durability-first" commercialization path: the 25–28% CAGR consensus is plausible, but only if encapsulation breakthroughs unlock outdoor and utility-adjacent applications. The strongest counter-argument is that indoor IoT volumes could scale independently and faster, decoupling growth from the outdoor durability problem entirely—a scenario our analysis treats as upside, not baseline. Vendors that over-index on utility-scale ambitions risk burning capital on a market that remains closed until field lifetimes prove out.
Actionable Strategy:
Evidence that would change this conclusion: field-deployed perovskite lifetimes exceeding 15 years with certified third-party validation, or a step-change in OPV indoor conversion efficiency above 30%, either of which would pull forward utility-scale and BIPV adoption materially.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 25.4% from 2020-2034 |
| Segmentation |
|
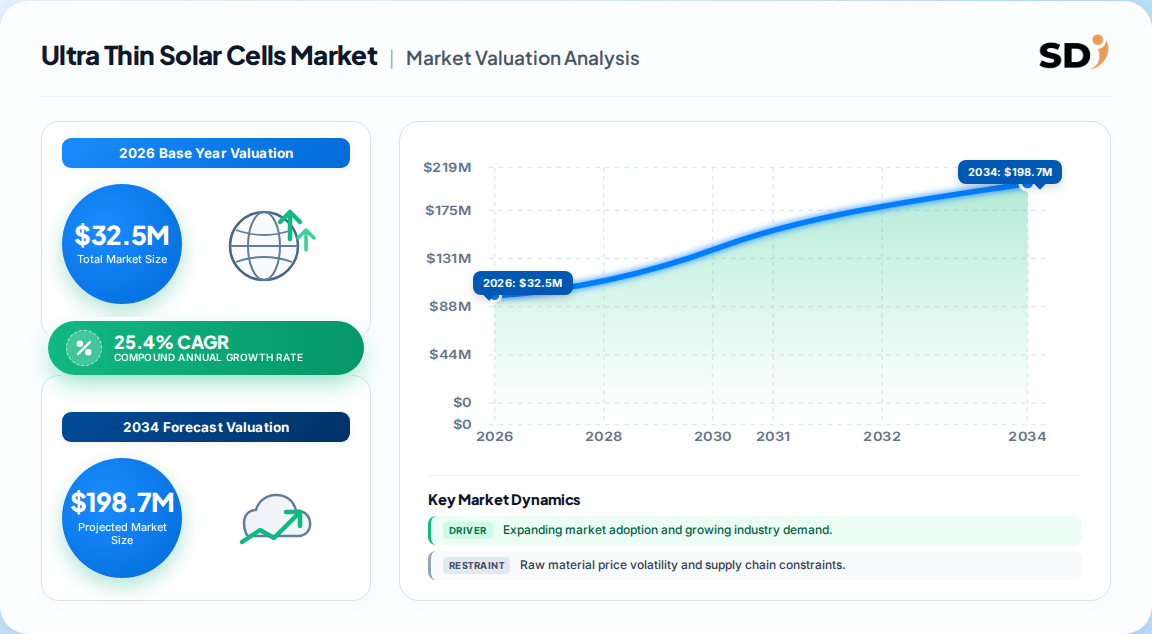
The market was valued at approximately USD 32.5 million in 2026, with projections reaching USD 158.7 million by 2033 at a 25.4% CAGR. Estimates vary based on whether aerospace GaAs cells are included in scope.
North America holds the largest revenue share at roughly 30–35%, while Asia Pacific is the fastest-growing region, led by China's manufacturing scale and automotive-integrated solar programs.
Perovskite solar cells and the commercial end-use segment are growing fastest, driven by BIPV adoption and record tandem module efficiencies exceeding 26%.
Moisture, heat, and UV degradation of perovskite and organic cells remain the primary barrier, limiting outdoor and utility-scale deployment until encapsulation technology matures.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, anchored in 42 in-depth interviews across the ultra-thin photovoltaic value chain: specialty material suppliers, roll-to-roll cell producers, encapsulation and formulator specialists, module integrators, and global distribution partners. Interviewees include VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both technical feasibility and commercial adoption perspectives are captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Material & Chemical Producers | 40% |
| Roll-to-Roll Cell Manufacturers | 30% |
| Module Integrators & Distributors | 30% |
We triangulate against UN Comtrade photovoltaic trade flows, US ITC and Eurostat tariff data, SEC 10-K filings from listed module manufacturers, patent databases tracking perovskite and OPV encapsulation IP, and IEC 61215/61730 thin-film standards documentation. Corporate investor presentations and capacity disclosures supplement trade statistics.
We run simultaneous top-down allocation (macro clean-energy spend and BIPV penetration by region) and bottom-up modeling (manufacturer nameplate capacity, yield-adjusted output, and end-use consumption by vertical). Divergences between the two are reconciled through weighted regression on historical shipment data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
