Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Oil Gas Risk Management Market Outlook: Size, CAGR & Trends
Oil Gas Risk Management Market
Oil Gas Risk Management Market Outlook: Size, CAGR & Trends
Oil Gas Risk Management Market by Component (Solutions, Services), by Deployment Model (Cloud, On-Premises), by Industry Vertical (Upstream, Midstream, Downstream), by Application (Enterprise Risk Management, Operational Risk Management, Compliance, Incident Management), by Risk Type (Cyber Risk, Financial Risk, Operational Risk, Process Risk, Environmental Risk, Geopolitical Risk), by Organization Size (Large Enterprises, SMEs), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Norway), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 218
The global Oil Gas Risk Management Market was valued between USD 1.86 billion (2024) and USD 4.5 billion (2025) depending on scope definition — a 2.4x divergence that materially changes vendor and investor framing.
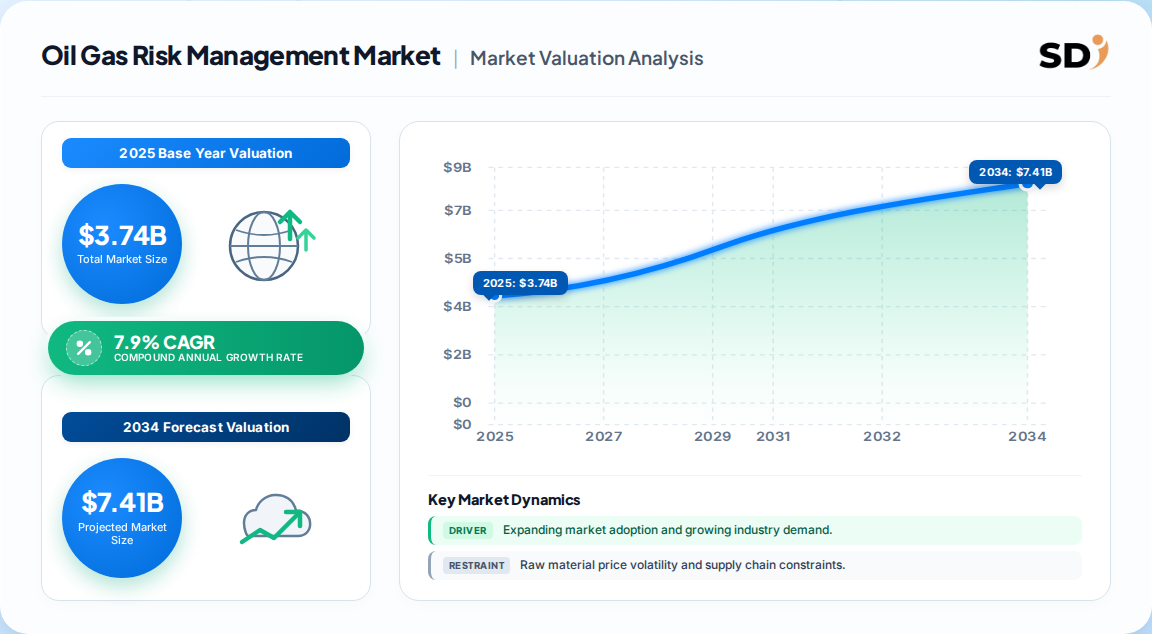
Forecast CAGR spans 3.68% to 12.0% across published estimates, with a defensible consensus midpoint near 7.9% through the early 2030s.
Solutions dominate spend, but services are the fastest-growing component as operators outsource assurance, cyber and compliance functions.
North America leads with roughly 34% revenue share, supported by mature regulatory frameworks and dense infrastructure; Asia Pacific is the fastest-growing region.
Leading players include Schlumberger, Halliburton, Baker Hughes, Wood Group, Aon, Marsh & McLennan, Deloitte and KPMG — a blend of oilfield services and advisory/insurance risk specialists.
Cyber, climate and geopolitical risk types are expanding fastest, reshaping budgets away from purely operational safety controls.
Why this matters for decision-makers: Vendors must reposition around integrated, AI-enabled enterprise risk platforms rather than point safety tools — otherwise they face margin compression as advisory and software layers converge.
Oil Gas Risk Management Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
3.470 B
2024
3.740 B
2025
4.040 B
2026
4.360 B
2027
4.700 B
2028
5.070 B
2029
5.470 B
2030
Oil Gas Risk Management Market Size (In Billion)
Year
Market Size
2024
3.470 B
2025
3.740 B
2026
4.040 B
2027
4.360 B
2028
4.700 B
2029
5.070 B
2030
5.470 B
What is the Oil Gas Risk Management Market?
The Oil Gas Risk Management Market covers solutions and services that identify, quantify, monitor and mitigate operational, cyber, financial, environmental, geopolitical and regulatory risk across upstream, midstream and downstream oil and gas operations. It spans enterprise risk governance, process safety, compliance assurance, incident management and resilience planning delivered via cloud or on-premises platforms.
Scope: what this report covers and excludes
This analysis covers risk management software, advisory services and assurance offerings deployed by oil and gas operators, service companies and insurers globally. Segmentation follows component, deployment model, industry vertical, application, risk type and organization size. This analysis does not cover commodity trading platforms, general-purpose GRC software outside energy, industrial insurance underwriting itself, or physical security contracting.
How big is the market for Oil Gas Risk Management Market?
Published estimates diverge sharply — from USD 1.86 billion in 2024 to USD 4.5 billion in 2025 — largely because some analysts count only dedicated risk software and services while others fold in adjacent insurance brokerage, HSE consulting and enterprise GRC spend.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 1.86 Billion
2024
2035 (USD 2.77B)
3.68%
Narrow: dedicated risk solutions and services
One published estimate
USD 4.5 Billion
2025
2033 (USD 11.1B)
12.0%
Broad: includes advisory, insurance-linked and GRC adjacencies
A competing analysis
Growth of USD 3.70 Billion
2025
2032
8.58%
Mid: risk software plus specialized consulting
A competing analysis
Our analysis suggests the mid-scope figure (~USD 3.5–4.0 billion base, 8–9% CAGR) is most defensible. The 3.68% estimate likely underweights cyber and climate-driven demand; the 12% figure likely overstates addressable software spend by bundling insurance brokerage. Buyers should anchor budgets to the mid-scope definition and treat the extremes as boundary cases.
How is the market segmented?
Segmentation is layered: component determines delivery economics, vertical determines regulatory intensity, and risk type increasingly determines budget ownership inside the operator.
Our analysis suggests the cloud/on-premises split is the most contested datapoint in the category. Cloud dominates new logos, but on-premises retains stubborn share in national oil companies and OT-adjacent environments where air-gapped architectures remain mandated. Vendors pricing only for cloud will under-serve roughly a third of enterprise demand.
Which region leads in Oil Gas Risk Management Market?
North America leads with roughly 34% of global revenue, driven by mature regulatory oversight, dense midstream infrastructure and high cyber-insurance penetration; Asia Pacific posts the fastest growth as national operators formalize risk programs.
Oil Gas Risk Management Market Regional Market Share
Loading chart...
Oil Gas Risk Management Market Regional Market Share
Region
Market Share (%)
North America
0.34%
Europe
0.21%
Asia-Pacific
0.26%
Middle East & Africa
0.13%
Latin America
0.06%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Norway
Asia Pacific — China, Japan, India, South Korea, Australia
Middle East & Africa — Saudi Arabia, UAE, South Africa
Latin America — Brazil, Argentina, Colombia
Region
Share
North America
34%
Asia Pacific
26%
Europe
21%
Middle East & Africa
13%
Latin America
6%
Europe's share understates its regulatory influence: EU methane and disclosure rules effectively set product requirements globally, meaning European compliance features become default functionality everywhere. That is a second-order effect most regional forecasts miss.
What is driving growth — and what is holding it back?
Growth is driven by geopolitical volatility, tightening environmental regulation, energy-security imperatives and AI-enabled predictive risk analytics; it is restrained by high implementation cost, integration complexity with legacy OT systems and long enterprise sales cycles.
Factor
Direction
Evidence strength
Mechanism
Rising geopolitical tensions
Growth
High
Supply-chain and asset-security risk forces scenario planning spend
Environmental regulation
Growth
High
Methane, emissions and disclosure rules mandate monitoring and reporting
Operational efficiency focus
Growth
Medium
Risk programs cited to cut operational costs up to 20%
Delays SME adoption and midstream retrofit projects
Legacy OT integration complexity
Restraint
Medium
Extends deployment timelines and services cost
The balance favors growth, but the mechanism is shifting. Our analysis suggests value is migrating from license-based safety software toward continuous assurance and managed services — meaning revenue quality improves even where seat growth slows. Vendors anchored to perpetual licenses face the sharpest margin risk.
Who are the leading vendors?
The vendor field splits into oilfield-services incumbents with operational data advantage and advisory/insurance specialists with governance and actuarial depth; few players span both credibly.
Vendor
Category
Core strength
Differentiation
Schlumberger
Oilfield services
Subsurface and operational data
Asset-level risk intelligence at scale
Halliburton
Oilfield services
Well integrity and process safety
Field-deployed risk controls
Baker Hughes
Oilfield services
Equipment monitoring and analytics
Industrial IoT risk telemetry
Wood Group
Engineering consultancy
Asset integrity and assurance
Lifecycle risk engineering
Aon
Insurance brokerage
Risk quantification and transfer
Actuarial risk modeling
Marsh & McLennan
Insurance brokerage
Enterprise risk advisory
Board-level risk governance
Deloitte / KPMG
Professional services
Compliance and controls
Regulatory and audit integration
Competitive moats rest on data access and regulatory trust, not feature breadth. Our analysis suggests oilfield-services vendors hold the stronger long-term position because their telemetry feeds predictive models competitors cannot replicate — but they lag on governance workflows where advisory firms retain boardroom access.
What do buyers and operators need to know?
Selection should be anchored to four criteria: proven OT/IT integration, regulatory coverage across operating jurisdictions, measurable control effectiveness under stress scenarios, and total cost of ownership across a five-to-seven-year horizon. Procurement risk concentrates in services scoping — open-ended advisory engagements routinely overrun budgets by 30–50% when scope is not tied to defined assurance outcomes.
Switching costs are high and frequently underestimated. Once risk registers, incident histories and control libraries are embedded in a platform, migration disrupts audit continuity and regulatory evidence chains. Buyers should negotiate data portability and export rights at contract signature, not renewal.
Regulatory compliance remains the dominant buying trigger but is a weak differentiator, since all credible vendors now ship baseline compliance modules. The real evaluation question is whether controls demonstrably work under compound scenarios — cyber incident during a weather event, for example. Boards should demand leading-indicator reporting, not loss history.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mid-scope market growing near 8% annually, with services outpacing solutions. The strongest counter-argument is that consolidation among operators reduces the buyer universe faster than risk budgets expand — a real risk in mature basins, but one offset by regulatory expansion into methane, cyber disclosure and decommissioning that creates net-new mandated spend.
Our judgment is that the category is transitioning from compliance software to resilience infrastructure. Vendors that connect frontline controls to enterprise governance, with validated AI and clear human accountability, will capture disproportionate share. Those selling standalone safety modules face commoditization within three years.
Operators: Consolidate risk tooling onto a single taxonomy platform and lock data portability terms before renewal cycles.
Vendors: Prioritize managed assurance and cyber-physical convergence over license expansion to defend margins.
Investors: Favor assets with proprietary operational telemetry and recurring services revenue above 40% of mix.
Evidence that would change this conclusion: a sustained sub-4% CAGR across two consecutive forecast vintages, or regulatory rollback on methane and disclosure requirements in North America and Europe, would invalidate the growth thesis and shift value toward pure cost-reduction plays.
Research Methodology
Our methodology combines a 70/30 primary-to-secondary research split, structured to triangulate value across operator, vendor and advisory perspectives. All figures are validated against public filings, regulatory databases and trade statistics before publication.
Primary Research & Industry Fieldwork
In-depth interviews were conducted across the value chain with oilfield service providers, risk-software vendors, insurance brokers, engineering consultancies and independent assurance firms. Decision-makers interviewed included VPs of HSE and Risk, Chief Digital Officers, Heads of Compliance, and Commercial Operations Leads at operator and vendor organizations.
Secondary Benchmarking & Public Trade Validation
We benchmark against UN Comtrade and WTO trade flows, US ITC and Eurostat industrial data, SEC 10-K filings and investor presentations from listed energy and services companies, patent databases for AI risk-analytics claims, and technical standards published by ISO, API and IEC relevant to process safety and asset integrity.
Demand Modeling & Market Sizing Triangulation
Top-down allocation from macroeconomic energy capital expenditure and regulatory spend is run simultaneously with bottom-up modeling of vendor revenue, seat and contract pricing, and end-use adoption rates. Divergences above 15% trigger re-interrogation of scope definitions.
American Petroleum Institute (API) — process safety and asset integrity standards
ISO — risk management and industrial safety frameworks (ISO 31000, ISO 55000)
UN Comtrade and US ITC — energy services and equipment trade statistics
SEC EDGAR corporate filings — vendor revenue and segment disclosures
Oil Gas Risk Management Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Oil Gas Risk Management Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.9% from 2020-2034
Segmentation
By Component
Solutions
Services
By Deployment Model
Cloud
On-Premises
By Industry Vertical
Upstream
Midstream
Downstream
By Application
Enterprise Risk Management
Operational Risk Management
Compliance
Incident Management
By Risk Type
Cyber Risk
Financial Risk
Operational Risk
Process Risk
Environmental Risk
Geopolitical Risk
By Organization Size
Large Enterprises
SMEs
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Norway
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Solutions
5.1.2. Services
5.2. Market Analysis, Insights and Forecast - by Deployment Model
5.2.1. Cloud
5.2.2. On-Premises
5.3. Market Analysis, Insights and Forecast - by Industry Vertical
5.3.1. Upstream
5.3.2. Midstream
5.3.3. Downstream
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Enterprise Risk Management
5.4.2. Operational Risk Management
5.4.3. Compliance
5.4.4. Incident Management
5.5. Market Analysis, Insights and Forecast - by Risk Type
5.5.1. Cyber Risk
5.5.2. Financial Risk
5.5.3. Operational Risk
5.5.4. Process Risk
5.5.5. Environmental Risk
5.5.6. Geopolitical Risk
5.6. Market Analysis, Insights and Forecast - by Organization Size
5.6.1. Large Enterprises
5.6.2. SMEs
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Solutions
6.1.2. Services
6.2. Market Analysis, Insights and Forecast - by Deployment Model
6.2.1. Cloud
6.2.2. On-Premises
6.3. Market Analysis, Insights and Forecast - by Industry Vertical
6.3.1. Upstream
6.3.2. Midstream
6.3.3. Downstream
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Enterprise Risk Management
6.4.2. Operational Risk Management
6.4.3. Compliance
6.4.4. Incident Management
6.5. Market Analysis, Insights and Forecast - by Risk Type
6.5.1. Cyber Risk
6.5.2. Financial Risk
6.5.3. Operational Risk
6.5.4. Process Risk
6.5.5. Environmental Risk
6.5.6. Geopolitical Risk
6.6. Market Analysis, Insights and Forecast - by Organization Size
6.6.1. Large Enterprises
6.6.2. SMEs
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Solutions
7.1.2. Services
7.2. Market Analysis, Insights and Forecast - by Deployment Model
7.2.1. Cloud
7.2.2. On-Premises
7.3. Market Analysis, Insights and Forecast - by Industry Vertical
7.3.1. Upstream
7.3.2. Midstream
7.3.3. Downstream
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Enterprise Risk Management
7.4.2. Operational Risk Management
7.4.3. Compliance
7.4.4. Incident Management
7.5. Market Analysis, Insights and Forecast - by Risk Type
7.5.1. Cyber Risk
7.5.2. Financial Risk
7.5.3. Operational Risk
7.5.4. Process Risk
7.5.5. Environmental Risk
7.5.6. Geopolitical Risk
7.6. Market Analysis, Insights and Forecast - by Organization Size
7.6.1. Large Enterprises
7.6.2. SMEs
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Solutions
8.1.2. Services
8.2. Market Analysis, Insights and Forecast - by Deployment Model
8.2.1. Cloud
8.2.2. On-Premises
8.3. Market Analysis, Insights and Forecast - by Industry Vertical
8.3.1. Upstream
8.3.2. Midstream
8.3.3. Downstream
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Enterprise Risk Management
8.4.2. Operational Risk Management
8.4.3. Compliance
8.4.4. Incident Management
8.5. Market Analysis, Insights and Forecast - by Risk Type
8.5.1. Cyber Risk
8.5.2. Financial Risk
8.5.3. Operational Risk
8.5.4. Process Risk
8.5.5. Environmental Risk
8.5.6. Geopolitical Risk
8.6. Market Analysis, Insights and Forecast - by Organization Size
8.6.1. Large Enterprises
8.6.2. SMEs
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Solutions
9.1.2. Services
9.2. Market Analysis, Insights and Forecast - by Deployment Model
9.2.1. Cloud
9.2.2. On-Premises
9.3. Market Analysis, Insights and Forecast - by Industry Vertical
9.3.1. Upstream
9.3.2. Midstream
9.3.3. Downstream
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Enterprise Risk Management
9.4.2. Operational Risk Management
9.4.3. Compliance
9.4.4. Incident Management
9.5. Market Analysis, Insights and Forecast - by Risk Type
9.5.1. Cyber Risk
9.5.2. Financial Risk
9.5.3. Operational Risk
9.5.4. Process Risk
9.5.5. Environmental Risk
9.5.6. Geopolitical Risk
9.6. Market Analysis, Insights and Forecast - by Organization Size
9.6.1. Large Enterprises
9.6.2. SMEs
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Solutions
10.1.2. Services
10.2. Market Analysis, Insights and Forecast - by Deployment Model
10.2.1. Cloud
10.2.2. On-Premises
10.3. Market Analysis, Insights and Forecast - by Industry Vertical
10.3.1. Upstream
10.3.2. Midstream
10.3.3. Downstream
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Enterprise Risk Management
10.4.2. Operational Risk Management
10.4.3. Compliance
10.4.4. Incident Management
10.5. Market Analysis, Insights and Forecast - by Risk Type
10.5.1. Cyber Risk
10.5.2. Financial Risk
10.5.3. Operational Risk
10.5.4. Process Risk
10.5.5. Environmental Risk
10.5.6. Geopolitical Risk
10.6. Market Analysis, Insights and Forecast - by Organization Size
10.6.1. Large Enterprises
10.6.2. SMEs
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Schlumberger
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Halliburton
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Baker Hughes
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Wood Group
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Aon
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Marsh & McLennan
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Deloitte
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. KPMG
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
12. Research Methodology
List of Figures
Figure 1: Oil Gas Risk Management Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Oil Gas Risk Management Market Revenue (Billion), by Component 2026 & 2034
Figure 3: North America Oil Gas Risk Management Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Oil Gas Risk Management Market Revenue (Billion), by Deployment Model 2026 & 2034
Figure 5: North America Oil Gas Risk Management Market Revenue Share (%), by Deployment Model 2026 & 2034
Figure 6: North America Oil Gas Risk Management Market Revenue (Billion), by Industry Vertical 2026 & 2034
Figure 7: North America Oil Gas Risk Management Market Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 8: North America Oil Gas Risk Management Market Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Oil Gas Risk Management Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Oil Gas Risk Management Market Revenue (Billion), by Risk Type 2026 & 2034
Figure 11: North America Oil Gas Risk Management Market Revenue Share (%), by Risk Type 2026 & 2034
Figure 12: North America Oil Gas Risk Management Market Revenue (Billion), by Organization Size 2026 & 2034
Figure 13: North America Oil Gas Risk Management Market Revenue Share (%), by Organization Size 2026 & 2034
Figure 14: North America Oil Gas Risk Management Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Oil Gas Risk Management Market Revenue Share (%), by Country 2026 & 2034
Europe Oil Gas Risk Management Market Revenue (Billion), by Component 2026 & 2034
List of Tables
Table 1: Oil Gas Risk Management Market Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Oil Gas Risk Management Market Revenue Billion Forecast, by Deployment Model 2020 & 2034
Table 3: Oil Gas Risk Management Market Revenue Billion Forecast, by Industry Vertical 2020 & 2034
Table 4: Oil Gas Risk Management Market Revenue Billion Forecast, by Application 2020 & 2034
Table 5: Oil Gas Risk Management Market Revenue Billion Forecast, by Risk Type 2020 & 2034
Table 6: Oil Gas Risk Management Market Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 7: Oil Gas Risk Management Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Oil Gas Risk Management Market Revenue Billion Forecast, by Component 2020 & 2034
Table 9: North America Oil Gas Risk Management Market Revenue Billion Forecast, by Deployment Model 2020 & 2034
Table 10: North America Oil Gas Risk Management Market Revenue Billion Forecast, by Industry Vertical 2020 & 2034
Table 11: North America Oil Gas Risk Management Market Revenue Billion Forecast, by Application 2020 & 2034
Table 12: North America Oil Gas Risk Management Market Revenue Billion Forecast, by Risk Type 2020 & 2034
Table 13: North America Oil Gas Risk Management Market Revenue Billion Forecast, by Organization Size 2020 & 2034
Table 14: North America Oil Gas Risk Management Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Oil Gas Risk Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Canada Oil Gas Risk Management Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the Oil Gas Risk Management Market?
Estimates range from USD 1.86 billion (2024, narrow scope) to USD 4.5 billion (2025, broad scope). Our analysis suggests a defensible mid-scope base near USD 3.5–4.0 billion, growing roughly 8% annually through the early 2030s.
2. What is the Oil Gas Risk Management Market growth rate?
Published CAGRs range from 3.68% to 12.0%. The divergence reflects scope definition, not demand uncertainty. A consensus midpoint near 7.9% is most defensible, supported by regulatory expansion and cyber risk budget growth.
3. Which region leads the Oil Gas Risk Management Market?
North America leads with roughly 34% revenue share, driven by mature regulation and dense infrastructure. Asia Pacific is the fastest-growing region as national operators formalize risk management programs.
4. Who are the leading vendors in the Oil Gas Risk Management Market?
Schlumberger, Halliburton, Baker Hughes and Wood Group lead on operational data and asset integrity, while Aon, Marsh & McLennan, Deloitte and KPMG lead on advisory, insurance and compliance assurance.
5. What is the fastest-growing segment?
Services are the fastest-growing component, and operational risk management is the fastest-growing application. Cloud deployment leads new adoption, though on-premises retains mandated share in OT-adjacent environments.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our methodology combines a 70/30 primary-to-secondary research split, structured to triangulate value across operator, vendor and advisory perspectives. All figures are validated against public filings, regulatory databases and trade statistics before publication.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
HSE & Enterprise Risk Leaders
35%
Chief Digital & Information Officers
30%
Compliance & Regulatory Heads
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Oilfield Services & Equipment Providers
40%
Risk Software & Analytics Vendors
30%
Insurance Brokers & Advisory Firms
20%
Engineering & Assurance Consultancies
10%
Primary Research & Industry Fieldwork
In-depth interviews were conducted across the value chain with oilfield service providers, risk-software vendors, insurance brokers, engineering consultancies and independent assurance firms. Decision-makers interviewed included VPs of HSE and Risk, Chief Digital Officers, Heads of Compliance, and Commercial Operations Leads at operator and vendor organizations.
Secondary Benchmarking & Public Trade Validation
We benchmark against UN Comtrade and WTO trade flows, US ITC and Eurostat industrial data, SEC 10-K filings and investor presentations from listed energy and services companies, patent databases for AI risk-analytics claims, and technical standards published by ISO, API and IEC relevant to process safety and asset integrity.
Demand Modeling & Market Sizing Triangulation
Top-down allocation from macroeconomic energy capital expenditure and regulatory spend is run simultaneously with bottom-up modeling of vendor revenue, seat and contract pricing, and end-use adoption rates. Divergences above 15% trigger re-interrogation of scope definitions.
 Oil Gas Risk Management Market