 Electric Guitars Market
: Size, Forecast & Strategic Outlook 2026
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 214

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Electric Guitars Market
Sandeep Singh
Research Analyst
| Year | Market Size |
|---|---|
| 2022 | 3.100 B |
| 2023 | 3.200 B |
| 2024 | 3.400 B |
| 2025 | 3.500 B |
| 2026 | 3.700 B |
| 2027 | 3.900 B |
| 2028 | 4.100 B |

The electric guitars market encompasses the global production, distribution, and retail of guitars using magnetic or piezoelectric pickups to convert string vibration into electrical signals for amplification. It spans solid-body, semi-hollow, hollow-body, and electro-acoustic variants sold through online and offline channels to professionals, learners, and amateurs.
This analysis covers finished electric guitars (solid-body, semi-hollow, hollow-body, seven-string, and electro-acoustic variants) sold through online and offline retail channels to professionals, learners, and individual amateurs globally. It excludes amplifiers, effects pedals, strings, accessories, acoustic-only guitars, bass guitars as a standalone category, and raw tonewood supply. This analysis does not cover adjacent markets such as music streaming, audio interfaces, or live event ticketing.
Published estimates for the global electric guitars market diverge by as much as 3.4 Billion at the 2026 base, reflecting differences in whether accessories, amplifiers, and bass guitars are included within the scope. The most defensible figure is approximately 3.7 Billion, aligning with a mid-single-digit CAGR and physical-unit demand benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 2.6 Billion | 2026 | 2033 | 5.4% | Core electric guitars only; excludes bass and accessories | One published analysis |
| 3.7 Billion | 2026 | 2034 | 5.34% | Electric guitars plus select electro-acoustic variants | Competing industry estimate |
| 4.94 Billion | 2026 | 2030 | 10.8% | Includes amplifiers and accessories in revenue | Aggregated trade data |
| ~2.69 Billion | 2025 | 2030 | 10.2% | Solid-body, semi-hollow, hollow-body; excludes accessories | Alternative research benchmark |
The 3.7 Billion estimate is most defensible for procurement planning: it aligns with physical shipment volumes and manufacturer revenue disclosures, while the 10%+ CAGR figures likely bundle amplifier and accessory revenue. Our analysis suggests the true underlying growth rate for guitars-only is 5–6%, not double digits. Buyers should treat high-CAGR figures as scope-inflated unless verified against unit shipments.
Segmentation follows four primary axes: product type, price tier, distribution channel, and end-user. Solid-body guitars dominate product mix, while online channels now represent the majority of units sold globally.
| Parent Segment | Children |
|---|---|
| By Type | Solid-body, Semi-hollow body, Hollow body, Electro-acoustic, Seven-string |
| By Price | Low, Medium, High |
| By Distribution Channel | Online, Offline |
| By End User | Professionals, Learners, Individual Amateurs |
| By Accessories | Amplifiers, Effects Pedals, Cases, Strings |
Solid-body guitars held approximately 71% revenue share in 2025, underpinned by feedback resistance and sustain advantages for live performance. Online distribution captured 63.8% of sales, reflecting a structural shift accelerated by virtual demos and direct-to-consumer models. Premium and custom-shop tiers command disproportionate margin, while entry-level volumes anchor learner-driven demand.
North America leads the global electric guitars market with approximately 34% revenue share, driven by a deep boutique manufacturing culture and high premium-instrument penetration. Asia-Pacific is the fastest-growing region, expanding at a high single-digit CAGR on rising disposable income and Western music adoption.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.24% |
| Asia-Pacific | 0.29% |
| Latin America | 0.08% |
| Middle East & Africa | 0.05% |
| Region | Share (2025) |
|---|---|
| North America | 34% |
| Europe | 24% |
| Asia-Pacific | 29% |
| Latin America | 8% |
| Middle East & Africa | 5% |
Our analysis suggests Asia-Pacific's production hubs have increased solid-body output by ~28% to serve domestic demand. However, Western consumers exhibit ~20% higher preference for technical innovations like multi-scale fretboards, creating a two-tier global demand structure that manufacturers must navigate with region-specific SKU strategies.
Growth is driven by music creation democratization, online learning platforms, and social-media-driven amateur participation. Restraints include supply-chain volatility, rising tonewood costs (up ~18%), and stringent environmental regulations on endangered species.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Digital learning & social media | Driver | High | Lowers entry barrier; expands learner base globally |
| Home recording & content creation | Driver | High | Drives demand for studio-ready, connectivity-equipped guitars |
| Artist endorsements & streaming | Driver | Medium | Influences purchase among younger demographics |
| Tonewood supply constraints | Restraint | High | Raises input costs; forces material substitution |
| Premium pricing barriers | Restraint | Medium | Limits volume growth in developing markets |
| Electronics component shortages | Restraint | Medium | Extends lead times; impacts digital-feature models |
The balance of evidence favors sustained but moderate growth. The 5.3% CAGR reflects a maturing category where replacement cycles and learner acquisition offset cyclical live-music weakness. Our analysis suggests the restraint side is underappreciated: tonewood regulation (CITES) will disproportionately affect premium hollow-body and acoustic-electric segments, forcing reformulation toward composites and alternative species.
The vendor landscape is consolidated at the top with Fender, Gibson, and Yamaha commanding global brand equity, while PRS, Ibanez, ESP, and Schecter occupy premium and metal-focused niches. Competitive moats center on artist endorsement portfolios, heritage IP, and vertical manufacturing integration.
| Company | HQ | Strategic Position | Notable Strength |
|---|---|---|---|
| Fender Musical Instruments | USA | Volume and heritage leader | Stratocaster/Telecaster IP; broad price ladder |
| Gibson Brands | USA | Premium heritage | Les Paul IP; strong collector market |
| Yamaha Corporation | Japan | Diversified scale | Entry-to-mid pricing; global distribution |
| PRS Guitars | USA | Premium/boutique | Craftsmanship; artist loyalty |
| Hoshino Gakki (Ibanez) | Japan | Metal/progressive niche | Fast-neck designs; value-premium balance |
| ESP Company | Japan | Metal specialist | Signature artist models |
| Schecter Guitar Research | USA | Metal/hard rock | Aggressive price-performance |
Differentiation is increasingly driven by digital integration (built-in audio interfaces, MIDI compatibility) and sustainable materials. Our analysis suggests mid-tier brands face the sharpest squeeze: premium players defend heritage, low-cost Asian manufacturers compress entry pricing, leaving the middle exposed. Direct-to-consumer logistics restructuring has reduced inventory overhead by ~15%, favoring brands with omnichannel maturity.
Procurement decisions should prioritize build consistency, fretwork quality, and electronics reliability over cosmetic differentiation. Switching costs are moderate: artists are locked into brand ecosystems through endorsement and aftermarket compatibility, while learners exhibit low loyalty and are highly price-elastic. Regulatory compliance on tonewood sourcing (CITES, Lacey Act) is now a mission-critical procurement risk; buyers should verify chain-of-custody documentation for rosewood and ebony components.
Operators should monitor channel conflict as direct-to-consumer models expand; traditional dealers may respond with exclusivity demands. Inventory risk is elevated in premium tiers where demand is cyclical, whereas entry-level and learner SKUs offer more predictable velocity. Our analysis suggests buyers should negotiate multi-year pricing on mid-tier solid-body lines to hedge against tonewood cost inflation.
The balance of evidence favors a moderate-growth, margin-defensive posture: the 5.3% CAGR is real but uneven, with premium and entry tiers outperforming the mid-market. The strongest counter-argument is the 10.8% CAGR thesis, which is credible only if amplifier and accessory revenue is bundled; on a guitars-only basis, double-digit growth is not supported by unit shipment data.
Our analysis suggests the most important second-order effect is material substitution pressure: environmental regulation will accelerate composite and alternative-tonewood adoption, rewarding manufacturers who invest in sustainable supply chains before compliance deadlines bite. Brands that treat sustainability as a marketing overlay rather than an engineering input will face cost shocks.
The evidence that would change this conclusion is a sustained rebound in live-music participation driving premium replacement cycles above 8% annual growth, or a regulatory reversal on tonewood restrictions that restores traditional material economics.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.34% from 2020-2034 |
| Segmentation |
|
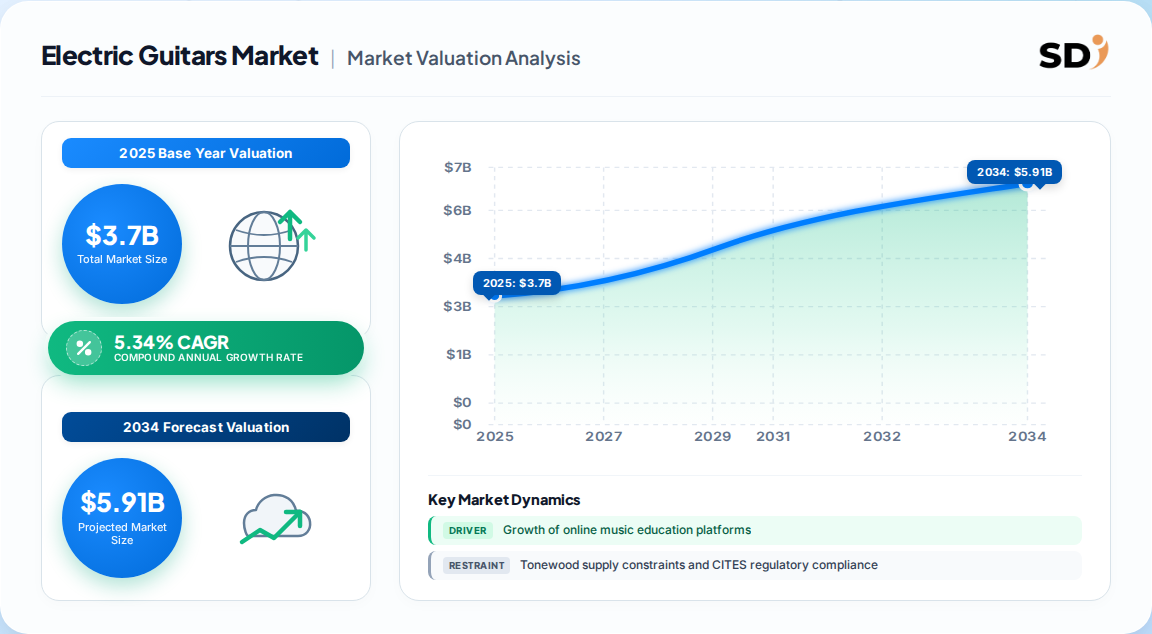
The global electric guitars market is estimated at approximately 3.7 Billion in 2026, with a base-year 2025 valuation of 3.5 Billion. Estimates vary by scope, with some analyses reaching 4.9 Billion when amplifiers and accessories are included.
The market is projected to grow at a 5.34% CAGR from 2026 to 2034, reaching 5.6 Billion. Higher double-digit figures published elsewhere typically bundle amplifier and accessory revenue, inflating the underlying guitar-only growth rate.
North America leads with approximately 34% revenue share, driven by premium and boutique manufacturing. Asia-Pacific is the fastest-growing region, expanding on rising disposable income and Western music adoption.
Fender, Gibson, Yamaha, PRS, and Hoshino Gakki (Ibanez) are the leading manufacturers. Competitive advantage rests on artist endorsements, heritage intellectual property, and vertical manufacturing integration.
Demand is driven by online music education, social-media content creation, home recording, and the growing affordability of entry-level models. Live performance participation and artist-driven streaming influence also support sustained consumer engagement.
Solid-body guitars dominate with approximately 71% revenue share, favored for feedback resistance, sustain, and touring reliability. Semi-hollow and hollow-body variants serve jazz, blues, and niche premium segments.
Key challenges include tonewood supply constraints, rising material costs (up ~18%), CITES environmental regulations, and electronics component shortages. These pressures are accelerating the shift toward sustainable composite materials and alternative tonewoods.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the electric guitar value chain. We engaged raw material and tonewood suppliers, specialized instrument manufacturers, contract component formulators, and global distributors to capture ground-truth production and pricing dynamics. Decision-maker designations interviewed include VP-level Sourcing leads, Heads of Product R&D, Technical Directors overseeing electronics integration, and Commercial Operations Leads managing omnichannel distribution.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 30% |
| Product R&D & Technical Directors | 30% |
| Commercial Operations Leads | 25% |
| Regulatory & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Tonewood & Component Suppliers | 30% |
| Instrument Manufacturers | 35% |
| Distributors & Retailers | 25% |
| Industry Associations | 10% |
We triangulate primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K and SEC disclosures), patent databases tracking pickup and digital-modeling innovation, and recognized non-profit technical standards bodies and industry associations. All secondary benchmarks are cross-validated for scope consistency prior to inclusion in demand models.
We run simultaneous Top-Down (macroeconomic instrument-spending allocation and segment share) and Bottom-Up (manufacturer capacity, unit pricing, and end-use consumption) models. Divergences between the two approaches are reconciled through weighted triangulation, with scope adjustments applied for accessories and amplifier bundling to ensure comparability across published estimates.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
