 Energy Harvesting Textiles Market
: Size, Trends & 2034 Outlook
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 183

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Energy Harvesting Textiles Market
Sandeep Singh
Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 4.230 B |
| 2026 | 5.180 B |
| 2027 | 6.350 B |
| 2028 | 7.770 B |
| 2029 | 9.520 B |
| 2030 | 11.66 B |
| 2031 | 14.28 B |

Energy harvesting textiles are advanced fabrics that capture ambient energy — body heat, motion, solar, vibration, or moisture — and convert it into usable electrical power for embedded sensors and electronics. They eliminate or reduce battery dependence, enabling self-powered wearables in healthcare, defense, sports, and industrial safety applications.
This report covers energy-harvesting smart textiles as a function segment within the global smart-textile and smart-fabrics ecosystem: piezoelectric, triboelectric, thermoelectric, photovoltaic, and moisture-gradient fabric systems, plus the substrate materials, conductive yarns, and integration processes that enable them. Coverage spans healthcare, defense, sports, industrial safety, fashion, and architecture end uses across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa.
This analysis does not cover conventional passive performance textiles, standalone rigid wearable electronics, textile manufacturing machinery, or apparel retail economics outside the harvesting-function value chain. Adjacent sensing-only and luminescence-only fabric markets are referenced for context but not sized here.
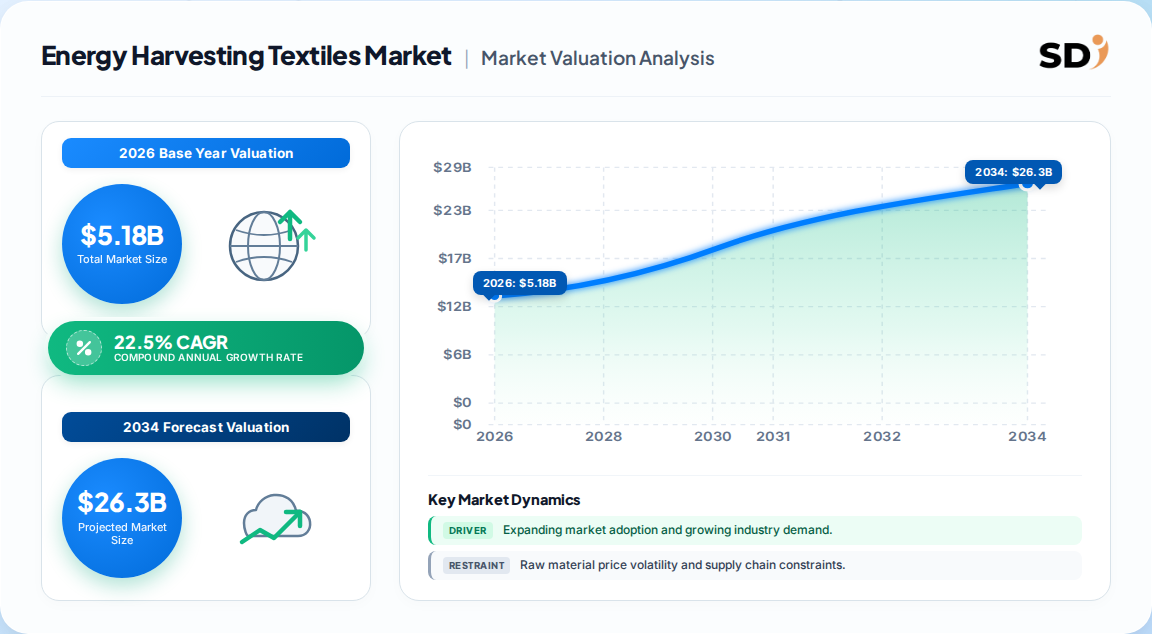
Defensible estimates place the parent smart-textile market near USD 5.18 billion in 2026, with energy-harvesting functions the fastest-growing layer at roughly 29.4% CAGR through 2034. Estimates diverge sharply because publishers define "smart textile" differently.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 5.18B → 26.30B | 2026 | 2034 | 22.51% | Smart textiles by type/function/end-use; value terms | One published estimate |
| USD 7.2B → 48.7B | 2026 | 2033 | 31.3% | Smart fabrics incl. very-smart and broad end-uses | A competing analysis |
| USD 9.18B → 24.14B | 2026 | 2035 | 11.30% | Smart textiles, conservative substitution curve | Another published estimate |
| 8.58M → 14.25M units | 2026 | 2031 | 10.68% | Volume (units), not value | Mordor-style volume study |
Our analysis suggests the 11–22% band is the most defensible for the total smart-textile envelope, because the 31.3% figure likely bundles adjacent flexible-electronics revenue and the 10.68% unit study excludes value uplift from premium harvesting functions. Energy harvesting's 29.4% CAGR sits logically above the blended market, since it starts from a smaller base and benefits from the miniaturization cost curve.
Segmentation splits along four axes — type, function, material, and end use — with energy harvesting appearing as a function sub-segment across every product tier.
| Parent | Children |
|---|---|
| By Type | Passive, Active, Ultra-smart |
| By Function | Sensing, Energy Harvesting, Luminescence & Aesthetics, Thermoelectricity, Others |
| By Material | Polyester & Nylon, Cotton, Wool & Silk, High-performance, Others |
| By End Use | Healthcare, Military & Defense, Sports & Fitness, Fashion & Entertainment, Automotive/Transportation, Architecture |
Energy harvesting technology itself bifurcates into piezoelectric/triboelectric (motion), thermoelectric (body heat), photovoltaic (solar), and moisture-gradient systems. Each carries distinct durability and washability constraints.
North America leads the energy-harvesting textile market on the strength of defense procurement, clinical reimbursement pilots, and flexible-electronics investment; Asia-Pacific is the fastest-growing region and the manufacturing engine for conductive yarns.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.24% |
| Asia-Pacific | 0.29% |
| South America | 0.05% |
| Middle East & Africa | 0.06% |
North America's share estimates range from 28% to 45% depending on whether defense contracts and rigid telemetry are folded in. Asia-Pacific's 12–13% regional CAGR (up to 29.7% in one aggressive forecast) reflects India's National Technical Textiles Mission and Chinese conductive-yarn capacity. Europe's circularity regulation is quietly reshaping product architecture toward recyclable conductive substrates.
The dominant driver is energy autonomy: textile-embedded supercapacitors and nanogenerators now remove the battery-replacement cycle, which is the single largest barrier to consumer and clinical adoption of smart garments.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Wearable-electronics ecosystem growth | Driver | Strong | +2.1% CAGR impact; university demos of solar/body-heat fabrics |
| Flexible-IC miniaturization | Driver | Strong | Module thickness down >60% since 2020; wash-survivable fiber computers |
| Textile energy-harvesting supercapacitors | Driver | Moderate–Strong | 96.6% voltage retention over 120 hrs flexing |
| Military cognitive-load mandates | Driver | Strong | Multi-year framework awards; ~USD 1.6B Army Soldier Lethality allocation |
| High fabrication cost | Restraint | Strong | −1.9% CAGR impact; premium over conventional apparel |
| Wash durability & reliability failure | Restraint | Strong | Conductors degrade under stretch, abrasion, laundering |
| Absent testing standards | Restraint | Moderate | No global interoperability baseline slows procurement |
The balance favors growth, but durability failure is the binding constraint. Our analysis suggests that until wash-cycle standards exist, the harvesting segment will scale fastest in non-laundered and low-wash applications — military outerwear, architectural textiles, automotive interiors — before it breaks into consumer apparel at scale.
Competition is medium-concentrated and split between material-science incumbents, textile specialists, and electronics integrators — no single firm owns the harvesting stack end to end.
| Company | Category | Core Strength |
|---|---|---|
| DuPont | Materials | Advanced fibers and protective substrates |
| Toray Industries | Materials | Conductive yarns, high-performance fabric |
| AIQ Smart Clothing | Textile Specialist | E-textile integration and garments |
| ThermoSoft International | Textile Specialist | Heated/thermoregulating fabric systems |
| Kolon Industries | Materials | Aramid and performance textiles |
| MIT / NREL / STELEC | Research Consortia | Fiber computers, distributed energy converters, recyclable conductive textiles |
Differentiation rests on wash durability and integration depth, not feature count. Incumbents with fiber-science IP hold a moat in substrates; electronics integrators hold a moat in miniaturized power management. The gap — who owns the interface — is where M&A and partnership activity concentrates.
Selection hinges on five mission-critical criteria: wash-cycle durability rating, power output stability under flex, substrate compatibility with existing garment manufacturing, regulatory compliance (medical-device and data-privacy rules for healthcare deployments), and total cost per garment over its usable life.
Procurement risk is concentrated in reliability failure. A harvesting garment that degrades after 30 launderings destroys the business case regardless of output specs. Buyers should demand accredited wash-cycle testing and specified voltage-retention thresholds before scaling orders. Switching costs are high once harvesting modules are designed into a garment line, so early vendor selection locks in years of supply relationships — negotiate durability warranties and second-source substrate options upfront. Regulatory compliance in healthcare (remote-monitoring reimbursement pathways) and military (reliability baselines that cascade into commercial specs) raises the certification bar and favors suppliers with documented test protocols.
The balance of evidence favors energy harvesting as the highest-value functional layer in the smart-textile stack. Its 29.4% projected CAGR outpaces sensing, luminescence, and thermoelectricity because it solves the adoption-killing battery bottleneck — and because the miniaturization cost curve is moving in its favor. The strongest counter-argument: if wash durability remains unsolved and no global testing standard emerges, the segment stalls in military and architectural niches and consumer apparel adoption drags. We weight this risk as real but surmountable within the forecast window, given active recyclable-conductive-textile and fiber-computer programs.
Actionable strategy:
Evidence that would change this conclusion: a credible global wash-cycle standard arriving early would accelerate consumer adoption and pull forward value; conversely, repeated field-failure disclosures in clinical pilots would push the timeline out and shift value toward replaceable-battery hybrid designs.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 22.5% from 2020-2034 |
| Segmentation |
|
The parent smart-textile market is valued near USD 5.18 billion in 2026, within which energy harvesting is the fastest-growing function segment at roughly 29.4% CAGR through 2034, according to aggregated industry benchmarks.
North America leads on defense procurement, clinical reimbursement pilots, and flexible-electronics investment. Asia-Pacific is the fastest-growing region, driven by India's National Technical Textiles Mission and Chinese conductive-yarn manufacturing capacity.
They power self-charging wearables in healthcare monitoring, military physiological sensing, sports performance apparel, industrial safety workwear, automotive interiors, and architectural textiles — removing or reducing battery dependence.
Wash durability and reliability failure are the binding constraints. Conductors degrade under stretch, abrasion, and laundering, and the absence of a global testing standard slows procurement and consumer adoption at scale.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain — conductive-yarn and substrate suppliers, specialized e-textile producers, flexible-electronics integrators, and global textile distributors — to capture both upstream material constraints and downstream adoption behavior. Decision-maker designations interviewed include VP-level Sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring that durability specifications, certification pathways, and volume commitments are validated against real procurement decisions rather than published assumptions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory & Compliance Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Conductive Yarn & Substrate Suppliers | 40% |
| E-Textile & Garment Producers | 30% |
| Flexible-Electronics Integrators | 20% |
| Distributors & Traders | 10% |
We cross-reference official multilateral trade statistics (UN Comtrade, WTO, US ITC, Eurostat) for conductive yarn and semiconductor trade flows, corporate annual filings and investor presentations (10-K, SEC filings), patent databases tracking conductive-yarn and flexible-IC activity, and recognized non-profit technical standards bodies and industry associations. No third-party market-research publisher is used as a validation source.
Estimates combine simultaneous top-down allocation (macroeconomic apparel capex, defense budget lines, healthcare reimbursement data) with bottom-up modeling (manufacturer capacity, product pricing, and end-use consumption by application). Divergent published estimates are reconciled through adoption-curve fitting calibrated to the installed manufacturing base.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
