Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Directed Energy Weapons Market: 2026 Size, Forecast & Trends
Directed Energy Weapons Market: 2026 Size, Forecast & Trends
Directed Energy Weapons Market
Directed Energy Weapons Market: 2026 Size, Forecast & Trends
Directed Energy Weapons Market by Type (High-Energy Laser, High-Power Microwave, Particle Beam), by Platform (Land, Airborne, Naval, Space), by Lethality (Lethal, Non-Lethal), by Power Class (Less Than 50 kW, 51-150 kW, More Than 150 kW), by End-User (Army, Navy, Air Force, Homeland Security), by Application (Counter-UAS, Counter-Rocket Artillery Mortar, Anti-Satellite, Area Denial), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa), by Latin America (Brazil, Argentina, Mexico) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 227
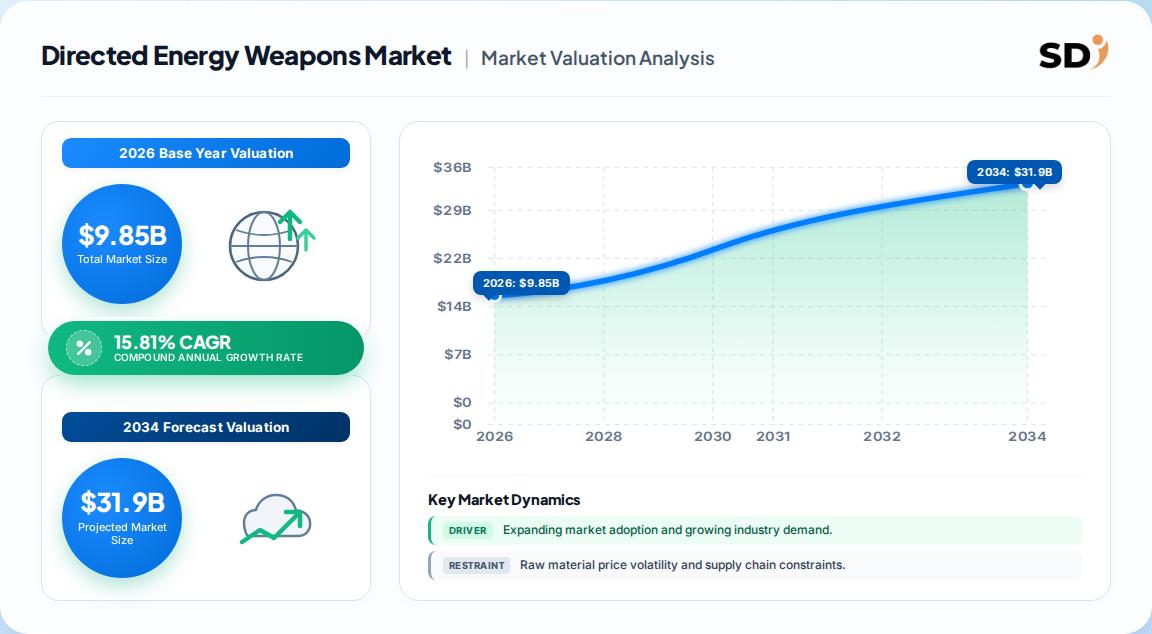
USD 9.85 Billion in 2026 (widest-scope consensus), with higher-end estimates reaching USD 20.51 Billion by 2031 and a 15.81% CAGR for 2026–2031.
A narrower prime-contractor revenue view values the market at USD 375 Million in 2026, rising to USD 1.02 Billion by 2035 — a huge scope divergence every buyer must reconcile.
High-energy lasers dominate at roughly 59–67% of revenue; high-power microwave is the fastest-growing sub-segment (est. 17.5% CAGR).
North America leads with ~37–46% revenue share, while Middle East & Africa and Asia Pacific show the steepest growth trajectories.
The top five vendors (Rafael, Elbit, Leidos/Dynetics, Lockheed Martin, MBDA) hold an estimated ~82% combined share in the prime-contractor view.
Why this matters for decision-makers: The cost-per-shot gap (a GBP 10 laser versus a GBP 1 million interceptor) is the single largest value driver — vendors that cannot prove repeatable thermal management and beam control at operational weights will lose procurement slots.
Budget timing risk is real: a FY2025 dip in U.S. unclassified DEW requests (USD 789.7M) suggests a 2028–2029 revenue trough; align capital commitments to 2030 recovery signals.
Directed Energy Weapons Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
9.850 B
2026
11.41 B
2027
13.21 B
2028
15.30 B
2029
17.72 B
2030
20.51 B
2031
Directed Energy Weapons Market Size (In Billion)
Year
Market Size
2026
9.850 B
2027
11.41 B
2028
13.21 B
2029
15.30 B
2030
17.72 B
2031
20.51 B
What is the Directed Energy Weapons Market?
Directed energy weapons are military systems that emit focused electromagnetic energy — high-energy lasers (HEL), high-power microwaves (HPM), or particle beams — to disable, damage, or destroy targets at near-light speed. Revenue is measured at the prime-contractor and subsystem level from contracted development, prototype delivery, and serial production.
Scope: what this report covers and excludes
This analysis covers HEL and HPM systems across land, airborne, naval, and space platforms, spanning both lethal and non-lethal effectors across defense, homeland security, and counter-UAS applications. It excludes classified U.S. programs and China's indigenous production from the central estimate, and it excludes conventional kinetic munitions, electronic-warfare jammers, and directed-energy medical or industrial laser segments. This analysis does not cover adjacent markets such as radar, C2 battle-management software, or space-based ISR sensors.
How big is the market for Directed Energy Weapons Market?
The size of the directed energy weapons market depends heavily on scope definition. Published estimates diverge by a factor of roughly 26x, ranging from a narrow prime-contractor revenue view of USD 375 Million to a broad USD 9.95 Billion system-level market.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
375 Million
2026
2035
11.76%
Prime-contractor & subsystem revenue; excludes classified U.S. and China
One published estimate
9.85 Billion
2026
2031
15.81%
Full system value incl. integration, all platform types
Competing analysis
9.95 Billion
2025
2034
15.11%
Full system value, defense + homeland security
Competing analysis
Our analysis suggests the broad system-level figure (USD 9.85–9.95 Billion) is the more defensible base for procurement planning, because operators acquire integrated systems, not bare prime contracts. The narrow estimate is useful for investor views on pure-play prime revenue but understates total cost of ownership by an order of magnitude.
How is the market segmented?
Segmentation is typically structured around technology, platform, lethality, power output, and end-user — each creating distinct procurement and integration requirements.
Counter-UAS, Counter-Rocket/Artillery/Mortar, Anti-Satellite, Area Denial
Lethal systems commanded ~59–68% of 2025 revenue, while non-lethal is the fastest-growing category (~15.6% CAGR). High-energy lasers represented roughly 61% of revenue; HPM is forecast to grow at ~17.5% CAGR through 2031.
Which region leads in Directed Energy Weapons Market?
North America leads the directed energy weapons market with an estimated 37–46% revenue share, anchored by U.S. DoD investment across DARPA, MDA, and all service branches. Asia Pacific and the Middle East are the fastest-growing regions, each posting double-digit CAGRs.
Directed Energy Weapons Market Regional Market Share
Loading chart...
Directed Energy Weapons Market Regional Market Share
Region
Market Share (%)
North America
0.38%
Europe
0.19%
Asia-Pacific
0.24%
Middle East & Africa
0.14%
Latin America
0.05%
Region
Share (Approx.)
North America
38%
Asia-Pacific
24%
Europe
19%
Middle East & Africa
14%
Latin America
5%
Geography tree (Parent / Children)
North America: USA, Canada, Mexico
Europe: Germany, UK, France, Italy
Asia Pacific: China, Japan, India, South Korea
Middle East & Africa: Saudi Arabia, UAE, Israel
Latin America: Brazil, Argentina, Mexico
This divergence implies that vendors must localize integration and support capabilities in the Middle East and Asia Pacific to capture growth share, while maintaining North American R&D pipelines for platform qualification.
What is driving growth — and what is holding it back?
Growth is driven primarily by cost-per-shot economics and the proliferation of drone swarms, while restraints center on budget cyclicality, prototype-only procurement, and atmospheric physics limits.
Factor
Direction
Evidence Strength
Mechanism
Cost-per-shot advantage
Driver
High
GBP 10 laser vs. GBP 1M interceptor transforms magazine depth
Counter-UAS / hypersonic threat
Driver
High
Drone swarms overwhelm kinetic inventories
GaN power electronics
Driver
Medium
Compresses 150 kW into destroyer-compatible footprints
Jammer-immune beams
Driver
Medium
Spectrum-denial resilience in contested EW environments
Budget pressure
Restraint
High
FY2025 U.S. request dipped to USD 789.7M, shifting revenue
Prototype-only procurement
Restraint
High
DEFEND HPM limited to USD 31.3M for two prototypes
Atmospheric attenuation
Restraint
Medium
Humidity/fog limits HEL operational range certification
The balance of evidence favors the drivers over the 2026–2031 horizon. Our analysis suggests the USD 789.7M FY2025 request dip is a timing artifact, not a demand collapse, and likely creates a 2028–2029 trough before 2030 recovery. The second-order effect: buyers win negotiating leverage on pricing during that trough, while suppliers must protect cash flow through sustained R&D.
Who are the leading vendors?
The competitive landscape is moderately concentrated, with an estimated top-five share of ~82% in the prime-contractor revenue view.
Company
Primary Focus
Notable Programs
Rafael Advanced Defense Systems
HEL, Iron Beam
Iron Beam serial production
Elbit Systems
HEL, vehicle-mount
Counter-UAS lasers
Lockheed Martin
HEL, HPM, naval
HELIOS, MDA glide-phase
Leidos / Dynetics
HPM
DEFEND HPM prototypes
MBDA
HEL, naval
DragonFire (UK)
RTX (Raytheon)
HPM, missiles
THOR, DEW-integrated systems
Northrop Grumman
HEL, space
Solid-state laser arrays
Differentiation is shifting from physics demonstration toward production engineering: thermal control, ruggedized optics, and power-density density. Our analysis suggests moats will be built not on patent portfolios but on qualified production lines and tested performance at operational weights.
What do buyers and operators need to know? (Decision Support)
Selection criteria are converging on repeatable demonstrated lethality, not laboratory power figures. Buyers should demand operational testing data — particularly for HEL systems under humid, foggy, and high-turbulence conditions where atmospheric attenuation can cut effective range by 30% or more.
Procurement risk is concentrated in the prototype-to-production transition. Programs that fail to clear government acceptance testing, like the DEFEND HPM path, delay revenue and force recompete. Buyers should contract for performance-based milestones rather than development cost-plus structures to align incentives.
Switching costs are rising as platforms integrate proprietary beam-control software and power-management architectures. Open-architecture mandates and sensor-to-shooter interoperability requirements are the best mitigants. Regulatory compliance with export-control regimes (ITAR, dual-use laser classifications) must be settled before platform selection, as post-award changes are prohibitively expensive.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a broad-scope market of USD 9.85–9.95 Billion in 2025–2026, with the narrow prime-contractor figure serving only as an investor-screening lens. The strongest counter-argument is that atmospheric physics and prototype-only funding could cap growth below 15%; however, naval trials (USS Preble, HMS DragonFire) and Iron Beam's 2024 combat deployment are converting skepticism into production contracts faster than the bears expect.
Our analysis suggests the decision-relevant insight is that cost-per-shot economics, not raw power output, will determine market winners through 2031. Vendors that cannot demonstrate sustainment economics at scale — including cooling, power budget, and consumable-free operation — will lose share to those that can.
Actionable Strategy:
Vendors: Prioritize thermal-management and beam-control integration engineering for airborne and vehicle-mounted platforms to capture the highest-CAGR (17%+) segments.
Buyers/Operators: Contract for performance-based milestones and test atmospheric attenuation in theater-representative conditions before committing to serial production.
Investors: Time capital deployment around the projected 2028–2029 budget trough, positioning for the 2030–2031 recovery cycle when HPM programs-of-record are expected to clarify.
What evidence would change this conclusion: a sustained FY2026–FY2027 U.S. budget cut below USD 500M for unclassified DEW, or two consecutive atmospheric tests failing operational range certification, would materially lower the CAGR outlook.
Directed Energy Weapons Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Directed Energy Weapons Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 15.81% from 2020-2034
Segmentation
By Type
High-Energy Laser
High-Power Microwave
Particle Beam
By Platform
Land
Airborne
Naval
Space
By Lethality
Lethal
Non-Lethal
By Power Class
Less Than 50 kW
51-150 kW
More Than 150 kW
By End-User
Army
Navy
Air Force
Homeland Security
By Application
Counter-UAS
Counter-Rocket Artillery Mortar
Anti-Satellite
Area Denial
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Middle East & Africa
Saudi Arabia
UAE
Israel
South Africa
Latin America
Brazil
Argentina
Mexico
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. High-Energy Laser
5.1.2. High-Power Microwave
5.1.3. Particle Beam
5.2. Market Analysis, Insights and Forecast - by Platform
5.2.1. Land
5.2.2. Airborne
5.2.3. Naval
5.2.4. Space
5.3. Market Analysis, Insights and Forecast - by Lethality
5.3.1. Lethal
5.3.2. Non-Lethal
5.4. Market Analysis, Insights and Forecast - by Power Class
5.4.1. Less Than 50 kW
5.4.2. 51-150 kW
5.4.3. More Than 150 kW
5.5. Market Analysis, Insights and Forecast - by End-User
5.5.1. Army
5.5.2. Navy
5.5.3. Air Force
5.5.4. Homeland Security
5.6. Market Analysis, Insights and Forecast - by Application
5.6.1. Counter-UAS
5.6.2. Counter-Rocket Artillery Mortar
5.6.3. Anti-Satellite
5.6.4. Area Denial
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Middle East & Africa
5.7.5. Latin America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. High-Energy Laser
6.1.2. High-Power Microwave
6.1.3. Particle Beam
6.2. Market Analysis, Insights and Forecast - by Platform
6.2.1. Land
6.2.2. Airborne
6.2.3. Naval
6.2.4. Space
6.3. Market Analysis, Insights and Forecast - by Lethality
6.3.1. Lethal
6.3.2. Non-Lethal
6.4. Market Analysis, Insights and Forecast - by Power Class
6.4.1. Less Than 50 kW
6.4.2. 51-150 kW
6.4.3. More Than 150 kW
6.5. Market Analysis, Insights and Forecast - by End-User
6.5.1. Army
6.5.2. Navy
6.5.3. Air Force
6.5.4. Homeland Security
6.6. Market Analysis, Insights and Forecast - by Application
6.6.1. Counter-UAS
6.6.2. Counter-Rocket Artillery Mortar
6.6.3. Anti-Satellite
6.6.4. Area Denial
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. High-Energy Laser
7.1.2. High-Power Microwave
7.1.3. Particle Beam
7.2. Market Analysis, Insights and Forecast - by Platform
7.2.1. Land
7.2.2. Airborne
7.2.3. Naval
7.2.4. Space
7.3. Market Analysis, Insights and Forecast - by Lethality
7.3.1. Lethal
7.3.2. Non-Lethal
7.4. Market Analysis, Insights and Forecast - by Power Class
7.4.1. Less Than 50 kW
7.4.2. 51-150 kW
7.4.3. More Than 150 kW
7.5. Market Analysis, Insights and Forecast - by End-User
7.5.1. Army
7.5.2. Navy
7.5.3. Air Force
7.5.4. Homeland Security
7.6. Market Analysis, Insights and Forecast - by Application
7.6.1. Counter-UAS
7.6.2. Counter-Rocket Artillery Mortar
7.6.3. Anti-Satellite
7.6.4. Area Denial
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. High-Energy Laser
8.1.2. High-Power Microwave
8.1.3. Particle Beam
8.2. Market Analysis, Insights and Forecast - by Platform
8.2.1. Land
8.2.2. Airborne
8.2.3. Naval
8.2.4. Space
8.3. Market Analysis, Insights and Forecast - by Lethality
8.3.1. Lethal
8.3.2. Non-Lethal
8.4. Market Analysis, Insights and Forecast - by Power Class
8.4.1. Less Than 50 kW
8.4.2. 51-150 kW
8.4.3. More Than 150 kW
8.5. Market Analysis, Insights and Forecast - by End-User
8.5.1. Army
8.5.2. Navy
8.5.3. Air Force
8.5.4. Homeland Security
8.6. Market Analysis, Insights and Forecast - by Application
8.6.1. Counter-UAS
8.6.2. Counter-Rocket Artillery Mortar
8.6.3. Anti-Satellite
8.6.4. Area Denial
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. High-Energy Laser
9.1.2. High-Power Microwave
9.1.3. Particle Beam
9.2. Market Analysis, Insights and Forecast - by Platform
9.2.1. Land
9.2.2. Airborne
9.2.3. Naval
9.2.4. Space
9.3. Market Analysis, Insights and Forecast - by Lethality
9.3.1. Lethal
9.3.2. Non-Lethal
9.4. Market Analysis, Insights and Forecast - by Power Class
9.4.1. Less Than 50 kW
9.4.2. 51-150 kW
9.4.3. More Than 150 kW
9.5. Market Analysis, Insights and Forecast - by End-User
9.5.1. Army
9.5.2. Navy
9.5.3. Air Force
9.5.4. Homeland Security
9.6. Market Analysis, Insights and Forecast - by Application
9.6.1. Counter-UAS
9.6.2. Counter-Rocket Artillery Mortar
9.6.3. Anti-Satellite
9.6.4. Area Denial
10. Latin America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. High-Energy Laser
10.1.2. High-Power Microwave
10.1.3. Particle Beam
10.2. Market Analysis, Insights and Forecast - by Platform
10.2.1. Land
10.2.2. Airborne
10.2.3. Naval
10.2.4. Space
10.3. Market Analysis, Insights and Forecast - by Lethality
10.3.1. Lethal
10.3.2. Non-Lethal
10.4. Market Analysis, Insights and Forecast - by Power Class
10.4.1. Less Than 50 kW
10.4.2. 51-150 kW
10.4.3. More Than 150 kW
10.5. Market Analysis, Insights and Forecast - by End-User
10.5.1. Army
10.5.2. Navy
10.5.3. Air Force
10.5.4. Homeland Security
10.6. Market Analysis, Insights and Forecast - by Application
10.6.1. Counter-UAS
10.6.2. Counter-Rocket Artillery Mortar
10.6.3. Anti-Satellite
10.6.4. Area Denial
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Directed Energy Weapons Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Directed Energy Weapons Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Directed Energy Weapons Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Directed Energy Weapons Market Revenue (Billion), by Platform 2026 & 2034
Figure 5: North America Directed Energy Weapons Market Revenue Share (%), by Platform 2026 & 2034
Figure 6: North America Directed Energy Weapons Market Revenue (Billion), by Lethality 2026 & 2034
Figure 7: North America Directed Energy Weapons Market Revenue Share (%), by Lethality 2026 & 2034
Figure 8: North America Directed Energy Weapons Market Revenue (Billion), by Power Class 2026 & 2034
Figure 9: North America Directed Energy Weapons Market Revenue Share (%), by Power Class 2026 & 2034
Figure 10: North America Directed Energy Weapons Market Revenue (Billion), by End-User 2026 & 2034
Figure 11: North America Directed Energy Weapons Market Revenue Share (%), by End-User 2026 & 2034
Figure 12: North America Directed Energy Weapons Market Revenue (Billion), by Application 2026 & 2034
Figure 13: North America Directed Energy Weapons Market Revenue Share (%), by Application 2026 & 2034
Figure 14: North America Directed Energy Weapons Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Directed Energy Weapons Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Directed Energy Weapons Market Revenue (Billion), by Type 2026 & 2034
List of Tables
Table 1: Directed Energy Weapons Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Directed Energy Weapons Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 3: Directed Energy Weapons Market Revenue Billion Forecast, by Lethality 2020 & 2034
Table 4: Directed Energy Weapons Market Revenue Billion Forecast, by Power Class 2020 & 2034
Table 5: Directed Energy Weapons Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 6: Directed Energy Weapons Market Revenue Billion Forecast, by Application 2020 & 2034
Table 7: Directed Energy Weapons Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Directed Energy Weapons Market Revenue Billion Forecast, by Type 2020 & 2034
Table 9: North America Directed Energy Weapons Market Revenue Billion Forecast, by Platform 2020 & 2034
Table 10: North America Directed Energy Weapons Market Revenue Billion Forecast, by Lethality 2020 & 2034
Table 11: North America Directed Energy Weapons Market Revenue Billion Forecast, by Power Class 2020 & 2034
Table 12: North America Directed Energy Weapons Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 13: North America Directed Energy Weapons Market Revenue Billion Forecast, by Application 2020 & 2034
Table 14: North America Directed Energy Weapons Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Directed Energy Weapons Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Directed Energy Weapons Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the directed energy weapons market in 2026?
The broad-scope market is estimated at USD 9.85 Billion in 2026, with higher-end views reaching USD 9.95 Billion. A narrower prime-contractor revenue view values the market at USD 375 Million, reflecting the wide scope divergence across published estimates.
2. What is the growth rate of the directed energy weapons market?
The broad-scope consensus CAGR is approximately 15.8% for 2026–2031, while the narrow prime-contractor view implies 11.76% through 2035. Growth is driven by cost-per-shot economics and counter-drone demand.
3. Which region dominates directed energy weapons production?
North America leads with roughly 37–46% revenue share, anchored by U.S. DoD investment. Asia Pacific and the Middle East are the fastest-growing regions, each posting double-digit CAGRs driven by threat proliferation and modernization.
4. What are the main types of directed energy weapons?
The main types are high-energy lasers (HEL), high-power microwaves (HPM), and particle beams. HEL dominates at roughly 59–67% of revenue, while HPM is the fastest-growing sub-segment at approximately 17.5% CAGR through 2031.
5. Who are the leading companies in the directed energy weapons market?
Leading companies include Rafael Advanced Defense Systems, Elbit Systems, Lockheed Martin, Leidos/Dynetics, MBDA, RTX, and Northrop Grumman. The top five held an estimated 82% combined share in the prime-contractor revenue view in 2025.
6. What is holding back the directed energy weapons market?
Key restraints include budget cyclicality (the FY2025 U.S. unclassified request dipped to USD 789.7 Million), prototype-only procurement that delays serial production, and atmospheric attenuation that limits laser operational range in humid or foggy conditions.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the directed energy value chain, including solid-state laser module suppliers, beam-control and optics producers, power-management subsystem manufacturers, and global defense-prime integration teams. Decision-makers interviewed included VP-level procurement leads, Heads of R&D, Technical Directors for beam control, and Commercial Operations Leads responsible for export licensing and contract negotiation.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Acquisition Leads
35%
R&D & Technical Directors
30%
Program Management Offices
20%
Commercial & Export Compliance Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Prime Contractors & System Integrators
40%
Laser & Optics Subsystem Producers
30%
Power Electronics & Beam Control Suppliers
20%
Government R&D & Testing Agencies
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official databases including UN Comtrade, the WTO, US ITC, and Eurostat bilateral defense-trade flows. Corporate 10-K filings, investor presentations, and patent filings from defense primes and photonics suppliers were cross-referenced. Technical standards and program documentation from recognized bodies and government research agencies were used to validate performance claims and procurement timelines.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down and bottom-up triangulation. Top-down, we allocate defense budget lines and segment spending by platform, power class, and end-user. Bottom-up, we model manufacturer production capacity, unit pricing, and end-use consumption, reconciling the two into a single base-year estimate with a defined scope boundary.
 Directed Energy Weapons Market