 Us Power Tools Market
US Power Tools Market Size, Share & Forecast to 2032
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 207

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Power Tools Market
Sandeep Singh
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 16.10 B |
| 2025 | 17.20 B |
| 2026 | 18.40 B |
| 2027 | 19.70 B |
| 2028 | 21.10 B |
| 2029 | 22.60 B |
| 2030 | 24.20 B |

The US power tools market covers electric, pneumatic and engine-driven tools — drills, saws, impact wrenches, grinders, hammers and fastening systems — sold to construction, industrial, automotive, energy and residential users. It is measured here as domestic demand (revenue) across offline and online channels, including corded and cordless variants of professional and consumer tiers.
This report sizes US demand for power tools by mode of operation (electric, pneumatic, other), product family, end-user and sales channel, for base year 2025 with a forecast to 2032. It captures cordless and corded electric tools, pneumatic tools and engine-driven tools sold through professional distribution, retail and e-commerce. Its volume view covers unit shipments of cordless tools where platform data is available. This analysis does not cover hand tools, power tool accessories as a standalone market, garden/outdoor power equipment, or the industrial fasteners that tools install, each of which has distinct supply chains and buyer economics.
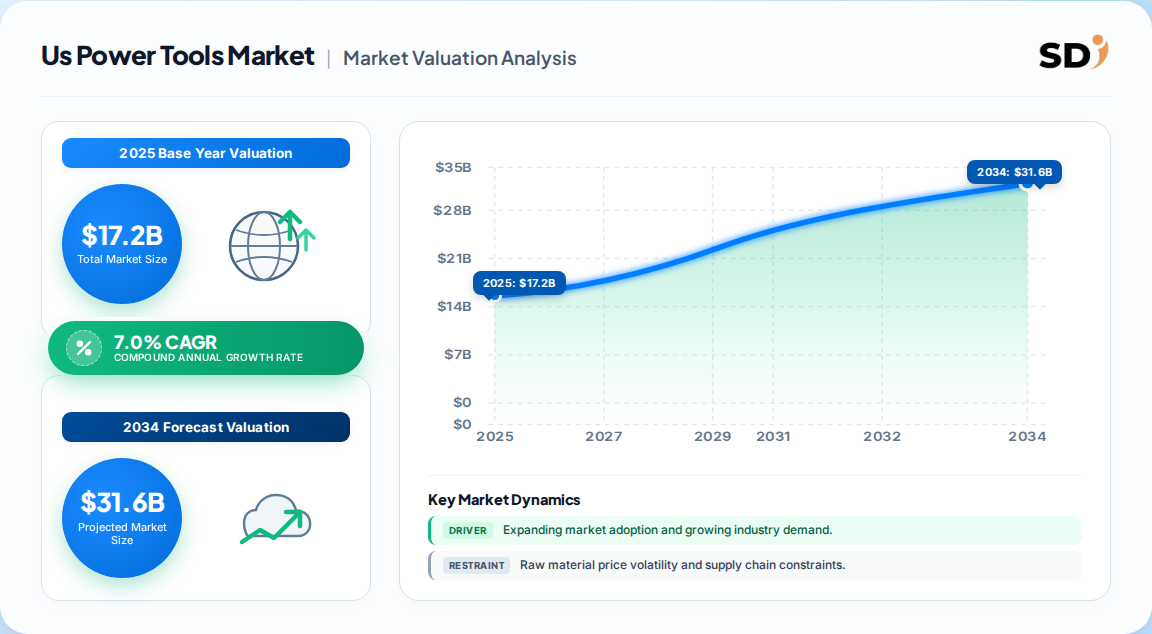
Most published benchmarks place US power tools demand between roughly 16 and 18 Billion in 2025, with the spread driven mainly by whether pneumatic and engine-driven categories are included. Our base case of 17.2 Billion sits mid-range and reflects a market growing near 7% in nominal terms through 2032.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| ~17.2 Billion | 2025 | 2032 | 7.0% | All power tools, US demand, value | Our triangulated estimate |
| ~15.9 Billion | 2025 | 2032 | 6.6% | Electric-led global share applied to US | One published estimate |
| ~18.1 Billion | 2024 | 2029 | 3.7% | Global demand model, US share extracted | A competing analysis |
| ~16.5 Billion | 2026 | 2035 | 9.0% | Electric-heavy, US regional split | Another industry study |
The divergence between the low-3% and high-9% CAGRs is largely definitional. The 3.7% figure is inflation-adjusted and includes mature pneumatic categories; the 9.9% headline is a nominal global figure weighted toward fast-growing cordless categories. Our analysis suggests the defensible US range is 6.5–7.5% nominal, with cordless conversion supplying most of the upside and pneumatic/engine tool erosion acting as a drag.
Segmentation follows four buyer-relevant axes: how the tool is powered, what job it performs, who uses it, and where it is purchased. Cordless electric tools account for the majority of incremental value, but pneumatic tools remain embedded in automotive and heavy-maintenance workflows.
| Parent segment | Children |
|---|---|
| Mode of Operation | Electric (corded, cordless), Pneumatic, Engine-driven, Hydraulic & powder-actuated |
| Product | Drilling & fastening (drills, impact drivers, impact wrenches), Sawing & cutting, Demolition, Material removal, Routing, Layout & other |
| Motor & Battery | Brushed, Brushless; 12V, 18V/20V, 40V, 40V+ |
| End-user | Construction & infrastructure, Industrial (automotive, aerospace, energy), Residential & DIY |
| Sales Channel | Offline (distributor, retail), Online |
Sun Belt construction corridors — Texas, Florida, Arizona and the Southeast — lead US power tools demand, reflecting population migration, data-center and semiconductor fab build-outs, and storm-repair activity. Traditional manufacturing belts in the Midwest remain strong but grow more slowly.
| Region | Market Share (%) |
|---|---|
| North America | 0.29% |
| Europe | 0.22% |
| Asia-Pacific | 0.33% |
| Latin America | 0.09% |
| Middle East & Africa | 0.07% |
Our analysis suggests the South will add the largest absolute dollar volume through 2032, but the West carries the highest average revenue per professional user because of precision-installation and cleanroom tooling requirements.
Demand is being pulled by three credible forces: CHIPS Act fab construction, public infrastructure capex, and cordless platform substitution. Restraints are narrower but real — battery input costs and skilled-labor scarcity slow conversion of funded projects into tool purchases.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| CHIPS Act semiconductor megafab build-outs | Growth | High | Precision installation tooling demand over 4+ year build cycles |
| Infrastructure and public capex | Growth | High | Funded projects translate into professional tool purchases |
| High-voltage cordless substitution | Growth | High | Rental fleets and contractors replace corded, pneumatic, gas tools |
| Battery input-cost volatility (cobalt quotas) | Restraint | Medium | Raises cordless kit prices; delays platform upgrades |
| Construction labor scarcity | Restraint | Medium | Limits crews available to execute funded work |
| Post-pandemic consumer correction | Restraint | Medium | DIY demand normalizing after 2021 surge |
The balance clearly favors growth. Cordless substitution is the single largest structural driver because it expands the addressable market rather than merely shifting share. The key risk is timing: fab and infrastructure capex converts to tool demand only as construction packages execute, so quarterly demand can lag headline investment announcements by several quarters.
The US market is moderately concentrated, with five global platforms controlling the majority of professional-channel revenue. Differentiation rests on battery ecosystems, professional brand loyalty and distribution depth rather than on individual tool performance.
| Vendor | Core US position | Battery platform | Strategic strength |
|---|---|---|---|
| Stanley Black & Decker (DeWalt/Craftsman) | Broad professional + consumer | 20V MAX, FlexVolt | Channel breadth, brand recall |
| Techtronic Industries (Milwaukee, Ryobi) | Professional + prosumer | M18, MX FUEL | ONE-KEY digital, jobsite loyalty |
| Bosch | Professional | 18V, ProCORE | Battery tech, European engineering |
| Makita | Professional | 18V LXT, XGT | Runtime leadership, cordless depth |
| Hilti | Premium professional | Nuron 22V | Service model, heavy-duty niches |
Our analysis suggests the competitive moat is the battery platform, not the tool. Once a contractor standardizes on M18, 20V MAX or LXT, switching costs rise sharply across dozens of tools, chargers and digital fleet services. This is why Milwaukee's ONE-KEY and Hilti's Nuron expansion matter more than any single product launch.
Procurement decisions should be anchored on total platform cost, not sticker price. A 20% discount on a single tool is trivial against the cost of migrating a 40-tool fleet to a new battery system. Buyers should map existing battery inventory before committing to any new platform and should demand written runtime and warranty terms under realistic load.
Battery safety and counterfeit risk are material. Counterfeit batteries and unauthorized UL marks pose fire and injury hazards, and reputable vendors increasingly require serialized, traceable packs. Operators should verify UL or ETL listing, insist on genuine OEM batteries, and audit online-marketplace purchases where counterfeit penetration is highest.
Regulatory and labor factors also shape selection. Federal and state jobsite rules on silica dust and noise favor tools with integrated dust extraction and low-vibration designs. Meanwhile, skilled-labor scarcity raises the value of tools that reduce setup time — cordless nailers and high-capacity batteries directly offset crew constraints.
Finally, digital fleet management is becoming a procurement criterion. Contractors managing multiple jobsites increasingly expect Bluetooth-enabled tracking, service records and theft recovery. Buyers evaluating a five-year platform commitment should weight these capabilities heavily, as retrofitting them later is costly.
The balance of evidence favors a constructive but disciplined view of the US power tools market. Growth of roughly 7% nominal through 2032 is well supported by cordless substitution and federally funded construction, and the US remains the highest-value country market globally. The strongest counter-argument is timing risk: infrastructure and fab capex can be announced years before tools are purchased, and battery-cost volatility could compress kit margins in the interim. We nonetheless see the structural drivers as durable and the cyclical risks as manageable.
For vendors, the strategic imperative is platform depth over SKU breadth. The winners will be those who convert contractors to a single battery ecosystem and then monetize that ecosystem through accessories, service and digital tools. For distributors, the imperative is to become the platform-agnostic advisor that helps buyers avoid lock-in mistakes. For investors, the signal to watch is high-voltage cordless adoption in rental fleets, which historically precedes broader contractor conversion.
What would change our conclusion? A sustained reversal in cordless adoption driven by battery-cost shocks, or a sharp slowdown in funded US construction, would push the market toward the low-3% growth scenario. Conversely, faster-than-expected AI-enabled smart-tool adoption could lift professional upgrade cycles above our base case.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.0% from 2020-2034 |
| Segmentation |
|
The US power tools market is valued at approximately 17.2 Billion in 2025, making it the world's largest single country market at roughly 29% of global revenue. Growth is projected at about 7% annually through 2032.
High-voltage cordless professional tools are growing fastest, led by impact drivers and wrenches. Cordless platforms are displacing corded, pneumatic and gas-powered equipment across construction, industrial maintenance and rental fleets.
Stanley Black & Decker (DeWalt), Techtronic Industries (Milwaukee), Bosch, Makita and Hilti lead the US market. Competition centers on battery-platform ecosystems, professional brand loyalty and distribution depth rather than individual tool specifications.
CHIPS Act semiconductor fab construction, public infrastructure capex, and cordless substitution are the primary drivers. Battery technology advances now enable cordless tools to compete in high-power professional applications previously dominated by corded and pneumatic equipment.
Battery input-cost volatility, particularly cobalt export quotas, and construction labor scarcity are the main restraints. Counterfeit batteries also pose safety and liability risks for buyers sourcing through unverified online channels.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the power tool value chain, including battery-cell and motor-component suppliers, specialized tool producers, contract manufacturers, and national industrial distributors. Within these organizations we engaged decision-makers designated as VP of Sourcing, Heads of Product R&D, Technical Directors, and Commercial Operations Leads. Interviews focused on platform economics, channel dynamics, pricing behavior and adoption timing.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product & R&D Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Commercial & Channel Operations | 25% |
| Regulatory & Safety Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Tool & Component Manufacturers | 40% |
| Battery & Motor Suppliers | 25% |
| Industrial Distributors & Retailers | 25% |
| Contractors & Rental Fleets | 10% |
We validated findings against official multilateral trade and standards databases, including UN Comtrade, WTO tariff schedules, US International Trade Commission import data, and Eurostat trade flows. Corporate 10-K filings, SEC disclosures and investor presentations from listed manufacturers informed capacity and revenue cross-checks. Patent databases and recognized technical standards bodies, including UL and ISO, supported product-safety and certification analysis.
We triangulated market size through simultaneous top-down and bottom-up approaches. The top-down model allocated macroeconomic construction and manufacturing output to power tool demand by end-use segment. The bottom-up model aggregated manufacturer capacity, product pricing and end-use consumption to derive revenue. Divergences were reconciled against trade data and channel checks.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |