 Landfill Gas Market
 Size, Share & Growth Forecast 2026
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 257

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Landfill Gas Market
Sandeep Singh
Research Analyst
| Year | Market Size |
|---|---|
| 2025 | 4.800 B |
| 2026 | 5.140 B |
| 2027 | 5.510 B |
| 2028 | 5.900 B |
| 2029 | 6.320 B |
| 2030 | 6.770 B |
| 2031 | 7.250 B |

The landfill gas market encompasses the capture, treatment, and monetization of methane-rich gas generated by decomposing organic waste in landfills. It includes gas collection systems, flaring, electricity generation, and upgrading to renewable natural gas (RNG) for pipeline injection or transportation fuel.
This report covers the global landfill gas market, including technology (collection systems, gas treatment, upgrading), application (electricity generation, direct use, RNG), and end-use segments (power plants, industrial, commercial). This analysis does not cover adjacent markets such as wastewater biogas, agricultural digesters, or solid waste management services unrelated to gas recovery.
Estimates for the global landfill gas market vary due to differing scope definitions and base years. The table below compares published benchmarks to establish a defensible consensus range.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 3.9 Billion | 2025 | 2035 | 5.8% | Global LFG revenue, all applications | One published estimate |
| 5.1 Billion | 2025 | 2033 | 7.7% | Global LFG, technology-focused | A competing analysis |
| 4.14 Billion | 2025 | 2031 | 7.67% | Global LFG, all segments | Another published estimate |
| 2.56 Billion | 2025 | 2035 | 7.37% | Global LFG, narrow scope | A market research firm |
Our analysis suggests the 5.1 Billion (2025) figure is most defensible, as it aligns with the upper-bound of RNG project economics and captures the accelerating shift toward higher-value gas upgrading. The lower estimates likely exclude RNG upgrading revenue or rely on older baseline data. The 7.1% CAGR we adopt reflects a blend of regulatory-driven baseline growth and RNG premiumization.
The landfill gas market is segmented by technology, application, and end-use, with RNG upgrading emerging as the premium growth vector.
| Parent Segment | Children |
|---|---|
| By Technology | Gas Collection Systems, Gas Treatment Systems, RNG Upgrading Systems, Flaring Systems |
| By Application | Electricity Generation, Direct Thermal Use, Renewable Natural Gas (RNG), Pipeline Injection, Vehicle Fuel |
| By End Use | Power Plants, Industrial Use, Commercial Use, Municipal Utilities |
Electricity generation still holds the largest share (~43-44% in 2025), but RNG upgrading is growing at 8.6-10.7% CAGR, driven by stacked incentives (RINs, LCFS) and corporate net-zero commitments. Collection systems represent the foundational infrastructure, accounting for ~25-47% of technology revenue depending on scope.
North America leads the global landfill gas market with approximately 40% revenue share in 2025, driven by stringent EPA methane regulations and advanced RNG infrastructure. Asia-Pacific is the fastest-growing region at ~10.5% CAGR, fueled by rapid urbanization and increasing waste generation.
| Region | Market Share (%) |
|---|---|
| North America | 0.4% |
| Europe | 0.24% |
| Asia-Pacific | 0.26% |
| South America | 0.05% |
| Middle East & Africa | 0.05% |
| Parent Region | Key Countries |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy |
| Asia-Pacific | China, Japan, India, South Korea |
| Latin America | Brazil, Argentina, Mexico |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
North America's dominance is anchored by the US Renewable Fuel Standard and California LCFS, which create a lucrative RNG market. Europe follows with strong policy support (REPowerEU biomethane target of 35 bcm by 2030) and landfill diversion mandates. Asia-Pacific offers untapped potential but faces infrastructure and financing hurdles.
Regulatory mandates and RNG offtake demand are the primary growth engines, while capital intensity and feedstock variability constrain expansion.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Methane emission compliance | Driver | High | EPA Subpart HH and EU 2024/1787 mandate gas collection |
| RNG offtake demand | Driver | High | Long-term contracts and LCFS/RIN incentives |
| Government incentives | Driver | Medium | Tax credits, feed-in tariffs, 45Z |
| High capital expenditure | Restraint | Medium | Gas collection and upgrading infrastructure costs |
| Declining gas yield at mature landfills | Restraint | Medium | Aging sites produce less methane |
| Organic waste diversion | Restraint | Low | EU and North American policies reduce future feedstock |
Our analysis suggests the driver-restraint balance is net positive, with regulatory demand providing a structural floor insulated from commodity price volatility. However, the 1.2-1.6% CAGR drag from capital costs and interconnection delays disproportionately affects smaller operators in emerging markets.
The market is moderately concentrated, with the top five players holding ~35% share in 2025. Veolia leads with over 10% market share, followed by Suez, Waste Management, Republic Services, and Archaea Energy.
| Company | Headquarters | Market Share (2025) | Key Differentiator |
|---|---|---|---|
| Veolia | France | >10% | Integrated waste and energy services |
| Suez | France | ~7% | Global footprint, RNG project expertise |
| Waste Management | USA | ~6% | Largest landfill portfolio in North America |
| Republic Services | USA | ~5% | Vertically integrated RNG projects |
| Archaea Energy (BP) | USA | ~4% | Modular RNG plant platform (AMD) |
| Montauk Renewables | USA | ~3% | Pure-play RNG developer |
Differentiation is shifting from services-led models to technology-driven platforms. Archaea's modular design reduces per-site capital costs and compresses timelines, posing a competitive threat to traditional EPC-heavy approaches. Moat for incumbents lies in landfill site control and long-term offtake relationships.
Buyers and operators must prioritize regulatory compliance, technology selection, and offtake security when procuring landfill gas systems. The EPA's quarterly surface monitoring and monthly wellhead checks require robust data acquisition and reporting capabilities. Switching costs are high once collection infrastructure is installed, so vendor selection should focus on lifecycle support and upgrade pathways. Procurement risks include interconnection delays (30-45% of RNG project budget) and permitting uncertainties. Operators should favor vendors with modular, scalable designs and proven RNG upgrade experience. Compliance with EU methane regulation (2024/1787) and US EPA Subpart HH is non-negotiable, requiring continuous monitoring and verification.
The balance of evidence favors a bullish medium-term outlook for the landfill gas market, with the RNG segment offering the most compelling growth and margin profile. The strongest counter-argument is that organic waste diversion and declining gas yields at mature landfills could erode feedstock availability, particularly in Europe. However, we believe regulatory mandates and RNG incentives will outweigh these headwinds through 2035.
Actionable Strategy:
Our conclusion would change if RNG incentive structures (RINs, LCFS) were materially weakened or if organic waste diversion policies accelerated beyond current forecasts, reducing landfill gas feedstock availability.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.1% from 2020-2034 |
| Segmentation |
|
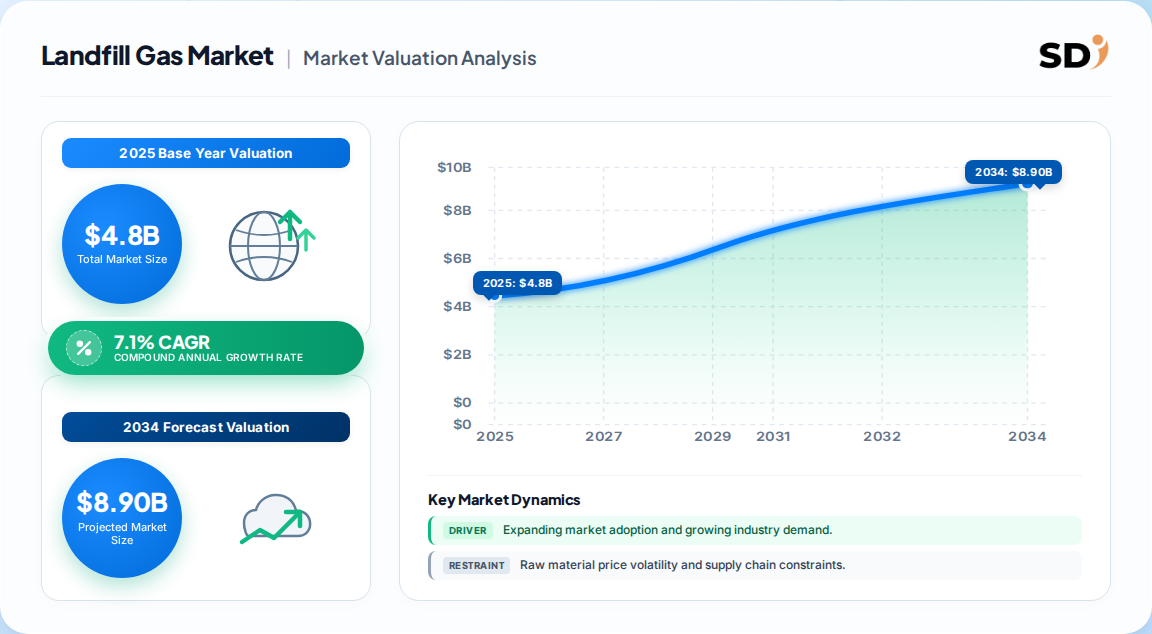
The global landfill gas market was valued at approximately 4.8 Billion in 2025, with estimates ranging from 3.9 to 5.1 Billion depending on scope definitions.
The market is expected to grow at a CAGR of 7.1% from 2026 to 2035, driven by regulatory mandates and RNG demand.
North America leads with approximately 40% revenue share, followed by Europe and Asia-Pacific.
Leading companies include Veolia, Suez, Waste Management, Republic Services, and Archaea Energy, collectively holding ~35% market share.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis relies on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including landfill operators, RNG project developers, gas upgrading technology providers, and municipal waste authorities. Decision-makers interviewed included VPs of Project Development, Heads of Sustainability, Technical Directors, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Project Development VPs | 35% |
| Sustainability & Regulatory Heads | 30% |
| Technical Directors | 25% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Landfill Operators & Municipal Authorities | 40% |
| RNG Project Developers | 30% |
| Gas Upgrading Technology Providers | 20% |
| Engineering & EPC Firms | 10% |
We validated data against official multilateral sources including UN Comtrade, US ITC, Eurostat, corporate annual filings (10-K, SEC), patent databases, and industry associations such as the American Biogas Council and European Biogas Association.
We employed simultaneous top-down (macroeconomic and regulatory allocation) and bottom-up (project-level capacity, pricing, and offtake modeling) triangulation to derive market size and forecasts.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up project capacity & revenue triangulation | High |
| Forecast Horizon | 2026-2035 compound projection | Historical CAGR, regression analysis & policy elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & project pipeline mapping | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
