 Us Energy Management Systems Ems Market
U.S. Energy Management Systems EMS Market 2025
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 192

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Energy Management Systems Ems Market
Sandeep Singh
Research Analyst
| Year | Market Size |
|---|---|
| 2023 | 12.70 B |
| 2024 | 14.15 B |
| 2025 | 15.76 B |
| 2026 | 17.56 B |
| 2027 | 19.56 B |
| 2028 | 21.79 B |
| 2029 | 24.27 B |

The U.S. Energy Management Systems (EMS) market comprises hardware, software, and services that monitor, control, and optimize electricity and fuel consumption across industrial, commercial, institutional, and residential sites. It spans industrial (IEMS), building (BEMS), and home (HEMS) systems, increasingly delivered via cloud with AI-driven load optimization and virtual power plant participation. This analysis covers U.S.-based EMS demand and does not cover global adjacent markets such as standalone demand-response aggregators, pure-play grid automation, or residential solar financing.
This report covers U.S. EMS demand across system type (IEMS, BEMS, HEMS), component (hardware, software, services), deployment (on-premises, cloud), and vertical (manufacturing, commercial, residential, energy & power, healthcare, telecom & IT, retail). It addresses market sizing, segmentation, drivers, restraints, vendor positioning, and procurement decision support. Exclusions: This analysis does not cover Canada or Mexico in detail, nor does it cover adjacent markets like standalone grid automation hardware, renewable energy development, or building construction services. It also excludes pure-play energy trading platforms that do not perform monitoring or control functions.
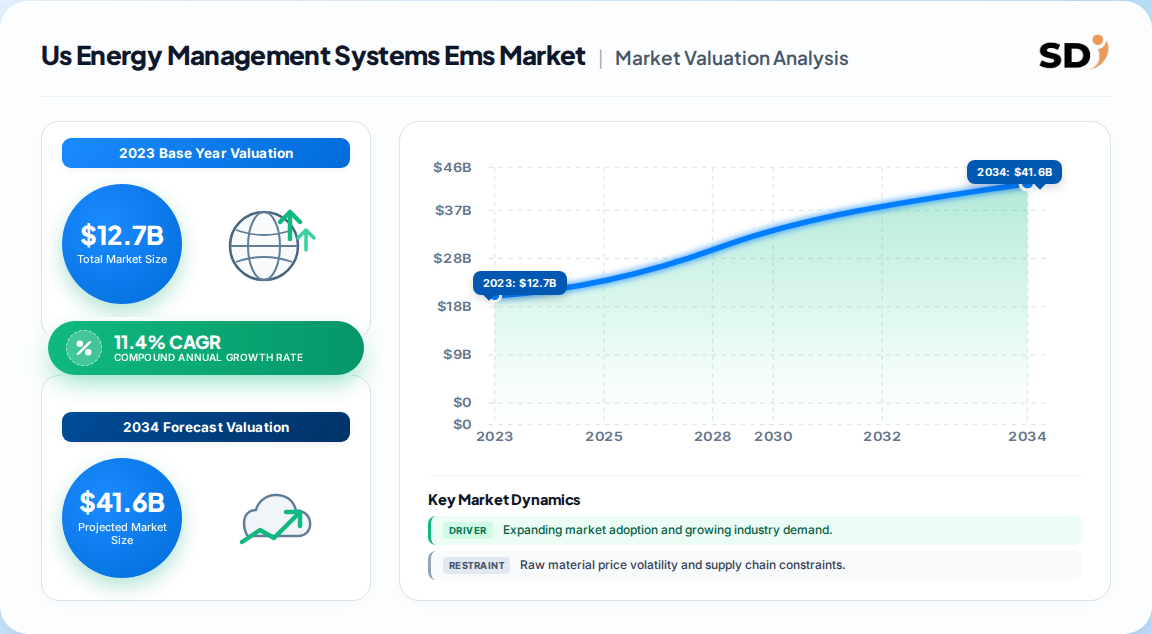
The U.S. EMS market was valued at USD 12.70 billion in 2023 and is projected to grow at 11.4% CAGR from 2024 to 2030, implying approximately USD 27 billion by 2030. Published estimates diverge because of differing scope definitions — some include services, some only hardware and software, and some blend global or North American figures.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 12.70 Billion | 2023 | 2024–2030 | 11.4% | U.S. EMS, full stack (hardware, software, services) | One published estimate |
| ~15.31 Billion (NA) | 2025 | 2026–2031 | 14.85% | North America EMS, all end-user sectors | A competing analysis |
| 38.6% of 57.42 Billion (Global) | 2025 | 2026–2034 | 15.99% | Global EMS, product-led segmentation | A competing analysis |
The 12.70 billion / 11.4% figure is the most defensible U.S.-specific anchor because it isolates U.S. demand and full-stack revenue. The North American and global estimates imply a faster trajectory, but their broader scopes (Canada, Mexico, and global product mix) inflate comparability. Our analysis suggests a U.S. base near 13.5–14.0 billion in 2024, with the gap to 2030 closing via software and services mix shift rather than hardware volume alone.
Segmentation by system type, component, deployment, and vertical reflects how buyers procure EMS: industrial operators prioritize real-time control, while commercial and residential buyers prioritize cost visibility and automation.
| Parent Segment | Children |
|---|---|
| System Type | Industrial EMS (IEMS), Building EMS (BEMS), Home EMS (HEMS) |
| Component | Hardware (sensors, controllers, meters, displays), Software, Services |
| Deployment | On-premises, Cloud-based |
| Vertical | Manufacturing, Commercial, Residential, Energy & Power, Healthcare, Telecom & IT, Retail |
IEMS dominated 2023 revenue at 74.5% because manufacturing and industrial facilities are the heaviest energy users and the earliest adopters of IoT, big data, and cloud analytics. BEMS is the fastest-rising system type as smart-meter penetration and space-heating electrification push building owners toward cloud platforms. On the component side, hardware leads current spend, but software is the fastest-growing component because it converts meter data into actionable savings and compliance reporting.
The South leads U.S. EMS demand, anchored by Texas, Florida, and the Gulf Coast industrial corridor, where high cooling loads, dynamic utility tariffs, and dense manufacturing drive adoption. The West follows closely, led by California's dynamic pricing programs and aggressive building codes.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.22% |
| South | 0.28% |
| Midwest | 0.21% |
| West | 0.24% |
| Others | 0.05% |
| Region | Share |
|---|---|
| South | 28% |
| West | 24% |
| Northeast | 22% |
| Midwest | 21% |
| Others | 5% |
Our analysis suggests the South will outpace the national CAGR by 1–2 points through 2030, driven by data-center load growth and industrial reshoring. Vendors should prioritize Texas and the Southeast for VPP-ready, flexibility-monetizing EMS configurations.
Growth is driven by federal retrofit incentives, smart-grid and AMI rollouts, corporate net-zero mandates, and dynamic utility tariffs, while high upfront costs, cybersecurity concerns, and integrator shortages restrain adoption among mid-sized and residential buyers.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Inflation Reduction Act retrofit incentives | Driver | Strong | Cuts payback periods; up to USD 5/sq ft deductions |
| Smart-grid and AMI penetration | Driver | Strong | Granular load data enables AI optimization and VPP |
| Corporate VPP and net-zero procurement | Driver | Moderate | 67 GW of clean PPAs signed in 2024 |
| Dynamic real-time utility tariffs | Driver | Moderate | Rewards automated load shifting every 30 minutes |
| High upfront and O&M costs | Restraint | Strong | Turnkey mid-size systems exceed USD 50,000 |
| Data-security and privacy concerns | Restraint | Moderate | Critical-infrastructure and residential hesitancy |
| Integrator skill-set shortage | Restraint | Moderate | Delays deployment, especially rural and secondary markets |
| Legacy protocols and interoperability gaps | Restraint | Moderate | Fragmented building stock raises integration cost |
The balance favors growth: incentive-driven payback compression and AMI data availability outweigh cost and skills friction in the near term. However, the restraint mix is not evenly distributed — mid-sized commercial and residential buyers bear the brunt of upfront-cost and skills gaps. Our analysis suggests vendors that offer energy-as-a-service or performance-contract structures will capture disproportionate share in those underpenetrated tiers.
The U.S. EMS landscape is moderately concentrated, with global building-automation and industrial incumbents competing against software-first specialists and utility-adjacent platforms.
| Vendor Type | Representative Players | Differentiation | Moat |
|---|---|---|---|
| Building automation incumbents | Honeywell, Johnson Controls, Schneider Electric, Siemens | End-to-end hardware + software + service | Installed base and channel lock-in |
| Industrial automation | Rockwell Automation, ABB, Emerson | Plant-floor integration, real-time control | Protocol depth and OT trust |
| Software-first specialists | EnergyCAP, GridPoint, Lucid | Analytics, dashboards, VPP orchestration | Data models and integrations |
| Utility-adjacent platforms | DNV, AutoGrid, Enel X | Demand response, VPP aggregation | Utility relationships and tariff data |
Incumbents defend through installed-base lock-in and multi-year service contracts; specialists win on speed of deployment and analytics depth. Our analysis suggests M&A activity will intensify as hardware incumbents buy software capabilities to defend margin — the DNV/ANB Systems deal in 2023 is a template. Buyers should expect consolidation to raise switching costs and should negotiate data-portability clauses upfront.
Buyers should prioritize interoperability, cybersecurity posture, and total cost of ownership over headline license price. The most common procurement failure is selecting a platform optimized for one protocol or vendor ecosystem, then facing five-figure integration costs when the estate expands. Require documented support for open protocols (BACnet, Modbus, OpenADR) and clear API access.
Regulatory compliance is a second critical filter. DOE baseline efficiency standards, EPA-aligned reporting, and ISO 50001 alignment increasingly determine which platforms qualify for incentive programs. Buyers should verify that the vendor's reporting engine maps to the specific utility or state incentive they intend to claim.
Switching costs are material: multi-year service contracts, proprietary data models, and integrator relationships create lock-in. Our analysis suggests buyers should insist on data-export rights and modular contract structures — a 3-year base term with expansion options rather than a single 7-year bundle. For mid-sized buyers, energy-as-a-service structures transfer performance risk and should be evaluated against outright purchase on a 5-year NPV basis, not year-one capex.
Vendors, in turn, should recognize that buyer sophistication is rising: procurement teams now benchmark payback against incentive stacks, not just energy savings. Those who can quantify incentive-adjusted ROI at the proposal stage will shorten sales cycles.
The balance of evidence favors a software-and-services-led growth thesis for the U.S. EMS market. Hardware remains the volume base, but the 11.4% CAGR is increasingly carried by analytics, VPP orchestration, and recurring service revenue. The strongest counter-argument is that hardware incumbents' installed bases and channel control will let them re-capture software margin through bundling — a real risk, but one that historically compresses specialist multiples rather than reversing the mix shift.
Our analysis suggests the most under-priced opportunity is mid-sized commercial and residential: incentive-driven payback compression is real, but upfront cost and integrator shortages keep these tiers underserved. Vendors offering energy-as-a-service with performance guarantees are best positioned to unlock them. Meanwhile, the South and West regions will outgrow the national average, driven by data-center load growth and dynamic tariffs respectively.
The evidence that would change our conclusion: a sustained slowdown in IRA-linked retrofit incentives, or AMI roll-out stalling, would compress the near-term growth path toward 8–9% and shift the balance back toward hardware refresh cycles.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.4% from 2020-2034 |
| Segmentation |
|
The U.S. EMS market was valued at USD 12.70 billion in 2023 and is projected to grow at roughly 11.4% CAGR through 2030, implying approximately USD 27 billion by the end of the forecast period.
Industrial Energy Management Systems (IEMS) led with 74.5% of 2023 revenue, driven by IoT, big data, and Industry 4.0 adoption. Building EMS is the fastest-advancing sub-segment as smart-building mandates spread.
Federal retrofit incentives under the Inflation Reduction Act, smart-grid and AMI rollouts, corporate net-zero commitments, and dynamic utility tariffs are the primary growth drivers, compressing payback periods and enabling VPP participation.
Honeywell, Johnson Controls, Schneider Electric, and Siemens lead as building-automation incumbents, competing with software specialists like GridPoint and EnergyCAP, and utility-adjacent platforms such as DNV and AutoGrid.
The South leads with roughly 28% share, anchored by Texas and Florida industrial and cooling loads, followed by the West at 24%, where California's dynamic pricing and building codes accelerate adoption.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain: sensor and controller manufacturers, EMS software developers, systems integrators, utility program administrators, and facility-management service providers. Decision-maker designations interviewed include VP of Facilities & Energy, Heads of Sustainability, Technical Directors of Building Operations, and Commercial Procurement Leads. Interviews focused on procurement criteria, payback thresholds, and deployment friction.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Facilities & Energy | 35% |
| Heads of Sustainability | 30% |
| Technical Directors of Building Operations | 20% |
| Commercial Procurement Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Hardware & Sensor Manufacturers | 40% |
| EMS Software & Platform Developers | 30% |
| Systems Integrators & Service Providers | 20% |
| Utility Program Administrators | 10% |
We validated demand against official multilateral and standards databases — UN Comtrade, US ITC trade data, US DOE efficiency standards, EPA emissions inventories, and EIA utility filings — alongside corporate annual filings (10-K, SEC disclosures, investor presentations) and patent databases. Non-profit technical standards and industry associations informed protocol and compliance baselines.
We triangulate a Top-Down macroeconomic and vertical-allocation model against a Bottom-Up manufacturer capacity, pricing, and end-use consumption model. Divergences between the two are reconciled at the segment level to produce a single defensible base-year value and forecast path.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
