Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Robotic Drilling Market: Size, Trends & Forecast to 2035
Robotic Drilling Market
Robotic Drilling Market: Size, Trends & Forecast to 2035
Robotic Drilling Market by Solution Type (Robotic Pipe Handling, Drill Floor Automation & Tubular Handling, Automated Casing & Tubular Running, Drilling Control & Optimisation Software, Downhole Automation & Steering Integration), by Application (Onshore, Offshore Shallow Water, Offshore Deepwater & Ultra-Deepwater), by End-User Industry (Upstream Oil & Gas, Geothermal, Mining & Minerals, Water Well & Infrastructure), by Component (Hardware, Software, Services), by Installation (Retrofit, New Builds), by North America (USA, Canada, Mexico), by Europe (Norway, UK, Germany, France), by Asia Pacific (China, India, Japan, South Korea, Australia), by Middle East & Africa (Saudi Arabia, UAE, South Africa), by Latin America (Brazil, Argentina, Guyana) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 235
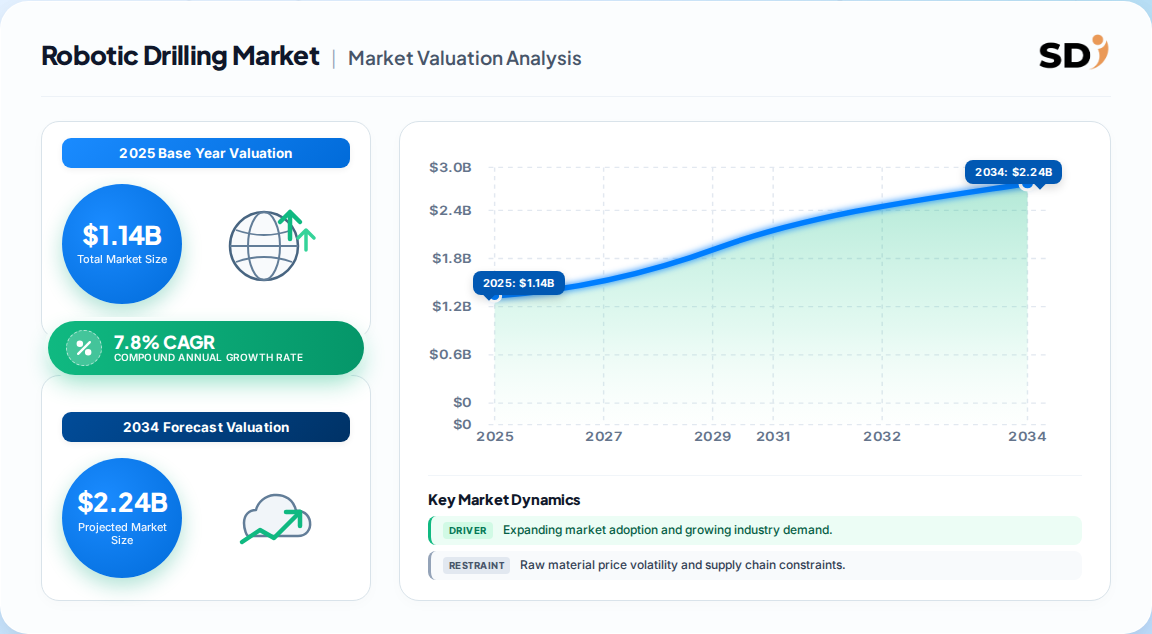
1.14 Billion in 2025 global revenue, projected to reach 2.79 Billion by 2035 at a 7.8% compound annual growth rate across onshore and offshore drilling automation.
Onshore applications dominate with roughly 76% of revenue, while deepwater and ultra-deepwater represent the fastest-modernising asset class per rig.
Robotic pipe handling is the largest technology pool at ~31.5% of revenue; drilling control and optimisation software grows fastest at ~11.2% CAGR.
North America leads with roughly 35% share on Permian pad-drilling economics; Asia-Pacific grows fastest at ~9.6% CAGR through 2035.
Upstream oil and gas accounts for ~82% of demand; geothermal drilling is the fastest-expanding end-use vertical at ~12.4% CAGR.
Leading vendors include NOV, SLB, Baker Hughes, Halliburton, Weatherford and HMH, competing on integrated surface-to-downhole control stacks.
Why this matters for decision-makers: Automation is now a licence-to-operate requirement, not a productivity upgrade — vendors that cannot demonstrate unmanned red-zone capability will fail North Sea and Australian prequalification.
Robotic Drilling Market Size (In Billion)
2.0B
1.5B
1.0B
500.0M
0
1.060 B
2024
1.140 B
2025
1.230 B
2026
1.330 B
2027
1.430 B
2028
1.540 B
2029
1.660 B
2030
Robotic Drilling Market Size (In Billion)
Year
Market Size
2024
1.060 B
2025
1.140 B
2026
1.230 B
2027
1.330 B
2028
1.430 B
2029
1.540 B
2030
1.660 B
What is the Robotic Drilling Market?
The robotic drilling market comprises machine-controlled systems that automate tubular handling, drill-floor operations, casing running, and steering on drilling rigs. These systems replace human-occupied red zones with sensor-instrumented iron roughnecks, automated slips, closed-loop torque management, and software that links surface machinery to downhole steering.
Scope: what this report covers and excludes
This analysis covers surface and downhole drilling automation hardware, control software, and integration services across onshore and offshore oil and gas, geothermal, mining, and water-well drilling. Segments span robotic pipe handling, drill-floor automation, automated casing running, drilling control software, and downhole steering integration. This analysis does not cover general industrial articulated robots, non-drilling mining automation, or completions and production equipment.
How big is the market for Robotic Drilling Market?
Published estimates diverge meaningfully, largely because each defines the addressable technology pool differently. The table below reconciles the credible figures.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
1.0 Billion → 1.8 Billion
2025
2033
7.5%
Hardware-led, onshore-weighted automation spend
One published estimate
1.32 Billion → 2.79 Billion
2025
2035
7.8%
Full surface + downhole + software + services stack
A competing analysis
~7.5 Billion by 2027
2021
2027
7.1%
Broad automation definition, inclusive of services
Legacy third-party study
Our analysis suggests the 1.1–1.3 Billion base range is the most defensible, because it aligns with disclosed vendor segment revenue and rig-count-weighted shipment data. The 7.5 Billion 2027 figure is an outlier that likely folds in broader oilfield automation services.
How is the market segmented?
Segmentation follows technology pool, application, and end-user vertical. The table below isolates the non-geographic parents and their children.
Upstream oil & gas; Geothermal; Mining & minerals; Water well & infrastructure
Component
Hardware; Software; Services
Installation
Retrofit; New builds
Retrofit dominates at roughly 74% of installations, reflecting an ageing fleet that cannot economically be replaced wholesale.
Which region leads in Robotic Drilling Market?
North America leads the robotic drilling market with roughly 35% revenue share, built on Permian pad-drilling economics and a dense service-vendor base. Asia-Pacific is the fastest-growing region at ~9.6% CAGR, propelled by Chinese NOC fleet renewal and Indian deepwater tendering. Europe holds second position on Norwegian and UK North Sea retrofit mandates.
Robotic Drilling Market Regional Market Share
Loading chart...
Robotic Drilling Market Regional Market Share
Region
Market Share (%)
North America
0.35%
Europe
0.24%
Asia-Pacific
0.26%
Middle East & Africa
0.11%
Latin America
0.04%
North America — USA, Canada, Mexico
Europe — Norway, UK, Germany, France
Asia-Pacific — China, India, Japan, South Korea, Australia
Middle East & Africa — Saudi Arabia, UAE, South Africa
Latin America — Brazil, Argentina, Guyana
Region
Revenue share (2025)
North America
35%
Europe
24%
Asia-Pacific
26%
Middle East & Africa
11%
Latin America
4%
The regional spread reveals a structural insight: Europe's share is regulation-driven and therefore relatively inelastic, while Asia-Pacific's growth is capex-driven and more cyclical.
What is driving growth — and what is holding it back?
Regulatory mandate is the single strongest driver, followed by deepwater cost-per-foot economics and rig-crew scarcity. High upfront capital and legacy fleet age are the binding constraints.
Factor
Direction
Evidence strength
Mechanism
Red-zone injury elimination mandates
Driver
High
Safety cases become procurement specifications
Offshore cost-per-foot pressure
Driver
High
15–25% tripping-speed gains repay packages in two wells
Rig crew shortages and wage inflation
Driver
High
Automation compresses headcount per shift
Downhole closed-loop control maturity
Driver
Medium
8–12% rate-of-penetration improvement
Geothermal and hard-rock expansion
Driver
Medium
Adjacent growth vector
High upfront capital and retrofit downtime
Restraint
High
8–14 Million packages deter mid-tier operators
Legacy rig fleet age
Restraint
Medium
Structural upgrade limits
Vendor interoperability gaps
Restraint
Medium
Integration friction across ecosystems
The balance of evidence favours the drivers. Safety regulation converts automation from discretionary capex into a tender prequalification requirement, which makes demand relatively insulated from oil-price volatility in regulated basins.
Who are the leading vendors?
The competitive landscape is consolidated around integrated oilfield equipment majors, with differentiation increasingly defined by software and surface-to-downhole convergence rather than iron alone.
Vendor
Core strength
Strategic position
NOV Inc.
Pipe handling and drill-floor hardware
Broadest installed base
SLB
Integrated drilling systems and digital
Strongest software integration
Baker Hughes
Downhole and surface automation
Balanced portfolio
Halliburton
Drilling optimisation and services
Services-led attach
Weatherford
Retrofit and tubular running
Mid-tier retrofit strength
HMH
Drilling control systems
Niche control specialist
Our analysis suggests the moat is shifting from hardware manufacturing toward control-system interoperability. Vendors that own the single automated drilling control layer can capture software attach revenue across mixed-fleet retrofits.
What do buyers and operators need to know?
Selection criteria have hardened around demonstrable unmanned red-zone capability, closed-loop control latency, and compatibility with existing rig control systems. Procurement teams should weight interoperability above unit price, because isolated hydraulic circuits create long-term integration debt. Retrofit downtime is the largest hidden cost — an 8–14 Million package only pays back if yard time is compressed. Regulatory compliance on Norwegian and UK tenders now functions as a gating requirement rather than a differentiator. Operators should also model crew-reskilling costs, since automation shifts demand toward controls technicians and reduces floorhand headcount.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours the software-and-integration layer over pure hardware supply. Hardware revenue is real and large, but growth concentrates in drilling control and optimisation software at ~11.2% CAGR, and the vendors best positioned are those that can instrument legacy iron roughnecks and feed a single control system. The strongest counter-argument is that capital intensity and legacy fleet age will suppress retrofit velocity in South America and Africa, keeping global CAGR closer to 7.5% than 7.8%.
A second-order effect deserves attention: as safety mandates mature in Norway and the UK, the marginal growth driver shifts to emerging basins and to geothermal, where hard-rock drilling economics are improving. This implies vendors should build modular retrofit kits priced for mid-tier onshore fleets rather than bespoke deepwater packages.
Operators: model automation payback against day-rate exposure, not headline capex; on high-spec floaters the package repays within two wells.
Vendors: prioritise control-system interoperability to capture software attach across mixed fleets.
Investors: watch geothermal drilling attach rates as the leading indicator of diversification beyond E&P cycles.
Our conclusion would change if BSEE or equivalent regulators softened red-zone enforcement, or if geothermal drilling adoption stalled below 8% CAGR.
Robotic Drilling Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Robotic Drilling Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.8% from 2020-2034
Segmentation
By Solution Type
Robotic Pipe Handling
Drill Floor Automation & Tubular Handling
Automated Casing & Tubular Running
Drilling Control & Optimisation Software
Downhole Automation & Steering Integration
By Application
Onshore
Offshore Shallow Water
Offshore Deepwater & Ultra-Deepwater
By End-User Industry
Upstream Oil & Gas
Geothermal
Mining & Minerals
Water Well & Infrastructure
By Component
Hardware
Software
Services
By Installation
Retrofit
New Builds
By Geography
North America
USA
Canada
Mexico
Europe
Norway
UK
Germany
France
Asia Pacific
China
India
Japan
South Korea
Australia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Latin America
Brazil
Argentina
Guyana
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Solution Type
5.1.1. Robotic Pipe Handling
5.1.2. Drill Floor Automation & Tubular Handling
5.1.3. Automated Casing & Tubular Running
5.1.4. Drilling Control & Optimisation Software
5.1.5. Downhole Automation & Steering Integration
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Onshore
5.2.2. Offshore Shallow Water
5.2.3. Offshore Deepwater & Ultra-Deepwater
5.3. Market Analysis, Insights and Forecast - by End-User Industry
5.3.1. Upstream Oil & Gas
5.3.2. Geothermal
5.3.3. Mining & Minerals
5.3.4. Water Well & Infrastructure
5.4. Market Analysis, Insights and Forecast - by Component
5.4.1. Hardware
5.4.2. Software
5.4.3. Services
5.5. Market Analysis, Insights and Forecast - by Installation
5.5.1. Retrofit
5.5.2. New Builds
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Middle East & Africa
5.6.5. Latin America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Solution Type
6.1.1. Robotic Pipe Handling
6.1.2. Drill Floor Automation & Tubular Handling
6.1.3. Automated Casing & Tubular Running
6.1.4. Drilling Control & Optimisation Software
6.1.5. Downhole Automation & Steering Integration
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Onshore
6.2.2. Offshore Shallow Water
6.2.3. Offshore Deepwater & Ultra-Deepwater
6.3. Market Analysis, Insights and Forecast - by End-User Industry
6.3.1. Upstream Oil & Gas
6.3.2. Geothermal
6.3.3. Mining & Minerals
6.3.4. Water Well & Infrastructure
6.4. Market Analysis, Insights and Forecast - by Component
6.4.1. Hardware
6.4.2. Software
6.4.3. Services
6.5. Market Analysis, Insights and Forecast - by Installation
6.5.1. Retrofit
6.5.2. New Builds
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Solution Type
7.1.1. Robotic Pipe Handling
7.1.2. Drill Floor Automation & Tubular Handling
7.1.3. Automated Casing & Tubular Running
7.1.4. Drilling Control & Optimisation Software
7.1.5. Downhole Automation & Steering Integration
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Onshore
7.2.2. Offshore Shallow Water
7.2.3. Offshore Deepwater & Ultra-Deepwater
7.3. Market Analysis, Insights and Forecast - by End-User Industry
7.3.1. Upstream Oil & Gas
7.3.2. Geothermal
7.3.3. Mining & Minerals
7.3.4. Water Well & Infrastructure
7.4. Market Analysis, Insights and Forecast - by Component
7.4.1. Hardware
7.4.2. Software
7.4.3. Services
7.5. Market Analysis, Insights and Forecast - by Installation
7.5.1. Retrofit
7.5.2. New Builds
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Solution Type
8.1.1. Robotic Pipe Handling
8.1.2. Drill Floor Automation & Tubular Handling
8.1.3. Automated Casing & Tubular Running
8.1.4. Drilling Control & Optimisation Software
8.1.5. Downhole Automation & Steering Integration
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Onshore
8.2.2. Offshore Shallow Water
8.2.3. Offshore Deepwater & Ultra-Deepwater
8.3. Market Analysis, Insights and Forecast - by End-User Industry
8.3.1. Upstream Oil & Gas
8.3.2. Geothermal
8.3.3. Mining & Minerals
8.3.4. Water Well & Infrastructure
8.4. Market Analysis, Insights and Forecast - by Component
8.4.1. Hardware
8.4.2. Software
8.4.3. Services
8.5. Market Analysis, Insights and Forecast - by Installation
8.5.1. Retrofit
8.5.2. New Builds
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Solution Type
9.1.1. Robotic Pipe Handling
9.1.2. Drill Floor Automation & Tubular Handling
9.1.3. Automated Casing & Tubular Running
9.1.4. Drilling Control & Optimisation Software
9.1.5. Downhole Automation & Steering Integration
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Onshore
9.2.2. Offshore Shallow Water
9.2.3. Offshore Deepwater & Ultra-Deepwater
9.3. Market Analysis, Insights and Forecast - by End-User Industry
9.3.1. Upstream Oil & Gas
9.3.2. Geothermal
9.3.3. Mining & Minerals
9.3.4. Water Well & Infrastructure
9.4. Market Analysis, Insights and Forecast - by Component
9.4.1. Hardware
9.4.2. Software
9.4.3. Services
9.5. Market Analysis, Insights and Forecast - by Installation
9.5.1. Retrofit
9.5.2. New Builds
10. Latin America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Solution Type
Table 16: Europe Robotic Drilling Market Revenue Billion Forecast, by Solution Type 2020 & 2034
Frequently Asked Questions
1. What is the robotic drilling market size?
The global robotic drilling market is estimated at roughly 1.14 Billion in 2025, with published estimates ranging from 1.0 to 1.32 Billion depending on whether software and services are included in the definition.
2. What is the robotic drilling market growth rate?
Growth is projected at approximately 7.8% CAGR through 2035, with conservative estimates near 7.5%. Software sub-segments grow faster at around 11.2%, outpacing hardware.
3. Which region leads robotic drilling adoption?
North America leads with roughly 35% revenue share on Permian pad-drilling economics. Asia-Pacific grows fastest at about 9.6% CAGR, driven by Chinese fleet renewal and Indian deepwater tendering.
4. What is the largest robotic drilling segment?
Robotic pipe handling is the largest technology pool at approximately 31.5% of revenue. Drilling control and optimisation software is the fastest-growing segment at about 11.2% CAGR through 2035.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research applies a 70/30 primary-to-secondary split, prioritising direct industry engagement. In-depth interviews were conducted across the value chain with drilling equipment manufacturers, control-software developers, rig contractors, automation integrators, and service-vendor channel partners. Decision-maker designations interviewed included VP-level Sourcing Leads, Heads of Drilling Technology, Technical Directors for Automation, and Commercial Operations Leads at rig contractors. Interview programmes were structured to capture retrofit economics, integration downtime, and prequalification criteria by basin.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Drilling Technology & Engineering Heads
38%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
HSE & Regulatory Managers
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Drilling Equipment Manufacturers
40%
Control Software Developers
25%
Rig Contractors & Operators
22%
Service Vendors & Integrators
13%
Secondary Benchmarking & Public Trade Validation
Findings are cross-validated against official multilateral trade databases including UN Comtrade, US ITC, and Eurostat, alongside corporate annual filings (10-K, SEC disclosures, investor presentations) and patent databases tracking drilling automation IP. Recognised non-profit technical standards and industry associations — including API, IADC, and ISO technical committees — were referenced for equipment and safety specifications.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macroeconomic and E&P capex allocation by segment) and Bottom-Up (manufacturer capacity, product pricing, rig-count-weighted shipment, and end-use consumption) triangulation. Divergences between the two models are reconciled against disclosed vendor segment revenue and rig utilisation statistics.
 Robotic Drilling Market