 Flexible Battery Market
 Size, Trends & Forecast 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 180

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Flexible Battery Market
Sandeep Singh
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 267.0 M |
| 2026 | 281.0 M |
| 2027 | 339.0 M |
| 2028 | 409.0 M |
| 2029 | 494.0 M |
| 2030 | 596.0 M |
| 2031 | 719.0 M |

The flexible battery market covers bendable, thin and lightweight electrochemical power sources — primary and rechargeable — manufactured via thin-film deposition, printed electronics or laminar lithium-polymer construction, and sold into wearables, IoT sensors, medical patches, smart packaging and flexible consumer electronics. It is a component market measured at manufacturer-level revenue.
The scope is global, covering flexible batteries across type (primary/secondary), technology (thin-film, printed, laminar lithium-polymer, flexible lithium-ion, zinc-carbon), capacity bands (below 10 mAh, 10–100 mAh, above 100 mAh), voltage tiers and applications (wearables, consumer electronics, healthcare, smart packaging, logistics, IoT). Both manufacturer revenue and unit demand are modeled.
This analysis does not cover conventional rigid lithium-ion cell manufacturing, grid-scale stationary storage, EV traction battery packs, or solid-state battery R&D programs that are not commercialized in flexible form factors.
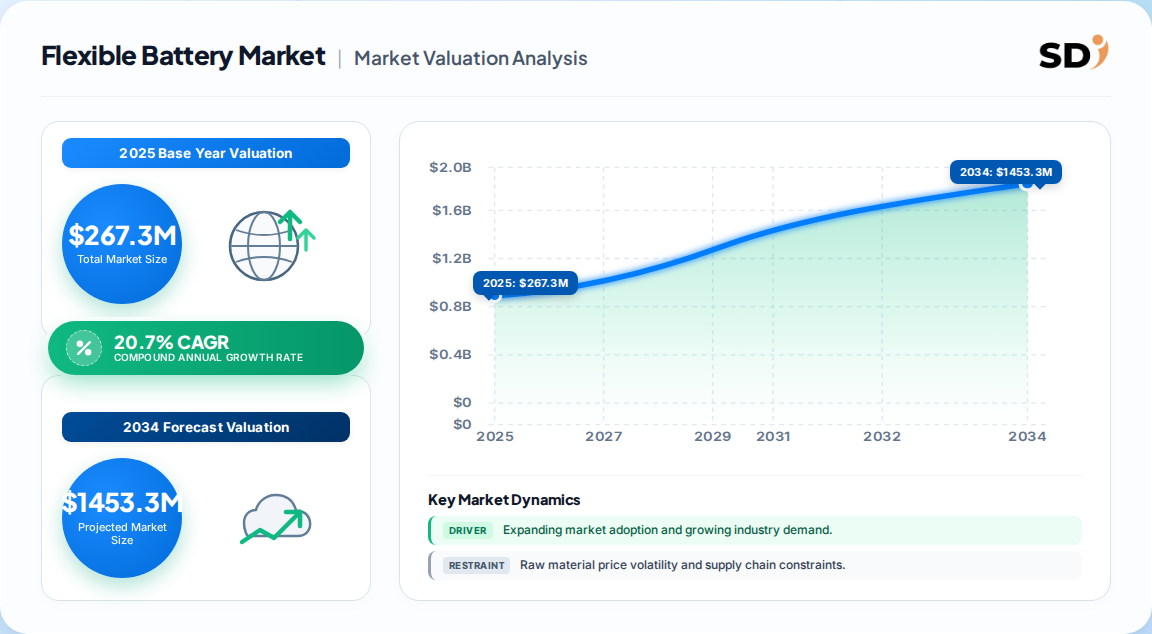
Published estimates diverge materially because base years and horizons differ, but the credible consensus places the global market at USD 267.3 Million in 2025, growing to USD 1,049.8 Million by 2033 at 20.7% CAGR. The table below reconciles the three benchmark sets against our synthesis.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 267.3 Million (2025) → USD 1,049.8 Million (2033) | 2025 | 2033 | 20.7% | Global flexible battery revenue, all technologies | One published industry estimate |
| USD 112.99 Million (2025) → USD 1,050.48 Million (2035) | 2025 | 2035 | 24.89% | Global flexible battery revenue, product-type segmentation | A competing analysis |
| USD 195.91 Million (2023) → USD 1,452.77 Million (2032) | 2023 | 2032 | 24.95% | Global flexible battery revenue, technology-first segmentation | A third published estimate |
| USD 267.3 Million (2025) → USD 1,049.8 Million (2033) | 2025 | 2033 | 20.7% | Consensus synthesis used throughout this report | Our triangulated consensus |
The 2025 base spreads from USD 113 Million to USD 267 Million — a 2.4x gap that implies divergent treatment of printed and laminar lithium-polymer cells. Our analysis suggests the higher base is more defensible because it captures flexible lithium-polymer shipments embedded inside wearable OEM supply chains, which narrower definitions omit.
The horizon endpoints converge tightly near USD 1.05 Billion regardless of path, which is the strongest signal in the dataset: forecasters disagree on today's size far more than on tomorrow's destination. For buyers, this means vendor revenue pools will roughly quadruple by the early 2030s, and the risk is timing, not direction.
Segmentation follows four non-geographic parents — type, technology, capacity and application — with voltage and chargeability as secondary cuts used in the underlying model. Thin-film leads technology at 44.3%, while secondary rechargeable chemistry commands 75.7% of revenue.
| Parent | Children | 2025 lead |
|---|---|---|
| By Type | Primary (single-use), Secondary (rechargeable) | Secondary, 75.7% |
| By Technology | Thin-film, Printed, Laminar lithium-polymer, Flexible lithium-ion, Zinc-carbon | Thin-film, 44.3% |
| By Capacity | Below 10 mAh, 10–100 mAh, Above 100 mAh | 10–100 mAh, 46.6% |
| By Application | Consumer electronics, Healthcare, Smart packaging, Transportation & logistics, IoT & others | Consumer electronics, 43% |
| By Voltage | 1.5V, 1.5–3V, Above 3V | 1.5–3V, 52% |
Two cross-segment insights matter. First, primary batteries are the fastest-growing type (21.4% CAGR) despite holding a minority share, because single-use medical patches and smart labels scale faster than rechargeable wearables. Second, zinc-carbon is the fastest-growing chemistry at 29.8% CAGR from a small base — a cost-driven substitution signal worth monitoring.
North America leads with 34.4% of 2025 revenue, anchored by US medical-wearable and defense-electronics design wins, while Asia Pacific is the fastest-growing region as cell production localizes in China, South Korea and Japan around consumer-electronics and battery supply chains.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.22% |
| Asia-Pacific | 0.29% |
| South America | 0.05% |
| Middle East & Africa | 0.05% |
| Region | Share (2025) | Growth posture |
|---|---|---|
| North America | 34.4% | Mature, high-value medical and defense design-ins |
| Asia Pacific | ~29% | Fastest CAGR; cell and materials localization |
| Europe | ~22% | Regulation-led; recyclability and e-waste compliance |
| Latin America | ~5% | Early-stage, imported supply |
| Middle East & Africa | ~5% | Nascent, logistics and smart-label pilots |
The North America–Asia Pacific split is the central tension in this market. Our analysis suggests North America's share lead reflects design ownership, not manufacturing — most cells are produced in Asia — so value capture is drifting toward whoever converts design wins into qualified, high-volume production. This divergence implies US and European OEMs will face rising single-source risk through 2028 unless second-source qualification accelerates.
Wearable and IoT proliferation is the dominant driver, supported by thin-film and printed-electronics advances that enable thinner, bendable form factors; the binding constraint is low energy density and high manufacturing cost, which caps use in high-power devices.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Wearable electronics demand | Driver | High | Bendable power for skin-conformal devices |
| IoT sensor deployment | Driver | High | Small, embedded, maintenance-free power |
| Thin-film and printed advances | Driver | High | Thinner cells, lower integration cost |
| Smart packaging and RFID | Opportunity | Medium | Disposable printed cells at high volume |
| High manufacturing cost | Restraint | High | Thin-film deposition capex and yield loss |
| Low energy density | Restraint | High | Excludes smartphones, EVs, long-duty devices |
The balance favors growth: three high-evidence drivers outweigh two high-evidence restraints because the restraints are capacity-bounded, not demand-bounded. Our analysis suggests the cost barrier erodes fastest in printed zinc-carbon, where per-unit economics suit smart labels. The energy-density ceiling, by contrast, is structural and will not lift within the forecast horizon — so strategy should target low-power niches rather than wait for parity with rigid lithium-ion.
Samsung SDI, Panasonic and LG Chem anchor the thin-film and flexible lithium-ion tier, while BrightVolt, Blue Spark Technologies, Enfucell and Cymbet compete in printed and medical-grade formats; differentiation rests on encapsulation durability, thin-film yield and design-in qualification.
| Company | Technology focus | Strategic position |
|---|---|---|
| Samsung SDI | Thin-film, flexible lithium-ion | Scale and consumer-electronics pull-through |
| Panasonic | Thin-film, laminar lithium-polymer | Reliability brand, IoT focus |
| LG Chem | Flexible lithium-ion | Materials depth, broad portfolio |
| BrightVolt | Thin-film, medical wearables | Medical qualification moat |
| Blue Spark Technologies | Printed primary cells | Smart packaging and medical patches |
| Enfucell | Printed thin-film | Cost-led printed volume |
| Cymbet | Solid-state thin-film | High-reliability niches |
Competitive moats are narrow but durable. Qualification cycles in medical and automotive-adjacent applications run 12–24 months, creating switching costs that protect incumbents far more than patent portfolios do. Our analysis suggests the most defensible position belongs to vendors with both medical-grade encapsulation IP and a printed low-cost line — a rare combination that lets them serve high-margin and high-volume segments from one materials base.
Selection should prioritize proven cycle life at the target bend radius, encapsulation reliability under humidity cycling, and a documented second-source path — not headline capacity claims. Procurement risk concentrates in single-source thin-film supply and long qualification lead times.
Switching costs are real but asymmetric. Once a flexible cell is designed into a wearable or patch, requalification can cost six figures and 12–24 months, so buyers should negotiate capacity commitments and price ladders before design freeze rather than after.
Regulatory compliance is tightening. EU battery and e-waste rules increasingly favor recyclable and biodegradable chemistries, while medical-device patch formats require biocompatibility and sterilization validation. Our analysis suggests compliance, not price, will become the primary disqualifier in European tenders by 2028 — operators should build recyclability and material traceability into specifications now.
The balance of evidence favors the higher base case: the market is roughly USD 267 Million today with a credible path to USD 1.05 Billion by 2033, and horizon-end forecasts converge even where base years diverge. The strongest counter-argument is that low energy density permanently caps the addressable pool to niche low-power devices — a real constraint, but one that still supports a four-fold revenue expansion as wearable and medical volumes scale.
Our analysis suggests value will migrate from cell makers to qualified design partners as medical and smart-packaging volumes build. Vendors that treat encapsulation and qualification as core IP, rather than commodities, will defend margin; those competing purely on price per mAh will face compression as printed zinc-carbon scales.
Actionable strategy for operators and investors:
What would change our conclusion: a breakthrough raising flexible-cell energy density toward rigid lithium-ion parity, or a sharp fall in thin-film deposition capex, would expand the addressable pool beyond low-power niches and pull forward the forecast materially. Until then, the data supports a niche-scaling, qualification-led strategy.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 20.7% from 2020-2034 |
| Segmentation |
|
The global flexible battery market is estimated at USD 280.7 Million in 2026, up from USD 267.3 Million in 2025, on track to reach USD 1,049.8 Million by 2033 at a 20.7% CAGR across all technologies and applications.
The consensus CAGR is 20.7% for 2026–2033. Some published estimates run as high as 24.9%, reflecting different base years and inclusion of printed and laminar lithium-polymer cells, but all converge near USD 1.05 Billion by the early 2030s.
North America holds the largest revenue share at 34.4% in 2025, driven by US medical-wearable and consumer-electronics design wins. Asia Pacific is the fastest-growing region as cell production localizes around Chinese, Japanese and South Korean supply chains.
Consumer electronics leads with 43% of 2025 revenue, followed by healthcare wearables, smart packaging, transportation and logistics, and IoT sensors. Smart packaging is the fastest-growing application, powered by printed batteries in smart labels and RFID tags.
Leading companies include Samsung SDI, Panasonic, LG Chem, BrightVolt, Blue Spark Technologies, Enfucell and Cymbet. Differentiation rests on thin-film deposition yield, encapsulation durability and 12–24 month design-in qualification cycles rather than raw capacity.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, with 70% of evidence drawn from structured fieldwork. We conducted in-depth interviews across the value chain, including raw material and specialty substrate suppliers, thin-film and printed-cell producers, contract manufacturing and encapsulation specialists, and global distributors serving wearable and medical OEMs. Interviewees were selected at decision-maker level: VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads. These interviews established qualification timelines, yield benchmarks and capacity constraints that public filings do not disclose.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Heads of R&D & Technical Directors | 40% |
| VP of Sourcing & Procurement Directors | 35% |
| Commercial Operations Leads | 15% |
| Quality & Regulatory Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Thin-Film & Printed Cell Producers | 40% |
| Raw Material & Substrate Suppliers | 25% |
| Contract Manufacturing & Encapsulation | 20% |
| Global Distributors & OEM Integrators | 15% |
Secondary validation draws on official multilateral trade and standards databases — UN Comtrade, WTO tariff schedules, US ITC trade data and Eurostat — alongside corporate annual filings (10-K, SEC submissions, investor presentations), patent databases tracking thin-film and encapsulation IP, and recognized technical standards bodies and industry associations. No third-party market-research publications are used as source inputs in the model.
We run top-down and bottom-up models simultaneously. The top-down path allocates macroeconomic electronics output to flexible form factors by application and region. The bottom-up path models manufacturer capacity, product pricing and end-use consumption by capacity band and voltage tier. Divergences are reconciled at segment level before the base-year value is fixed.
| Dimension | Analytical Scope | Methodology Applied | Validation Level | | Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High | | Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High | | Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High | | Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |