 Wind Turbine Rotor Blade Market
 Size & Forecast
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 272

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Wind Turbine Rotor Blade Market
Sandeep Singh
Research Analyst
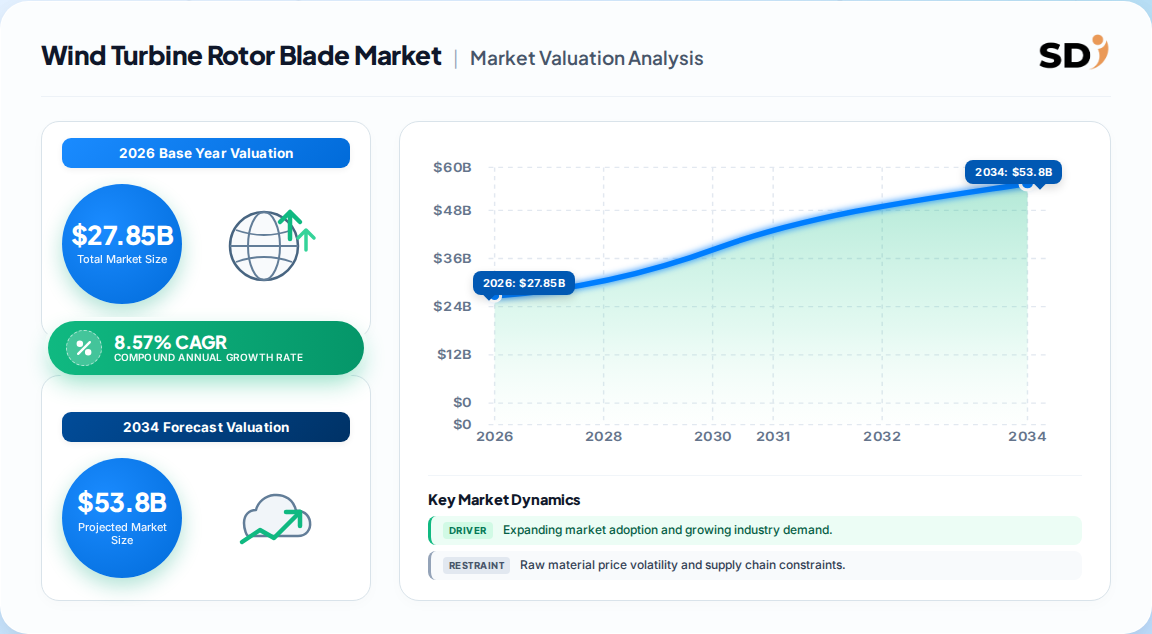
| Year | Market Size |
|---|---|
| 2025 | 25.54 B |
| 2026 | 27.85 B |
| 2027 | 30.24 B |
| 2028 | 32.83 B |
| 2029 | 35.64 B |
| 2030 | 38.70 B |
| 2031 | 42.02 B |

The wind turbine rotor blade market encompasses the design, composite material supply, manufacturing, and aftermarket servicing of aerodynamic blades that capture wind energy and convert it into rotational torque for electricity generation. It spans onshore and offshore applications, glass and carbon fiber architectures, blade lengths from sub-45 m to over 75 m, and processes from hand lay-up to advanced vacuum infusion and pre-preg.
This report covers the global market for wind turbine rotor blades, segmented by location of deployment (onshore, offshore), blade material (glass fiber, carbon fiber, hybrid composites, others), blade length (below 45 m, 46–60 m, 61–75 m, above 75 m), manufacturing process (hand lay-up, vacuum infusion, pre-preg, others), and geography. This analysis does not cover adjacent markets such as wind turbine nacelles, towers, gearboxes, generators, or balance-of-plant electrical infrastructure.
Lead-in: Published estimates for the wind turbine rotor blade market vary by a factor of nearly four in absolute size, but converge on a high-single-digit growth trajectory. The divergence reflects definitional scope, not disagreement on direction.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 27.85 Billion | 2026 | 2035 | 8.57% | Rotor blades only, global revenue | One published estimate (Precedence Research) |
| USD 28.33 Billion | 2026 | 2036 | 9.6% | Rotor blades, global revenue | A competing analysis |
| USD 55.49 Billion | 2026 | 2031 | 9.62% | Broader blade systems, global | A competing analysis |
| USD 103.5 Billion | 2025 | 2035 | 8.4% | Whole wind turbine blade market, inclusive of value chain | A competing analysis |
Our analysis suggests the USD 27.85–28.33 billion base is the most defensible for a pure-play rotor blade revenue figure, as it aligns with the installed base of major independent blade manufacturers. The USD 103.5 billion figure likely captures a wider blade value chain inclusive of aftermarket and services, while the USD 55.49 billion estimate appears to include blade-adjacent structural components. Buyers should anchor on the ~8.5–9.6% CAGR consensus regardless of base-year definition.
Lead-in: The market segments along four non-geographic axes — deployment location, material, blade length and manufacturing process — each with distinct growth and cost dynamics.
| Parent Segment | Children |
|---|---|
| By Location of Deployment | Onshore, Offshore |
| By Blade Material | Glass Fiber, Carbon Fiber, Hybrid Composites, Others |
| By Blade Length | Below 45 m, 46–60 m, 61–75 m, Above 75 m |
| By Manufacturing Process | Hand Lay-Up, Vacuum Infusion, Pre-Preg, Others |
Onshore holds over 82% of demand, yet offshore blades are expanding at roughly 29.9% CAGR through 2031 — the single largest growth lever in the sector. Carbon fiber dominates materials (~47.5–79.2% depending on definition) as blade length rises; hybrid composites are the fastest-growing material class. Blades above 75 m are advancing at ~12.85% CAGR, and vacuum infusion accounts for ~59% of production while pre-preg lines accelerate for offshore tolerance requirements.
Lead-in: Asia-Pacific leads the global wind turbine rotor blade market with roughly 47% revenue share, and is also the fastest-growing region, reinforcing its structural advantage in composite manufacturing cost and scale.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.48% |
| Europe | 0.25% |
| North America | 0.17% |
| South America | 0.05% |
| Middle East & Africa | 0.05% |
China's 31.4 GW offshore installed capacity by 2024 and its pivot to 15 MW machines requiring 100 m+ blades underpin APAC's lead. Europe's REPowerEU repowering wave and the US IRA production tax credit are the key demand catalysts in higher-cost regions. The Middle East & Africa is the fastest-growing sub-region at ~28.15% CAGR from a small base, signaling long-term geographic diversification.
Lead-in: The balance of drivers clearly outweighs restraints, supporting high-single-digit to low-double-digit CAGR through the early 2030s.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rapid scale-up of >5 MW turbines in China | Driver | High | +1.5% CAGR; ultra-large composite structures |
| US IRA production tax credits (Section 45X) | Driver | High | +1.2% CAGR; domestic blade output |
| EU REPowerEU repowering of post-2010 fleets | Driver | Medium | +0.8% CAGR; blade-only upgrades |
| OEM demand for 70 m+ modular blades | Driver | Medium | +0.6% CAGR; transport bottleneck relief |
| Brazil FINAME green financing | Driver | Medium | +0.5% CAGR; local blade capacity |
| Floating-offshore serial 100 m blade orders | Driver | Low-Medium | +0.4% CAGR; long-term volume |
| Chronic carbon-fiber supply tightness | Restraint | High | -0.9% CAGR; input-cost inflation |
| Higher LCOE penalty for sub-2 MW turbines | Restraint | Medium | -0.7% CAGR; legacy fleet attrition |
| Logistics restrictions on ultra-long blades | Restraint | Medium | Road-haul and bridge clearance limits |
The net driver impact is positive by roughly 4–5 percentage points, consistent with the consensus ~8.5–9.6% CAGR. Our analysis suggests carbon-fiber tightness is the most underpriced risk: it disproportionately hits offshore programs where carbon content is highest, potentially delaying 2027–2029 installations and favoring vertically integrated vendors.
Lead-in: The market is moderately concentrated, with the top five players — Sinoma, LM Wind Power, TPI Composites, Vestas and Siemens Gamesa — holding roughly 35–43% of global share.
| Company | HQ / Blades | Strategic Position | Moat |
|---|---|---|---|
| Sinoma Wind Power Blade | China | Volume leader, >10% share | Cost leadership, domestic scale |
| LM Wind Power (GE Vernova) | Denmark / US | Technology and offshore leader | Aerodynamic IP, OEM integration |
| TPI Composites | USA | Largest independent blade maker | 100,000+ blade milestone, US footprint |
| Vestas Wind Systems | Denmark | Captive OEM supply | Vertical integration, service network |
| Siemens Gamesa | Spain / Germany | Offshore specialist | Recyclable Blade, integrated platform |
| Nordex SE | Germany | Onshore focus | European share, modular designs |
| Mingyang Smart Energy | China | Offshore innovator | 15 MW+ platforms, MYSE series |
| MFG Wind | Brazil | Regional leader | LatAm cost and local-content edge |
Differentiation hinges on material engineering, logistics innovation and aftermarket services. TPI's independent model makes it a strategic supplier to multiple OEMs, while Sinoma's cost position compresses margins in price-sensitive tenders. Our analysis suggests vertical integration and recyclable material portfolios will be the decisive moats post-2030.
Blade selection is now a decade-long capital commitment, and procurement criteria must shift from unit cost toward total cost of ownership. Buyers should prioritize suppliers with demonstrated >100 m blade capability, certified lightning protection, and embedded structural health monitoring, as these reduce unplanned downtime and lifetime maintenance expense. Logistics is a mission-critical risk: modular segmented designs such as Nabrajoint can trim USD 100,000–150,000 per load in transport costs, but require hub-interface validation. Switching costs are high once blade tooling is committed, so early supplier qualification is essential. Regulatory compliance with IEC 61400 standards and evolving recyclability mandates in the EU must be built into contract terms, not treated as post-award compliance.
The balance of evidence favors a structurally bullish, high-single-digit growth trajectory for the wind turbine rotor blade market through the mid-2030s, with offshore and carbon-fiber architectures as the premium growth engines. The strongest counter-argument is demand cyclicality: policy shifts in the US and Europe, plus competitive pressure from solar and gas, could compress the forecast toward the low end of the 8–9% range. Still, the installed-base effect and repowering pipeline provide a demand floor absent in earlier cycles.
Our analysis suggests the market is entering a materials-constrained, scale-driven phase where supply assurance and logistics innovation matter more than raw capacity. Vendors that have locked carbon-fiber supply, invested in modular tooling and offer lifetime service contracts will capture disproportionate margin. Buyers should expect consolidation among sub-scale blade makers and rising content thresholds in North America and Europe.
What would change this conclusion: a sustained >15% year-over-year decline in Chinese offshore installations, or a carbon-fiber supply breakthrough that collapses input costs, would materially alter the forecast mix and favor glass-fiber-heavy incumbents.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.57% from 2020-2034 |
| Segmentation |
|
The global wind turbine rotor blade market is valued at approximately USD 27.85 billion in 2026 and is projected to reach USD 59.19 billion by 2035, expanding at an 8.57% CAGR over the forecast period.
Asia-Pacific leads with roughly 47% of global revenue, driven by China's offshore build-out and manufacturing cost advantage. Europe and North America follow at approximately 25% and 17% respectively.
Offshore deployment is the fastest-growing location segment, expanding at roughly 29.9% CAGR through 2031, while blades above 75 m are the fastest-growing length category at 12.85% CAGR.
Key players include Sinoma Wind Power Blade, LM Wind Power (GE Vernova), TPI Composites, Vestas, Siemens Gamesa, Nordex and Mingyang Smart Energy. The top five collectively hold roughly 43% of global share.
Glass fiber and carbon fiber dominate, with carbon fiber preferred for large offshore blades due to its stiffness-to-weight ratio. Hybrid composites are the fastest-growing material class at over 10% CAGR.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split, with in-depth interviews conducted across the blade value chain: glass and carbon fiber suppliers, specialized blade producers, contract composite formulators, and global distribution and logistics partners. Interviewees include VP-level Sourcing, Heads of Blade R&D, Technical Directors, and Commercial Operations Leads, ensuring both technical and commercial perspectives are captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Directors | 35% |
| Blade R&D and Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Certification Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Composite Material Suppliers | 40% |
| Blade Manufacturers | 35% |
| Logistics & Installation Partners | 15% |
| Aftermarket Service Providers | 10% |
We triangulate against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC submissions, investor presentations), patent databases, and recognized standards bodies including IEC 61400 and DNV. These sources validate demand volumes, pricing, and capacity claims independent of any single commercial estimate.
Simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) modeling is applied. Cross-validation reduces variance between competing published base-year estimates and confirms the ~8.5–9.6% CAGR consensus.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
