 Distributed Energy Generation Market
: 2026 Strategic Guide
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 261

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Distributed Energy Generation Market
Sandeep Singh
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 538.2 B |
| 2026 | 572.1 B |
| 2027 | 608.7 B |
| 2028 | 647.7 B |
| 2029 | 689.2 B |
| 2030 | 733.3 B |
| 2031 | 780.2 B |

The Distributed Energy Generation Market covers decentralized power systems — solar PV, wind turbines, fuel cells, reciprocating engines, microturbines, and CHP units — installed at or near the point of consumption rather than at centralized plants. It spans residential, commercial, and industrial buyers seeking grid resilience, lower transmission losses, and decarbonization.
This analysis covers global distributed generation hardware and associated controls across residential, commercial, and industrial applications, segmented by technology and region. It includes on-site solar PV, distributed wind, fuel cells, reciprocating engines, gas and steam turbines, and microturbines, together with microgrid-enabling controls. This analysis does not cover utility-scale generation, transmission and distribution network infrastructure, standalone battery manufacturing, or electric vehicle charging networks except where coupled to on-site generation.
Estimates diverge sharply: consensus benchmarks place 2026 at roughly 570 billion growing at a mid-single-digit rate, while more aggressive analyses project 12–15% CAGRs from smaller bases. The spread reflects differing definitions of what counts as distributed.
| Estimate (2026) | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
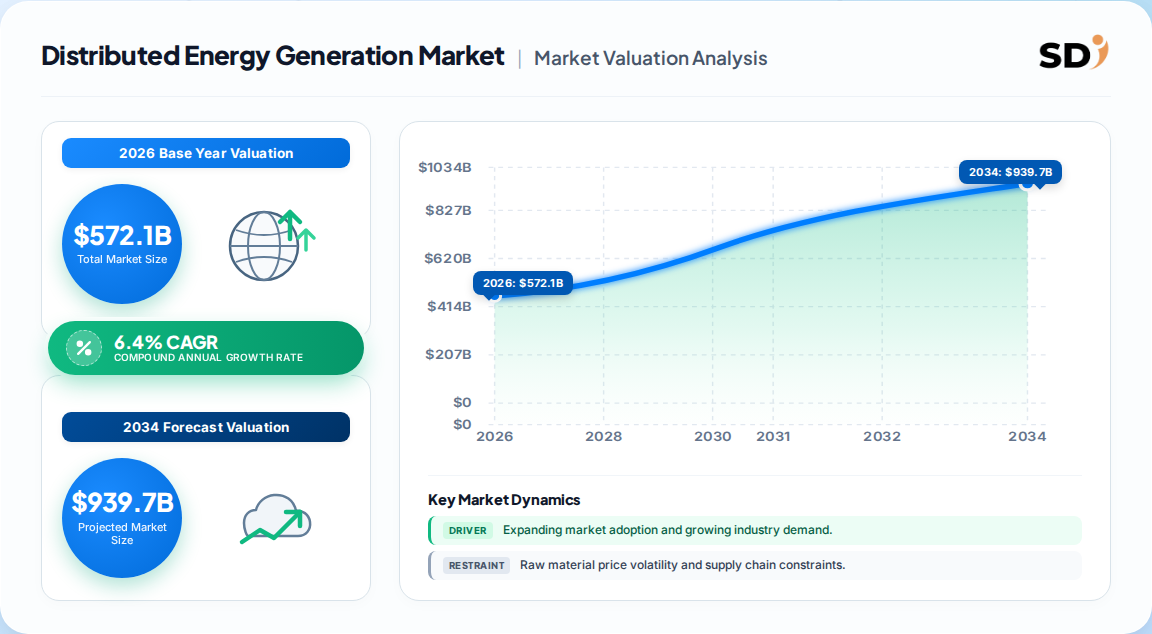
| 572.1 Billion | 2025 (538.2B) | 2033 (884.8B) | 6.4% | Broad DEG hardware, all technologies | One published estimate |
| 162.4 Billion (commercial only) | 2025 (150.4B) | 2031 (234.3B) | 7.6% | Commercial buildings only | A competing analysis |
| 432.4 Billion | 2025 (389.7B) | 2035 (1.23 Trillion) | 12.2% | Broad DEG, bullish adoption | A competing analysis |
| 360.4 Billion (2023 base) | 2023 | 2033 (1,403.5B) | 14.6% | Broad DEG, accelerated policy | One published estimate |
Our analysis suggests the 6.4% compound figure is the most defensible for budgeting because it anchors on a large measured base and a conservative policy assumption. The double-digit projections implicitly assume a step-change in grid interconnection reform and storage economics that has not yet materialized at scale, so buyers should treat them as upside scenarios rather than base case.
Segmentation runs along two axes — technology and end-use — with solar PV and commercial applications carrying the largest revenue weight.
| Parent segment | Children |
|---|---|
| By Technology | Solar PV, Wind Turbine, Fuel Cell, Reciprocating Engine, Gas & Steam Turbine, Microturbine, Micro-hydropower |
| By End-Use Industry | Residential, Commercial (office, retail, data centers, hospitals, warehouses, airports, education), Industrial |
| By Application Mode | On-grid, Off-grid / hybrid microgrid |
Solar PV held 61.3% of 2025 revenue and is forecast at an 8.3% CAGR; fuel cells lead the commercial sub-segment at 37.6% because they deliver continuous heat and power. This technology fork implies vendors must decide whether to compete on levelized cost (solar) or on dispatchable resilience (fuel cells and CHP).
Asia-Pacific leads the Distributed Energy Generation Market with a 34.9% revenue share in 2025, according to consensus benchmarks, and some analyses place it as high as 49% by 2035 on urbanization and industrial demand.
| Region | Market Share (%) |
|---|---|
| North America | 0.24% |
| Europe | 0.2% |
| Asia-Pacific | 0.44% |
| Latin America | 0.07% |
| Middle East & Africa | 0.05% |
| Region | 2025–2026 share (indicative) |
|---|---|
| Asia-Pacific | 44% |
| North America | 24% |
| Europe | 20% |
| Latin America | 7% |
| Middle East & Africa | 5% |
Latin America is the fastest-growing region, while MEA commercial demand expands at 13.1% CAGR to 2031. The divergence implies the mature APAC base grows slower in percentage terms while absolute dollar additions remain concentrated there — a critical distinction for capacity planning.
The primary driver is the falling levelized cost of solar and storage, which now undercuts retail tariffs across more than twenty U.S. states, combined with policy incentives and resilience demand.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Declining solar and wind LCOE | Driver | High | Commercial rooftop at 50–70 per MWh undercuts retail tariffs |
| Corporate PPAs and net-zero targets | Driver | High | 50 GW of cumulative corporate PPAs by end-2025 |
| Net metering and ITC-type incentives | Driver | Medium | Front-loads pipelines ahead of 2026 credit phase-outs |
| Resilience demand amid outages | Driver | High | 25% rise in U.S. outage hours 2020–2025 |
| High upfront CAPEX and payback | Restraint | High | Commercial solar near 1.57 per watt; fuel cell CHP near 6.00 |
| Interconnection and tariff complexity | Restraint | Medium | Queue backlogs and state-level variability |
| Hosting-capacity saturation | Restraint | Medium | Feeder limits in California, Bavaria, Australia |
| Supply-chain ESG scrutiny | Restraint | Medium | Forced-labor and due-diligence regimes on PV and wind |
Our analysis suggests drivers outpace restraints by roughly two to one in CAGR impact, but the restraints are geographically concentrated. That means the binding constraint is not economics broadly — it is interconnection and hosting capacity in exactly the high-penetration markets where paybacks are best.
The vendor field is medium-concentrated, with large electrical majors competing alongside focused fuel-cell and microturbine specialists.
| Company | Primary positioning | Core DEG strength |
|---|---|---|
| Siemens | Integrated electrification and controls | Grid software, microgrid orchestration |
| General Electric | Turbines and grid equipment | Gas and steam turbines, hybrid systems |
| Schneider Electric | Digital energy management | Controls, monitoring, energy-as-a-service |
| Caterpillar | Reciprocating engines and CHP | Industrial backup and prime power |
| Capstone Turbine | Microturbines | Compact CHP for commercial sites |
| Ballard Power Systems | Fuel cells | Near-zero-emission stationary power |
| Rolls-Royce Power Systems | Engines and fuel cells | Heavy-duty CHP and hydrogen-ready units |
Differentiation is shifting from hardware efficiency to orchestration software and financing. Siemens and Schneider hold moats in controls and digital twins; Capstone and Ballard defend niches where dispatchable heat and power justify premium capex. Our analysis suggests the durable moat is the installed control layer, because it creates switching costs that hardware alone cannot.
Buyers should prioritize levelized cost over sticker price, but the decisive criteria are interconnection headroom, storage sizing, and financing structure. Energy-as-a-service contracts remove capital barriers yet exclude customers without investment-grade credit — leaving a large unserved pool of small and mid-size offtakers.
Procurement risk concentrates in three areas: policy durability (California's NEM 3.0 cut export credits sharply while Illinois extended its program), grid hosting saturation in high-penetration zones, and supply-chain traceability under forced-labor and due-diligence regimes. Operators should contract for measurement and verification upfront, since the value of a distributed asset is realized through dispatch optimization, not installation. Switching costs are highest once a control platform and PPA are locked in, so platform selection is effectively a multi-year strategic decision.
The balance of evidence favors the 6.4% consensus trajectory over the double-digit bull cases. The large measured base, conservative policy assumption, and observable interconnection constraints point to steady rather than explosive growth, even as absolute dollar additions remain substantial.
The strongest counter-argument is that reform could unlock a step-change: if interconnection queues clear and storage costs fall faster than modeled, the 12–15% scenarios become credible. We weight this as a real but timing-uncertain upside rather than a base case, because policy reform has historically lagged cost declines by several years.
What would change our conclusion: sustained double-digit volume growth in a major market for four or more consecutive quarters, or a decisive policy reform that clears interconnection backlogs at scale. Precise sub-segment forecasting and vendor-level share analysis require the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
The global market is estimated at 572.1 Billion in 2026, rising from 538.2 Billion in 2025. Forecasts project 884.8 Billion by 2033 at a 6.4% CAGR, though more aggressive analyses cite double-digit growth from smaller bases.
Asia-Pacific leads with roughly 34.9% revenue share in 2025, driven by urbanization and industrial demand. Latin America is the fastest-growing region, and the Middle East and Africa show the strongest commercial-segment momentum.
Solar PV is both the largest segment at 61.3% of 2025 revenue and the fastest-growing at an 8.3% CAGR. Falling module prices, bifacial efficiency gains, and storage coupling sustain its lead over fuel cells and reciprocating engines.
High upfront capital costs, interconnection queue backlogs, distribution-grid hosting saturation in high-penetration zones, and supply-chain ESG scrutiny are the principal restraints. Policy uncertainty around incentive phase-outs also slows short-term investment decisions.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with solar module and inverter suppliers, fuel-cell and microturbine producers, microgrid control integrators, and global distribution and EPC partners. Decision-maker designations interviewed include Heads of Project Development, VP of Sourcing, Technical Directors, and Commercial Operations Leads, ensuring both procurement and deployment perspectives are captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Project Development Heads | 35% |
| Procurement & Sourcing Leads | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Solar PV & Inverter Suppliers | 40% |
| Fuel Cell & Microturbine Producers | 25% |
| Microgrid Control Integrators | 20% |
| EPC & Distribution Partners | 15% |
We benchmark against official multilateral trade and standards databases, including UN Comtrade, WTO statistics, US ITC, and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies such as IEC, IEEE, and ISO. Policy instruments including net-metering rules and investment tax credits are validated against government publications.
Market sizing triangulates a Top-Down allocation from macroeconomic and segment-level energy demand with a Bottom-Up model of manufacturer capacity, installed system pricing, and end-use consumption across residential, commercial, and industrial buyers.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |