 Material Handling Equipment Biomass Power Plant Market
 2025
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 238

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Material Handling Equipment Biomass Power Plant Market
Sandeep Singh
Research Analyst
| Year | Market Size |
|---|---|
| 2024 | 807.0 M |
| 2025 | 859.0 M |
| 2026 | 914.0 M |
| 2027 | 972.0 M |
| 2028 | 1.030 B |
| 2029 | 1.100 B |
| 2030 | 1.170 B |

The material handling equipment biomass power plant market covers the systems used to receive, store, convey, and feed biomass feedstock — wood chips, pellets, agricultural residues, and municipal solid waste — into biomass power boilers. It includes industrial trucks, cranes, continuous conveyors, and racking, sold as OEM equipment and integrated into plant EPC contracts.
This analysis covers equipment sold for biomass power plant feedstock handling across product and application segments in North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. It includes industrial trucks, racking and storage, cranes and lifting, and continuous handling equipment across wood chip, MSW, pellet, and agricultural residue applications.
This analysis does not cover biomass conversion technology (gasification, pyrolysis, anaerobic digestion reactors), boiler and turbine supply, fuel supply and trading, or waste-to-energy plants that do not combust biomass feedstock.
The market is estimated at roughly 850–859 Million in 2025, with forecasts converging on a mid-single-digit CAGR over the 2025–2030 horizon. Two published estimates bracket the base year within a 1% band, which strengthens confidence in the central figure.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 851.3 Million | 2023 | 2030 | 6.6% | Biomass power plant material handling, global | One published estimate |
| 858.8 Million | 2023 | 2030 | 6.4% | Biomass power plant material handling, global | A competing analysis |
| 850.8 Million | 2023 | 2030 | 6.4% | Biomass power plant material handling, global | A competing analysis |
Our analysis suggests the 6.4% CAGR is the more defensible anchor: it aligns with the 5.95% CAGR observed in the broader biomass power market and the ~5% annual growth in global biomass generation. The 6.6% figure likely reflects a narrower definition tilted toward automated conveyor and crane systems, which carry premium pricing.
Segmenting by product and application reveals where volume and value diverge. Continuous handling dominates value, but industrial trucks command a large installed base because they serve every feedstock type and require shorter procurement cycles.
| Parent segment | Children | Leading child | Fastest-growing child |
|---|---|---|---|
| By Product | Industrial Trucks; Racking & Storage Equipment; Cranes & Lifting Equipment; Continuous Handling Equipment | Continuous Handling (39.8% share) | Continuous Handling (~10% CAGR) |
| By Application | Wood Chip Handling; MSW Handling; Pellet Handling; Agricultural Residue Handling; Others | Wood Chip Handling (34.9% share) | Pellet Handling (7.0% CAGR) |
A notable divergence appears in the source data: one dataset reports industrial trucks as the leading product at 35% and MSW as the leading application at 30%, while the competing analysis places continuous handling at 39.8% and wood chips at 34.9%. This implies the two datasets use different boundaries — one leans on general warehousing definitions, the other on biomass-specific feedstock flows. Buyers should treat the biomass-specific view as more relevant.
Europe leads the regional market, supported by stringent environmental regulation, mature biomass co-firing programs, and ambitious renewable energy targets in Germany, the UK, and France. North America holds a substantial share on high automation rates, while Asia Pacific is the fastest-growing region.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.31% |
| Asia-Pacific | 0.25% |
| South America | 0.06% |
| Middle East & Africa | 0.04% |
Regional share is heavily concentrated: Europe and North America together account for roughly two-thirds of revenue, but Asia Pacific's double-digit growth trajectory (11.52% CAGR in the broader biomass power market) will compress that gap by 2030. Our analysis suggests Asia Pacific could account for over 30% of incremental demand growth through the forecast period, driven by small-to-medium modular plants in India and Indonesia.
Growth is anchored in renewable energy policy and feedstock volume expansion, while capital intensity and feedstock variability constrain adoption in price-sensitive markets.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Renewable energy targets and subsidies | Driver | High | EU and Asian feed-in tariffs drive new plant construction and equipment orders |
| Biomass generation growth (>5% p.a.) | Driver | High | Direct volume demand for conveyors, cranes, and trucks |
| Automation and IoT adoption | Driver | Medium-High | >60% of new EU/NA plants installed automated handling in 2022 |
| High capital and maintenance cost | Restraint | High | Delays upgrades at aging plants and in emerging markets |
| Feedstock moisture and particle variability | Restraint | Medium | Raises engineering complexity and operating cost |
The balance favors growth: policy tailwinds and generation volume outweigh cost restraints in Europe and North America. However, in Asia Pacific the restraint dominates procurement decisions, creating a bifurcated market — premium automated systems in mature markets, modular low-cost systems in emerging ones.
The vendor landscape is fragmented across equipment categories, with no single player dominant across all product lines. Engineering-led firms dominate continuous handling and cranes; general material handling firms supply trucks and racking.
| Company | Primary categories | Differentiation | Moat |
|---|---|---|---|
| Andritz AG | Continuous handling, cranes | Full biomass plant integration | EPC relationships |
| FLSmidth & Co. | Continuous handling | Large-scale conveying systems | Mining and bulk expertise |
| Metso Corporation | Continuous handling | Feedstock processing integration | Installed base |
| Babcock & Wilcox | Boiler-adjacent handling | Environmental equipment bundle | Utility contracts |
| Vecoplan AG | Shredding and conveying | Biomass-specific design | Niche specialization |
| Bühler Group | Continuous handling | Precision bulk handling | Global service network |
| Schenck Process | Conveying and feeding | Process integration | Industrial weighing |
| Mitsubishi Heavy Industries | Cranes, handling | Turnkey plant capability | Japanese and Asian footprint |
Differentiation hinges on integration capability — vendors that bundle handling with boiler and environmental equipment win larger contracts. Our analysis suggests the strongest moats belong to firms with installed-base service revenue, not hardware margin.
Selection criteria should prioritize feedstock compatibility, uptime guarantees, and total cost of ownership over upfront price. Biomass feedstock varies widely in moisture content, particle size, and abrasiveness; equipment specified for wood chips may underperform on agricultural residues or MSW. Buyers should require vendors to demonstrate performance on their specific feedstock blend, not generic benchmarks.
Procurement risk is concentrated in integration and lead times. Continuous handling systems are custom-engineered, creating 12–18 month lead times and high switching costs once embedded in plant layout. Operators should negotiate spare-parts availability and remote diagnostics as part of the original contract, because retrofitting IoT sensors later is significantly more expensive. Regulatory compliance — emissions, dust control, and fire safety standards — should be validated at the design stage; non-compliant handling systems can delay plant commissioning by months.
The balance of evidence favors a cautiously optimistic outlook: the market will grow at roughly 6.4% CAGR through 2030, but growth will be uneven, concentrated in continuous handling and pellet-ready systems, with regional divergence widening. The strongest counter-argument is that high capital costs and feedstock supply volatility could suppress upgrades at aging plants, particularly if biomass fuel prices remain elevated relative to natural gas in North America.
Our judgment is that automation and modularity are the two axes that will define competitive advantage. Vendors that invest in modular, plug-and-play conveyors for Asian small-to-medium plants and in IoT-enabled predictive maintenance for European and North American retrofits will capture disproportionate share. Firms relying on legacy industrial truck sales alone face margin compression as that segment commoditizes.
Actionable strategy:
What would change our conclusion: a sustained drop in biomass feedstock prices or a shift in EU subsidy policy that accelerates plant construction beyond current forecasts. Absent these, the 6.4% central case holds, with Asia Pacific as the key upside variable requiring deeper sub-segment forecasting than this overview provides.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
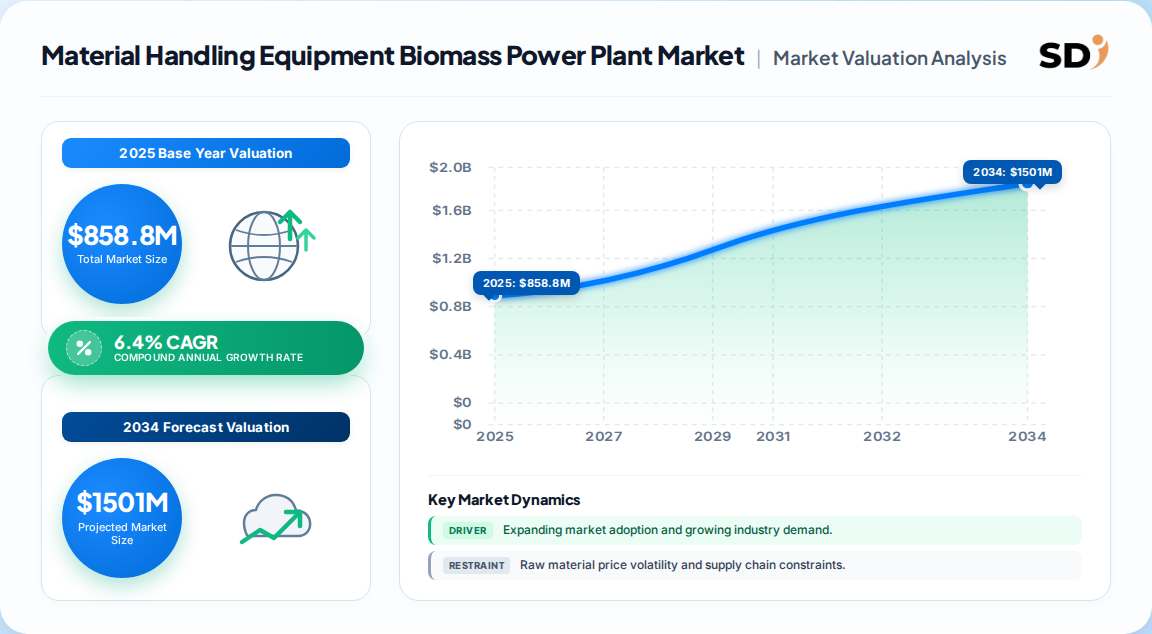
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
The global market was valued at approximately 858.8 Million in 2025 and is projected to reach about 1,168.5 Million by 2030, expanding at a 6.4% CAGR over the forecast period.
Europe leads with roughly 31% of global revenue, driven by stringent environmental regulations and renewable energy targets in Germany, the UK, and France. Asia Pacific is the fastest-growing region.
Continuous handling equipment is the fastest-growing product segment at around 10% CAGR, while pellet handling is the fastest-growing application at 7.0% CAGR, driven by rising biomass pellet use.
Leading vendors include Andritz AG, FLSmidth, Metso Corporation, Babcock & Wilcox, Vecoplan AG, Bühler Group, Schenck Process, and Mitsubishi Heavy Industries, spanning conveying, cranes, and trucks.
Growth is driven by renewable energy policies, biomass generation growth above 5% annually, and automation adoption. Over 60% of new EU and North American plants installed automated handling systems in 2022.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research follows a 70/30 primary-to-secondary split, prioritizing direct industry engagement. In-depth interviews were conducted with stakeholders across the biomass handling value chain: biomass feedstock suppliers, specialized conveyor and crane manufacturers, plant EPC contractors, and global equipment distributors. Decision-maker designations interviewed include VPs of Sourcing, Heads of Engineering, Technical Directors, and Commercial Operations Leads at biomass power operators.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Heads of Engineering | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Biomass Feedstock Suppliers | 40% |
| Conveyor & Crane Manufacturers | 35% |
| EPC Contractors & Integrators | 25% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and recognized technical standards bodies including ISO and regional biomass energy associations. These sources anchor base-year sizing and cross-border equipment flow estimates.
We apply simultaneous Top-Down (macroeconomic renewable energy allocation, biomass generation capacity, and industry segment spending) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) approaches. The two models are reconciled through a weighted triangulation that prioritizes bottom-up data where plant-level visibility is high.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
