 Mining Oil Gas Fasteners Market
 Outlook 2025
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 199

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Mining Oil Gas Fasteners Market
Sandeep Singh
Research Analyst

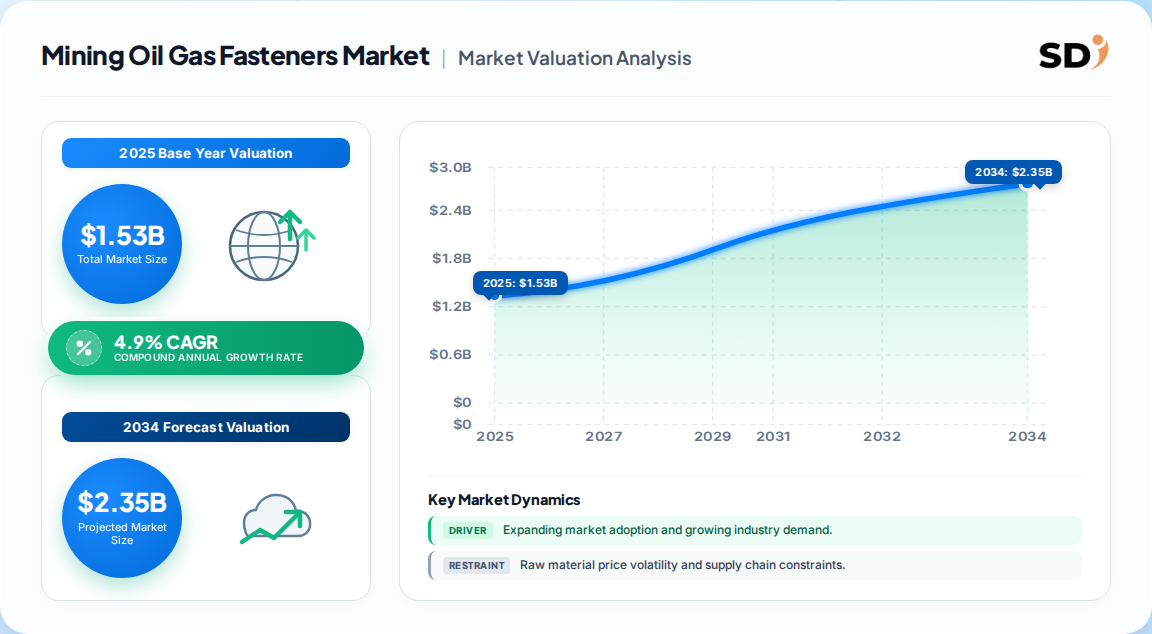
| Year | Market Size |
|---|---|
| 2024 | 1.460 B |
| 2025 | 1.530 B |
| 2026 | 1.500 B |
| 2027 | 1.610 B |
| 2028 | 1.690 B |
| 2029 | 1.780 B |
| 2030 | 1.900 B |

The Mining Oil Gas Fasteners Market covers mechanical components, including bolts, nuts, studs, washers, anchors and non-threaded fixings, engineered to join and secure equipment, pipelines, valves, tanks and structures in mining and oil and gas operations. Products are typically metal, with corrosion-resistant alloys and coatings specified for harsh, high-load and marine environments.
This analysis covers fasteners sold into mining and oil and gas end-use applications across all major regions, segmented by material, product type, application and size. It addresses commodity and engineered grades, including steel, stainless, nickel alloys and superduplex grades. This analysis does not cover general industrial construction fasteners, automotive fasteners, consumer hardware, or dedicated hand-tool and bolting-equipment markets except where they directly influence fastener specification.
The most defensible reading of the data places the market near 1.53 Billion in 2025, growing at a 4.9% CAGR toward 1.9 Billion by 2030; competing estimates diverge by over an order of magnitude, reflecting radically different scope definitions rather than genuine demand differences.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 1.3 Billion | 2022 | 2030 | 4.9% | Metal and plastic fasteners, mining and oil and gas end-use only | One published estimate |
| 20.85 Billion | 2024 | 2035 | 3.22% | Broader fastener categories including washers, anchors and coatings | A competing analysis |
| 1.33 Billion | 2025 | 2035 | 15.27% | Narrow mining and oil and gas fasteners with aggressive growth assumptions | A third-party forecast |
Our analysis suggests the 4.9% mid-single-digit view is the most defensible. It aligns with mature end-market capex cycles, a metal fastener base of roughly 98% revenue share, and modest replacement demand. The double-digit 15.27% projection appears to extrapolate early-stage offshore and alloy adoption across an unrealistically large base, while the 20.85 Billion figure almost certainly bundles adjacent industrial fastener categories. Buyers should anchor budgeting and vendor evaluation on the mid-single-digit trajectory.
Segmentation is dominated by material, with metal capturing roughly 98% of revenue; product form, application and corrosion protection then split the remainder into distinct demand pockets with very different margin profiles.
| Parent Segment | Children |
|---|---|
| By Material | Metal, Plastic |
| By Product | Externally Threaded (bolts, screws, studs), Internally Threaded (nuts, inserts), Non-Threaded |
| By Application | Flanges, Pipelines, Valves, Tanks, Structures |
| By Bolt Type | Nuts, Bolts, Washers, Studs, Anchors |
| By Size | Small, Medium, Large |
| By Corrosion Protection | Coating, Heat Treatment, Other |
Externally threaded products hold the largest product share at 47.3%, driven by ease of installation, high clamping force and wide availability. Bolts lead the bolt-type split, while flanges are the largest application. The plastic segment is small but growing faster because of weight and corrosion advantages, though it remains immaterial to revenue in the near term.
Asia Pacific leads global demand with 35.7% revenue share in 2022, and North America and Europe follow, supported by mature oilfield services and mining bases; within Asia Pacific, Australia anchors regional revenue while Indonesia grows fastest at a 6.5% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.27% |
| Europe | 0.23% |
| Asia-Pacific | 0.36% |
| Latin America | 0.06% |
| Middle East & Africa | 0.08% |
| Region | Share (2022) |
|---|---|
| Asia Pacific | 35.7% |
| North America | 27% |
| Europe | 23.1% |
| Middle East & Africa | 8% |
| Latin America | 6.2% |
Our analysis suggests regional leadership is a proxy for project pipeline, not price. Asia Pacific's share reflects mining expansion and state-backed energy investment, while the U.S. remains the single largest country market and is projected to lead global revenue through 2030. Indonesia, at just 0.7% of 2022 global revenue, signals where incremental volume growth will concentrate.
Growth is driven by rising global energy demand, expanding mining output and the shift to corrosion-resistant engineered fasteners, while high alloy costs, strict certification and qualification lead times restrain faster adoption and cap near-term volume growth.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising energy demand and population growth | Driver | High | Expands drilling, refining and mining capex, lifting fastener volume |
| Offshore and subsea development | Driver | High | Requires superduplex and nickel-alloy fasteners with higher unit value |
| Equipment reliability and downtime reduction | Driver | Medium | Favors engineered locking and tensioning solutions |
| Safety and compliance standards | Driver | Medium | Certification requirements raise specification quality |
| High alloy and raw material costs | Restraint | High | Pressures buyer budgets and encourages substitution |
| Long qualification and certification cycles | Restraint | Medium | Slows vendor switching and new product adoption |
| Availability of low-cost standard fasteners | Restraint | Medium | Caps pricing power in commodity segments |
Our analysis suggests the balance favors steady rather than explosive growth. Driver strength is structural but mature, while restraints are largely cost and process based. The net effect is a market that rewards suppliers able to certify and stock engineered grades, while commodity suppliers face persistent price competition. Sustainability and AI-enabled predictive maintenance are emerging accelerants but remain too early to shift the aggregate CAGR materially.
The vendor landscape is led by Fastenal, Hilti Group, Parker Hannifin, Bulten, Würth Group and Stanley Black & Decker, each combining fastener portfolios with distribution reach and engineered fastening expertise across mining and energy end-markets.
| Company | HQ | Positioning | Strategic Moat |
|---|---|---|---|
| Fastenal | USA | Broad industrial distribution | Vending and inventory programs at customer sites |
| Hilti Group | Liechtenstein | Engineered fastening and anchoring | Technical service and specification influence |
| Parker Hannifin | USA | Engineered components and sealing | Cross-selling into fluid and sealing systems |
| Bulten | Sweden | Fastener manufacturing at scale | OEM supply relationships and quality systems |
| Würth Group | Germany | Industrial and assembly distribution | Vast catalog and logistics network |
| Stanley Black & Decker | USA | Fastening and industrial tools | Brand and multi-category channel access |
| Nord-Lock Group | Sweden | Bolt securing and tensioning | Proprietary locking technology |
Differentiation is shifting from catalog breadth to engineered solutions and certification depth. Our analysis suggests vendors with on-site inventory management and proprietary locking or tensioning technology hold the strongest switching costs, because specification into safety-critical joints creates multi-year replacement and maintenance lock-in. Pure commodity suppliers compete almost entirely on price and lead time.
Buyers must prioritize certified material traceability, corrosion performance and preload accuracy over unit price, because fastener failure in safety-critical joints drives far higher downtime and liability costs than any procurement saving. Procurement risk concentrates in alloy grade substitution, counterfeit or uncertified stock, and long qualification lead times for new suppliers. Operators should standardize specifications across sites to reduce inventory complexity, and lock in multi-year supply agreements for superduplex and nickel-alloy grades where availability is tight. Regulatory compliance with offshore, pressure-equipment and mining safety standards is non-negotiable and increasingly audited. Switching costs are highest where vendors embed inventory management, so buyers should negotiate exit terms and dual-source critical grades to preserve leverage.
The balance of evidence favors a mid-single-digit growth outlook of roughly 4.9% CAGR, not the double-digit projections circulating in some analyses. The strongest counter-argument is that rapid offshore and deep-mining expansion could pull alloy adoption forward faster than base-case modeling implies; however, long qualification cycles and high material costs make a 15% sustained CAGR implausible over a decade. The defensible strategic conclusion is that value migrates toward engineered, certified and corrosion-resistant fastening, while commodity steel volume grows slowly and margin-poor.
Our analysis suggests the most important second-order effect is specification lock-in. Once a superduplex or nickel-alloy fastener is qualified into a subsea or high-temperature joint, switching costs and audit requirements protect incumbents for years. Vendors that invest in certification, technical field service and site-level inventory integration will capture disproportionate share of the higher-value alloy pool, while distributors without engineering capability will compete on logistics alone.
Actionable strategy:
The evidence that would change this conclusion is a sustained acceleration in offshore project sanctioning or a structural alloy cost decline that widens addressable demand faster than modeled.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material and alloy suppliers, specialized fastener producers, contract manufacturers and global industrial distributors. Decision-makers interviewed included VP-level sourcing executives, heads of engineering and R&D, technical directors and commercial operations leads, ensuring both demand-side and supply-side perspectives were captured.
Secondary validation drew on official multilateral trade databases such as UN Comtrade, WTO statistics, US ITC and Eurostat, alongside corporate annual filings, SEC 10-K disclosures, investor presentations, patent databases and recognized technical standards bodies. These sources were used to cross-check trade flows, capacity announcements and certification requirements rather than to substitute for primary fieldwork.
Market sizing combined top-down macroeconomic and end-segment allocation with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Conflicting published estimates were reconciled by normalizing scope definitions, isolating mining and oil and gas end-use revenue, and applying consistent CAGR assumptions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow and regional consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.9% from 2020-2034 |
| Segmentation |
|
The market is valued at roughly 1.53 Billion in 2025, based on a 1.3 Billion 2022 base compounding at 4.9% annually. Published estimates differ widely because of scope differences, but the mid-single-digit trajectory is the most defensible.
A 4.9% CAGR is the most defensible estimate through 2030. Higher published projections of 15% or more rely on aggressive alloy adoption assumptions that conflict with long qualification cycles and high raw-material costs.
Metal fasteners dominate with roughly 98% revenue share, led by steel and stainless grades. Corrosion-resistant alloys such as superduplex and nickel alloys are the fastest-growing segment, driven by offshore and subsea applications.
Asia Pacific leads with 35.7% revenue share, supported by mining and energy expansion. The U.S. remains the largest single country market, while Indonesia is among the fastest-growing country markets at a 6.5% CAGR.
Leading vendors include Fastenal, Hilti Group, Parker Hannifin, Bulten, Würth Group, Stanley Black & Decker and Nord-Lock Group. Competition is shifting from catalog breadth toward certified engineered solutions and on-site inventory integration.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and alloy suppliers, specialized fastener producers, contract manufacturers and global industrial distributors. Decision-makers interviewed included VP-level sourcing executives, heads of engineering and R&D, technical directors and commercial operations leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Engineering & R&D Directors | 40% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Alloy Producers | 30% |
| Specialized Fastener Producers | 40% |
| Contract Manufacturers | 15% |
| Industrial Distributors | 15% |
Secondary validation drew on UN Comtrade, WTO statistics, US ITC and Eurostat, alongside corporate annual filings, SEC 10-K disclosures, investor presentations, patent databases and recognized technical standards bodies.
Market sizing combined top-down macroeconomic and end-segment allocation with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Conflicting published estimates were reconciled by normalizing scope definitions and isolating mining and oil and gas end-use revenue.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow and regional consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |