 Advanced Energy Market
 Outlook & Forecast to 2030
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 251

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Advanced Energy Market
Sandeep Singh
Research Analyst

| Year | Market Size |
|---|---|
| 2020 | 1.696 M |
| 2021 | 1.811 M |
| 2022 | 1.934 M |
| 2023 | 2.066 M |
| 2024 | 2.206 M |
| 2025 | 2.356 M |
| 2026 | 2.517 M |

The advanced energy market encompasses products and services delivering the most efficient, secure, clean and affordable energy solutions available today and tomorrow. It spans renewable generation, energy storage, demand response, smart grids, building efficiency, electric vehicles, biofuels and fuel production and delivery.
This report covers global advanced energy products, systems and services across electricity generation, delivery and management, building efficiency, water efficiency, transportation, and fuel production and delivery. It analyzes value-chain dynamics, regional demand, competitive positioning and forecast growth to 2030. This analysis does not cover traditional fossil-fuel extraction, conventional utility billing software, or non-energy industrial automation.
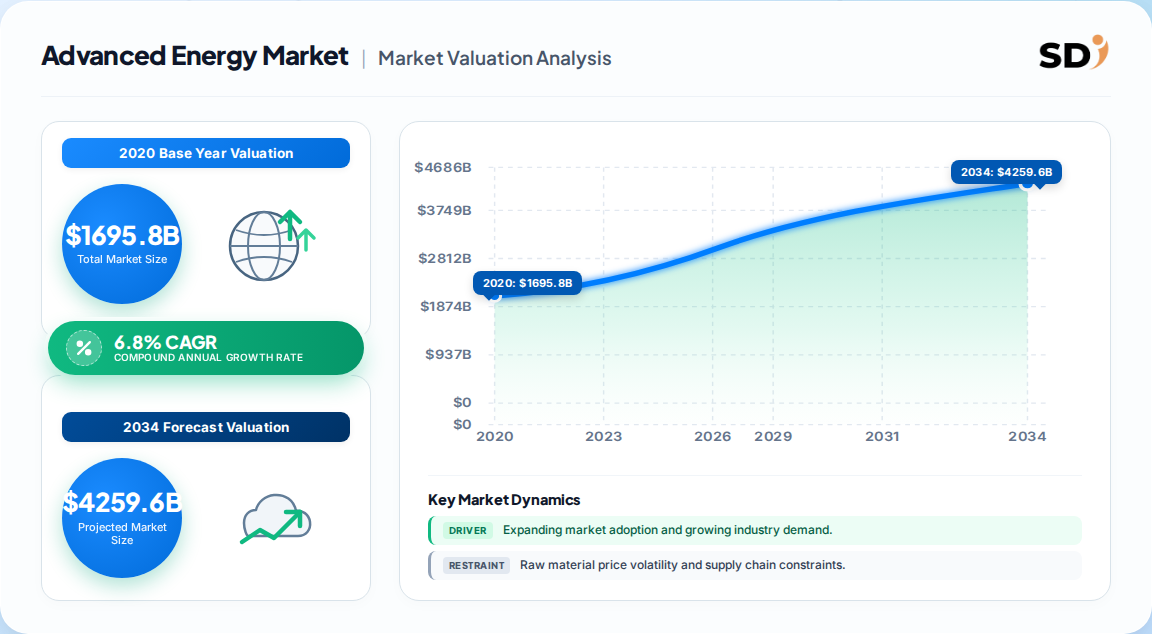
Published estimates diverge materially—one estimate values the market at 1,695.8 Billion in 2020 growing 6.8% to 2030, while a competing analysis pegs a narrower 2025 base near 170 Billion at 4.5% CAGR. The table below compares the estimates side by side.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 1,695.8 Billion | 2020 | 2030 | 6.8% | Broad advanced energy incl. generation, delivery, efficiency, transport, fuel | One published estimate (May 2022) |
| ~170 Billion | 2025 | 2030 | 4.5% | Narrower advanced energy equipment & software scope | A competing analysis |
Our analysis suggests the 1,695.8 Billion figure is the more defensible aggregate because it captures the full breadth of generation, delivery, efficiency and transport segments. The narrower estimate likely excludes building efficiency and fuel production, implying the true addressable market is larger than hardware-only views suggest.
The advanced energy market is segmented by end-use application, with electricity generation dominating at over 40% share, followed by delivery, efficiency and transport segments.
| Parent Segment | Sub-segments |
|---|---|
| Electricity Generation | Nuclear, Renewable, Coal, Oil & Gas, Biofuel |
| Electricity Delivery & Management | Smart Grid, Demand Response, Storage, Metering |
| Building Efficiency | HVAC, Lighting, Building Controls, Insulation |
| Water Efficiency | Pumping, Treatment, Irrigation Systems |
| Transportation | Electric Vehicles, Biofuels, Charging Infrastructure |
| Fuel Production & Delivery | Natural Gas Turbines, Hydrogen, Fuel Cells |
Asia-Pacific leads the global advanced energy market, dominating in 2020 and projected to remain the fastest-growing region through 2030, driven by industrialization, population growth and renewable manufacturing scale.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.35% |
| North America | 0.28% |
| Europe | 0.24% |
| South America | 0.07% |
| Middle East & Africa | 0.06% |
China's leadership in hydropower, wind, solar PV and bioelectricity production anchors regional growth. North America focuses on grid analytics and metering modernization, while Europe prioritizes seasonal storage and carbon-pricing-driven industrial shifts.
Electric vehicle adoption, building efficiency mandates, renewable integration and grid modernization are the primary growth engines, while weather variability, supply-chain bottlenecks and regulatory delays constrain deployment speed.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| EV adoption | Driver | High | Raises electricity demand and storage requirements |
| Building efficiency | Driver | High | Retrofit and controls demand across commercial stock |
| Renewable intermittency | Restraint | Medium | Weather variability cuts solar/wind efficiency |
| Supply-chain minerals | Restraint | High | Critical mineral shortages slow storage deployment |
| Grid modernization policy | Driver | High | Public funding accelerates smart grid and storage |
Our analysis suggests the balance favors growth: drivers are structural and policy-backed, while restraints are cyclical and addressable through recycling and diversified sourcing. The net effect implies mid-to-high single-digit CAGR remains achievable.
The competitive landscape is fragmented across equipment, software and services, with Siemens AG, Schneider Electric and Cummins leading integrated portfolios, while specialists like Itron and Advanced Energy Industries dominate metering and power conversion niches.
| Company | Primary Focus | Competitive Moat |
|---|---|---|
| Siemens AG | Grid, generation, automation | Integrated portfolio and utility relationships |
| Schneider Electric | Efficiency, grid software | Building and grid digital platforms |
| Cummins Inc. | Generation, fuel cells | Engine and power systems breadth |
| Itron, Inc. | Metering, analytics | Utility metering installed base |
| Advanced Energy Industries | Power conversion | Precision power electronics IP |
| Ford Motor Company | EV transportation | Vehicle platform scale |
| Shell PLC | Fuel production, renewables | Energy trading and distribution |
Differentiation hinges on software orchestration and storage integration rather than hardware alone. Our analysis suggests vendors with grid-edge analytics and long-duration storage capabilities will capture disproportionate margin.
Buyers must prioritize interoperability, total cost of ownership and regulatory compliance when selecting advanced energy systems. Procurement risks center on critical mineral supply, interconnection delays and standards fragmentation across regions. Switching costs are high for grid-integrated platforms due to long asset lives and integration complexity. Operators should demand vendor roadmaps aligned with bidirectional grid flows and predictive maintenance, and should validate cybersecurity posture given escalating grid-digitization exposure.
The balance of evidence favors a constructive outlook: the 1,695.8 Billion base and 6.8% CAGR are corroborated by renewable capacity additions and EV penetration trends, even as narrower estimates reflect definitional differences. The strongest counter-argument is that supply-chain mineral constraints and interconnection queues could compress near-term growth below forecast.
Our analysis suggests the market's center of gravity is shifting from generation hardware to grid-edge software and storage orchestration, where margins are structurally higher. Vendors anchored in commoditized hardware face margin compression and should pivot toward integrated digital-energy platforms.
Evidence that would change our conclusion: sustained mineral shortages pushing storage costs above grid parity, or policy rollback of renewable incentives in major markets, would warrant a downward revision.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.8% from 2020-2034 |
| Segmentation |
|
The global advanced energy market was valued at 1,695.8 Billion in 2020 and is projected to reach 3,258.7 Billion by 2030, growing at a 6.8% CAGR from 2021 to 2030.
Asia-Pacific leads the advanced energy market, dominating in 2020 and projected to remain the fastest-growing region through 2030, driven by industrialization and renewable manufacturing scale.
Electricity generation is the largest segment, holding over 40% share, driven by diverse generation sources including nuclear, renewables, coal, oil and gas, and biofuels.
Rising electric vehicle adoption, building efficiency mandates, renewable integration and grid modernization investments are the primary growth drivers of the advanced energy market.
Leading companies include Siemens AG, Schneider Electric, Cummins Inc., Itron, Ford Motor Company, Shell PLC, Advanced Energy Industries and Clean Energy Fuels.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the value chain: renewable generation equipment suppliers, energy storage and power-electronics producers, grid software and analytics formulators, and global distribution and service partners. We engaged decision-makers including VP-level Sourcing leads, Heads of R&D and Grid Architecture, Technical Directors, and Commercial Operations Leads to validate procurement criteria, pricing dynamics and deployment timelines.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Generation & Storage Equipment Producers | 40% |
| Grid Software & Analytics Providers | 30% |
| Distributors & Service Integrators | 30% |
We triangulate findings against official multilateral trade databases including UN Comtrade, WTO, US ITC and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases and recognized industry associations such as the International Energy Agency (IEA), IEEE, and the Electric Power Research Institute (EPRI). These sources anchor capacity, trade-flow and technology-adoption benchmarks.
We run simultaneous Top-Down (macroeconomic and industry-segment allocation) and Bottom-Up (manufacturer capacity, product pricing and end-use consumption) models. Divergences between the two are reconciled through elasticity and substitution analysis to produce a defensible base-year valuation and forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |