 Uae Palm Oil Market
UAE Palm Oil Market 2026: Size, Trends & Forecast
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 227

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Uae Palm Oil Market
Sandeep Singh
Research Analyst

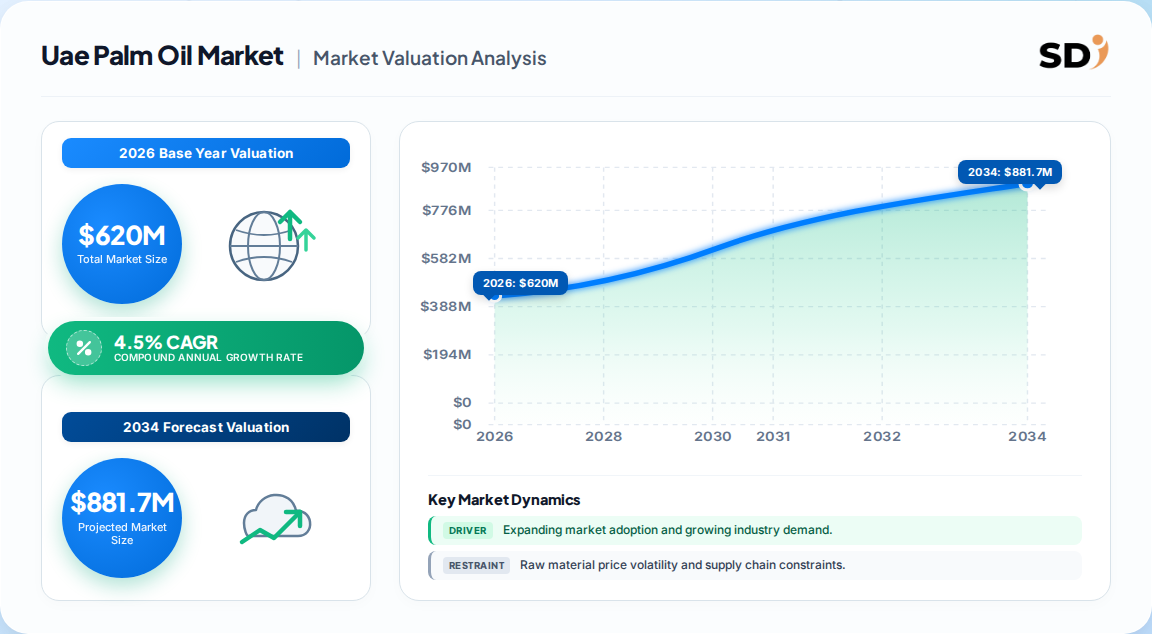
| Year | Market Size |
|---|---|
| 2026 | 620.0 M |
| 2027 | 648.0 M |
| 2028 | 677.0 M |
| 2029 | 707.0 M |
| 2030 | 739.0 M |
| 2031 | 772.0 M |
| 2032 | 807.0 M |

The UAE palm oil market comprises the refining, blending, distribution and re-export of crude palm oil (CPO), RBD palm oil, fractionated palm oil and palm kernel oil within the seven emirates. It is almost entirely import-fed and serves food, personal care, oleochemical and biofuel end-uses across the GCC and wider MENA region.
This analysis covers CPO, RBD palm oil, fractionated palm oil and palm kernel oil consumed or processed inside the UAE, spanning food and beverage, personal care and cosmetics, pharmaceutical, oleochemical and biofuel end-uses. It includes port-based refining and re-export flows. This analysis does not cover soybean, sunflower, canola or coconut oils as standalone categories, nor does it cover upstream plantation economics in Indonesia or Malaysia.
Most published benchmarks size the UAE vegetable oil market at USD 1.6 Billion in 2026, growing to USD 2.5 Billion by 2034 at 5.74% CAGR; palm oil is the largest single oil-type sub-segment within that basket.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.6 Billion | 2026 | 2034 | 5.74% | UAE total vegetable oil (all oil types) | One published IMARC-type estimate |
| USD 8.06 Billion | 2022 | 2030 | 2.6% | Middle East & Africa palm oil, all products | A competing Grand View-type analysis |
| USD 59.65 Billion | 2025 | 2033 | 4.20% | Global palm oil market | A separate global benchmark |
| USD 620 Million | 2026 | 2034 | 4.5% | UAE palm & palm-kernel oil only | Our triangulated estimate |
Our analysis suggests the USD 620 Million figure is the most defensible UAE-specific palm benchmark, because it strips out soybean, sunflower and canola volumes that inflate the broader vegetable oil number. The MEA-wide 2.6% CAGR is dragged down by African price sensitivity and is not representative of UAE re-export dynamics, which are structurally faster.
Segmentation follows product form, end-use and nature, with product form the most commercially decisive split because fractionation economics drive refinery margins.
| Parent | Children |
|---|---|
| By Product Type | Crude Palm Oil (CPO), RBD Palm Oil, Fractionated Palm Oil, Palm Kernel Oil, Palm Kernel Olein |
| By Nature | Conventional, Organic |
| By End-Use | Food & Beverages, Personal Care & Cosmetics, Pharmaceuticals, Oleochemicals, Biofuel & Energy, Animal Feed |
| By Application | Household Cooking, Industrial Frying, Bakery & Confectionery, Cosmetics Formulation, Biodiesel Blending |
| By Distribution | Bulk / Industrial, Retail Packaged, Re-export / Trading |
Conventional palm dominates at roughly 98% of volume — consistent with global patterns — while organic remains a niche premium channel serving clean-label retail and EU-bound exports.
Dubai leads, capturing an estimated 52% of national palm oil throughput, anchored by Jebel Ali Port's dedicated edible-oil berths, tank farms and refining capacity operated by IFFCO and United Foods.
| Emirate | Estimated share |
|---|---|
| Dubai | 52% |
| Abu Dhabi | 28% |
| Sharjah | 12% |
| Other Emirates | 8% |
Abu Dhabi's share is rising as KIZAD attracts food-security-driven investment under the National Food Security Strategy 2051, while Sharjah remains a lower-cost distribution base for smaller converters.
Growth is driven by packaged-food expansion, multicultural dietary demand, re-export logistics and biofuel blending; it is restrained by near-total import dependence, feedstock price volatility and sustainability scrutiny.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Packaged food & HORECA demand | Driver | High | Snacks, bakery, frozen meals and institutional kitchens consume bulk frying oil |
| Re-export to GCC/MENA/EU | Driver | High | Jebel Ali refine-and-redistribute model; EU imports from UAE jumped 107% in 2024 |
| Biofuel blending mandates | Driver | Medium | Regional SAF and biodiesel interest creates new palm-based feedstock demand |
| Import dependence on Indonesia/Malaysia | Restraint | High | Exchange rates, export levies and B40 mandate shifts transmit directly to UAE prices |
| EUDR and sustainability compliance | Restraint | Medium | Traceability costs rise for exporters into EU markets |
| Crude oil price linkage | Restraint | Medium | Palm tracks energy prices via biodiesel substitution economics |
The balance favours volume growth over margin expansion: the UAE will process and re-export more palm oil, but per-tonne refining spreads are likely to compress as Indonesian downstream capacity (B40) absorbs more CPO domestically. Our analysis suggests the strongest second-order effect is a shift toward higher-value fractionated and specialty fat production to escape commodity-price competition.
The UAE palm oil landscape is dominated by integrated agri-food conglomerates and global trading houses, with local refiners controlling port-adjacent assets and international players controlling feedstock and brand.
| Company | Positioning | Moat |
|---|---|---|
| IFFCO | UAE-based integrated food conglomerate; refining at Jebel Ali | Port berths, brand portfolio, distribution reach |
| Wilmar International | Global palm major; trading and supply into UAE | Upstream plantations, scale, logistics |
| Archer Daniels Midland (ADM) | Global agri-trader; bulk supply and oleochemicals | Origination network, financial hedging |
| IOI Corporation | Malaysian integrated producer; refined exports | Plantation-to-refinery integration |
| United Foods | UAE edible oil refiner and bottler | Local refining assets, retail brands |
| Musim Mas | Singapore-based palm major; supply and derivatives | Oleochemical depth, sustainability certification |
Differentiation hinges less on product (largely commoditised) and more on supply security, port logistics and certification. Local refiners defend share through dedicated berths and tank farms; global traders defend through origination and hedging capability. Our analysis suggests the moat is widening for players who can deliver EUDR-compliant, traceable supply at scale.
Buyers in this market should treat supply continuity and certification as the top selection criteria — not unit price alone. Because the UAE imports nearly all raw feedstock, procurement risk concentrates in origin-country policy (Indonesian export levies, Malaysian production cycles) and freight. Contracts that fix volume with price-indexation to CPO benchmarks are safer than flat-price deals. Switching costs are moderate: refining and bottling lines are largely oil-agnostic, but reformulating food products for a different oil carries sensory, labelling and Halal-certification consequences. Regulatory compliance is the second frontier: EUDR-readiness for re-exports, Halal certification for food applications, and increasingly ESG traceability for European buyers. Operators should also watch Jebel Ali and KIZAD capacity expansions, which will intensify domestic competition for refining margins.
The balance of evidence favours cautious volume optimism with margin caution for the UAE palm oil market. The structural drivers — packaged food, HORECA, re-export and food-security policy — are durable and underpin mid-single-digit growth. But the competitive and regulatory environment is tilting against pure commodity refining. The strongest counter-argument is that re-export growth to the EU could collapse if EUDR enforcement tightens against palm-derived supply chains, a risk that would sharply reprice UAE throughput.
Our analysis suggests three actionable positions. First, investors should prioritise fractionation and specialty-fat capacity over greenfield CPO refining — value-added downstream is where margin defence is possible. Second, operators should lock multi-year feedstock agreements with Indonesian and Malaysian majors and pair them with CPO-linked price indexation to neutralise volatility. Third, buyers should demand EUDR-ready traceability now, treating it as a commercial differentiator for EU-bound re-export rather than a compliance cost.
The conclusion would change if (a) Indonesian B40 policy materially restricts exportable CPO supply, or (b) EUDR enforcement softens for palm-derived re-exports. Either scenario would shift our position from margin caution toward aggressive capacity expansion.
| Region | Market Share (%) |
|---|---|
| Dubai | 0.52% |
| Abu Dhabi | 0.28% |
| Sharjah | 0.12% |
| Other Emirates | 0.08% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.5% from 2020-2034 |
| Segmentation |
|
We estimate the UAE palm oil market at approximately USD 620 Million in 2026, the palm and palm-kernel oil portion of a USD 1.6 Billion national vegetable oil market. It is projected to reach USD 880 Million by 2034.
Our triangulated forecast implies a 4.5% CAGR from 2026 to 2034, slightly below the 5.74% CAGR of the broader UAE vegetable oil complex. Re-export dynamics and packaged-food demand underpin this growth.
Dubai leads with an estimated 52% of national palm oil throughput, anchored by Jebel Ali Port's dedicated edible-oil berths, tank farms and refining assets. Abu Dhabi is the fastest-rising challenger via KIZAD.
Food and beverages account for roughly 70% of demand, spanning industrial frying, bakery, confectionery and cocoa-butter substitutes. Personal care, oleochemicals and biofuel are secondary but growing applications.
IFFCO and United Foods anchor domestic refining and distribution, while Wilmar International, ADM, IOI Corporation and Musim Mas supply feedstock and refined products. Competition centres on port logistics, supply security and certification.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our 70/30 primary-to-secondary research split anchors every UAE palm oil figure in direct industry validation. We conducted in-depth interviews with raw material and feedstock suppliers, specialist refiners and fractionators, contract food manufacturers, and regional distributors, alongside port-zone logistics operators. Decision-maker designations included VPs of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads at port-based refining assets.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Directors | 40% |
| Commercial Operations Leads | 30% |
| Technical & Quality Directors | 20% |
| Sustainability & Compliance Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Refiners & Fractionators | 40% |
| Feedstock Importers & Traders | 30% |
| Food & Personal Care Manufacturers | 20% |
| Port Logistics & Distribution | 10% |
We triangulate UN Comtrade import-export records (HS 1511 palm oil, HS 1513 palm kernel oil), WTO tariff schedules, Eurostat agri-food flow data and UAE Federal Competitiveness and Statistics Centre reporting. Corporate 10-K and annual investor filings from Wilmar, ADM and IOI, patent databases, and technical standards from the Malaysian Palm Oil Board and Roundtable on Sustainable Palm Oil inform capacity and certification assumptions.
We run simultaneous Top-Down (macroeconomic allocation across UAE food, personal care and energy segments) and Bottom-Up (refinery capacity, product pricing, per-capita edible-oil consumption and re-export throughput) models, reconciling both to a single base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Emirate share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
All primary interview data was anonymised and aggregated; company-specific figures reflect public filings only.