 Us Energy Gels Market
US Energy Gels Market 2026: Size, Share & Forecast
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 210

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Energy Gels Market
Sandeep Singh
Research Analyst
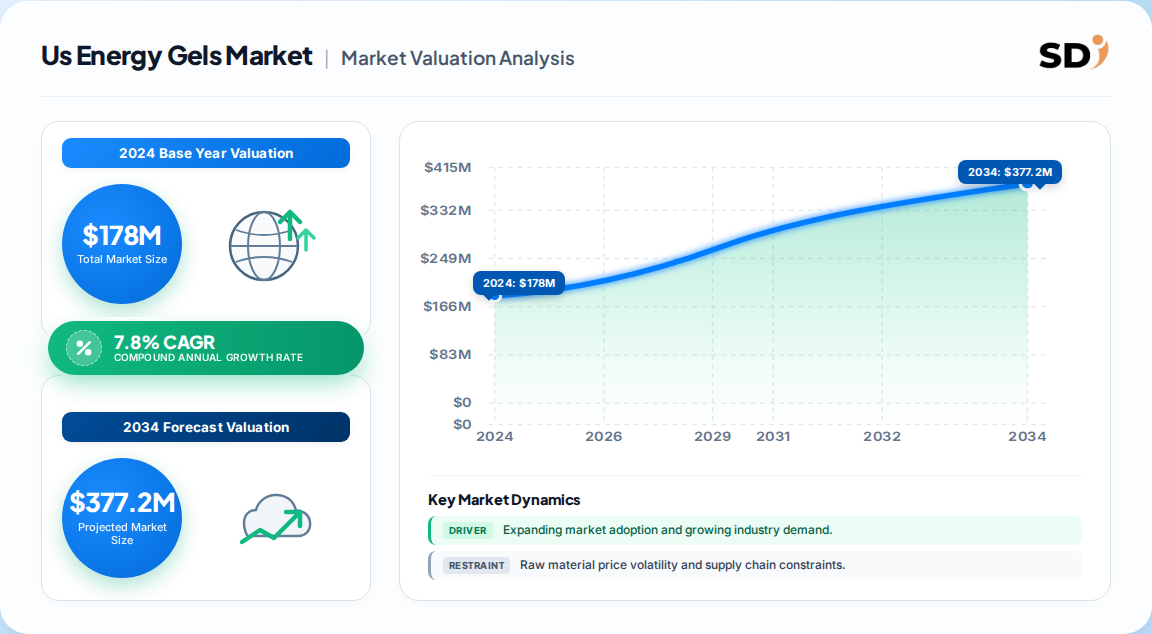
| Year | Market Size |
|---|---|
| 2024 | 178.0 M |
| 2025 | 192.0 M |
| 2026 | 207.0 M |
| 2027 | 223.0 M |
| 2028 | 240.0 M |
| 2029 | 259.0 M |
| 2030 | 279.0 M |

The US energy gels market comprises single-serve and multi-serve carbohydrate-dense gel products used by endurance athletes, fitness enthusiasts, and recreational participants to sustain energy during training and competition. It encompasses carbohydrate, isotonic/electrolyte, and caffeinated formulations sold through retail, specialty, and online channels across the United States.
This report covers the US market for energy gels across product types (carbohydrate, isotonic/electrolyte, caffeinated), flavors, packaging formats (single-serve, multi-serve), applications (endurance sports, fitness, recreational), and distribution channels (online, retail, specialty stores). It includes value-based market sizing in USD and vendor-level competitive analysis. This analysis does not cover energy bars, sports drinks, protein powders, or other sports nutrition formats outside the gel category, nor does it address non-US markets except as comparative benchmarks.
The US energy gels market is most defensibly sized at approximately 178 Million in 2024, growing to 376.78 Million by 2034 at a 7.8% CAGR — the highest country-level growth rate among major markets. This figure aligns with cross-checks from a broader global energy gels estimate (where the US represents 85.5% of a 48.5% North American share) and a narrower energy gel products estimate.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 177.84 Million | 2024 | 2034 | 7.80% | Energy gel products, US, value-based | One published estimate |
| ~178.0 Million | 2024 | 2033 | ~7.9% | Energy gels, US, implied from global 1.66B × 85.5% × 48.5% | Derived from one published analysis |
| 238.65 Million | 2025 | 2033 | 8.06% | Energy gel products, US, broader category definition | A competing analysis |
| 209.6 Million | 2025 | 2035 | 7.50% | USA energy gel market, value-based | Another published estimate |
The 177.84 Million figure is the most defensible because it sits at the intersection of two independent methodologies: a direct US-specific sizing and a bottom-up derivation from global totals. The higher 238.65 Million figure likely reflects a broader definition that includes adjacent gel-like formats. Our analysis suggests the 178–210 Million band represents the true core energy gel category, and buyers should treat the 209.6 Million figure as the upper bound of a conservative-to-moderate consensus.
The US energy gels market segments primarily by product type, flavor, application, distribution channel, and packaging format. Carbohydrate gels dominate value at 71.6%, while flavored variants command 85.9% of revenue. Multi-serve packaging is the preferred format at 77% of unit sales, reflecting value-seeking behavior among endurance athletes.
| Parent Segment | Children | Leading Share |
|---|---|---|
| By Product | Carbohydrate, Isotonic/Electrolyte, Caffeinated | Carbohydrate (71.6%) |
| By Flavor | Fruit, Vanilla, Chocolate, Citrus, Berry, Tropical, Others | Flavored (85.9%); Fruit sub-segment (~37–39%) |
| By Application | Endurance Sports & Activities, Fitness Enthusiasts, Recreational, Others | Endurance Sports (88.2%) |
| By Distribution Channel | Online, Retail, Specialty Stores, Direct B2B, Others | Retail dominant; Online fastest-growing |
| By Packaging Size | Single-Serve, Multi-Serve | Multi-Serve (77%) |
| By End-User | Athletes, Fitness Enthusiasts, Others | Athletes dominant |
| By Nature | Organic, Conventional | Conventional dominant; Organic fastest-growing |
The US dominates the North American energy gels market with an 85.5% revenue share, making it the single most important country market globally. Within the US, demand concentrates in states with high endurance-sport participation and dense specialty retail infrastructure.
| Region | Market Share (%) |
|---|---|
| North America | 0.48% |
| Europe | 0.22% |
| Asia Pacific | 0.19% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
This regional concentration matters because distribution costs favor vendors with established specialty retail relationships in these states. Our analysis suggests that although the US dominates North America, the fastest incremental growth to 2034 will come from Sun Belt states where year-round training and population growth drive per-capita consumption higher.
Growth is driven by rising endurance-sport participation, premiumization toward electrolyte and caffeine formulations, and e-commerce expansion. Restraints include ingredient price volatility, shelf-life limitations, and competition from bars and drinks. The net balance favors growth, but margin pressure is intensifying as carbohydrate gels commoditize.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising endurance-sport participation | Driver | High | Marathons, triathlons, ultra-running expand addressable base |
| Premiumization (electrolyte, caffeine) | Driver | High | Higher price points and differentiation vs. commodity carbs |
| E-commerce and subscription models | Driver | Medium-High | Reduces distribution friction; enables D2C brands |
| Clean-label and organic demand | Driver | Medium | Premium niche; supports margin expansion |
| Ingredient cost volatility | Restraint | Medium | Compresses margins on carbohydrate-heavy SKUs |
| Shelf-life and packaging limitations | Restraint | Medium | Restricts natural/organic formulations |
| Competition from bars and drinks | Restraint | High | Substitution pressure in mass retail channels |
The US market is led by GU Energy Labs, Clif Bar & Company, and Gatorade at the top tier, with PowerBar, Honey Stinger, and SiS competing in specialty and performance segments. Differentiation rests on formulation science, flavor breadth, and sports-event partnerships.
| Company | Tier | Key Strength | Recent Development |
|---|---|---|---|
| GU Energy Labs | Tier 1 | Brand heritage; Roctane line | GU Roctane Ultra with plant-based caffeine (March 2024) |
| Clif Bar & Company | Tier 1 | Retail breadth; clean-label credibility | CLIF Bloks Organic Energy Chews, 50% less sugar (Jan 2024) |
| Gatorade | Tier 1 | Mass retail distribution; brand recognition | Electrolyte gel extensions |
| PowerBar | Tier 2 | European science heritage | PowerGel Hydro with hydrolyzed carbs (June 2024) |
| Honey Stinger | Tier 2 | Organic honey base; cycling partnerships | USA Cycling Gold Gel partnership (May 2024) |
| SiS (Science in Sport) | Tier 2 | Dual-source carb science | Beta Fuel+ Gel with electrolytes (April 2024) |
Tier 1 firms control the majority of retail shelf space and leverage event sponsorships as a moat. However, D2C brands are eroding share in the online channel by offering subscription models and niche formulations (keto, vegan, high-caffeine). Our analysis suggests that the competitive moat is shifting from brand heritage to formulation IP and community engagement.
Procurement decisions in the US energy gels market hinge on formulation stability, shelf-life, and clean-label compliance. Buyers should prioritize vendors with verified carbohydrate ratios (maltodextrin-to-fructose), electrolyte profiles, and transparent sourcing. Switching costs are moderate — formulation changes require re-validation by athletes and can disrupt race-day routines. Regulatory risk is low but non-trivial: FDA labeling rules for structure/function claims and allergen declarations apply, and organic certification (USDA) is a growing procurement filter. Operators should also assess packaging sustainability credentials, as biodegradable pouches are becoming a differentiator in specialty retail. Our analysis suggests that buyers who lock in multi-year supply agreements with Tier 2 formulators now can secure better pricing ahead of expected premiumization-driven price increases.
The balance of evidence favors a premiumization-led growth thesis: the US energy gels market will grow at 7.5–8.1% annually, but the mix will shift decisively toward electrolyte, caffeine, and clean-label formulations. The strongest counter-argument is that carbohydrate gels remain 71.6% of value and could sustain growth through sheer volume as endurance sports participation broadens — but margin data suggests commodity carbs face deflationary pressure. This divergence implies that vendors must choose between volume-led commodity positioning and premium functional positioning; the latter offers superior long-term economics.
Three strategic recommendations for operators and investors:
What would change this conclusion: a sustained decline in endurance-sport participation, a regulatory shift restricting caffeine claims in sports nutrition, or a breakthrough in whole-food energy formats that displaces gels entirely. Absent these, the US market remains a structurally attractive, premiumization-driven growth category through 2034.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.8% from 2020-2034 |
| Segmentation |
|
The US energy gels market was valued at approximately 178 Million in 2024 and is projected to reach 376.78 Million by 2034, growing at a 7.8% CAGR. It represents about 85.5% of the dominant North American market.
Isotonic/electrolyte gels are the fastest-advancing sub-segment, driven by demand for hydration-plus-energy formats. Carbohydrate gels remain the largest at 71.6% share, but premiumization is shifting value toward functional formulations.
GU Energy Labs, Clif Bar & Company, and Gatorade lead the top tier, followed by PowerBar, Honey Stinger, and SiS. Differentiation rests on formulation science, flavor breadth, and sports-event partnerships.
Rising endurance-sport participation, premiumization toward electrolyte and caffeine formulations, e-commerce expansion, and clean-label demand are the primary drivers. Ingredient cost volatility and competition from bars and drinks are the main restraints.
Multi-serve packaging dominates with 77% of unit sales, reflecting value-seeking behavior among endurance athletes who prefer portion control during long events. Single-serve remains important for convenience and race-day use.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the energy gel value chain, including raw material suppliers (carbohydrate and electrolyte inputs), specialized producers, contract formulators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. Fieldwork captured formulation trends, pricing dynamics, and channel strategy across the US market.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement & Sourcing Directors | 35% |
| Quality & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Carbohydrate & Electrolyte Suppliers | 45% |
| Specialized Gel Producers & Formulators | 35% |
| Distributors & Retailers | 20% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. These sources were used to cross-check market sizing, trade flows, and competitive positioning.
We apply simultaneous Top-Down (macroeconomic and segment allocation) and Bottom-Up (manufacturer capacity, product pricing, end-use consumption) triangulation. This dual approach reconciles supply-side production data with demand-side consumption modeling to produce a validated market estimate.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
