 Energy Storage Chemicals Market
: 2025 Global Industry Forecast
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 219

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Energy Storage Chemicals Market
Sandeep Singh
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 130.0 M |
| 2025 | 154.0 M |
| 2026 | 172.0 M |
| 2027 | 200.0 M |
| 2028 | 233.0 M |
| 2029 | 271.0 M |
| 2030 | 315.0 M |

The energy storage chemicals market comprises specialty chemical inputs—lithium salts (LiPF₆, LiFSI), electrolytes, solvents, binders, conductive additives, and cathode/anode active materials—used in battery storage systems, flow batteries, and flywheel technologies across automotive, utility, and industrial applications.
This report covers specialty chemicals consumed in electrochemical and mechanical energy storage systems (lithium-ion, flow, sodium-sulfur, and flywheel), segmented by product, technology, end-use, and region. This analysis does not cover raw lithium/cobalt/nickel mining, battery cell manufacturing equipment, complete battery pack assembly, or thermal/mechanical storage systems that do not consume specialty chemicals.
The market is small in absolute dollar terms but expanding at a pace (16.3% CAGR) that outpaces most specialty chemical verticals. Published estimates diverge sharply because "energy storage chemicals" and broader "electro-chemical storage systems" are frequently conflated.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 130.0M → USD 500.3M | 2024 | 2033 | 16.3% | Specialty chemicals consumed in battery/flow/flywheel storage | One published estimate |
| USD 73.78B → USD 1,230.49B | 2024 | 2035 | 29.15% | Full electro-chemical storage systems (cells, packs, BMS) | A competing analysis |
| USD 99.7B → USD 868.2B | 2023 | 2032 | 25.2% | Electro-chemical storage systems (MW & USD) | A competing analysis |
| USD 20.20B → USD 46.31B | 2025 | 2034 | 9.7% | Advanced energy storage systems (all technologies) | A competing analysis |
The most defensible figure for chemicals alone is the USD 130M–500M trajectory, since the billion-dollar estimates measure complete systems, not the specialty chemicals layer. Our analysis suggests the chemicals sub-layer grows faster than systems because formulation complexity (LiFSI substitution, silicon-carbon anode binders, PFAS-free additives) increases chemical intensity per kWh.
Segmentation follows product chemistry, storage technology, and end-use vertical. The table below reflects non-geographic parent segments.
| Parent Segment | Children | 2024 Share |
|---|---|---|
| By Product | Lithium-ion battery, Flow battery, Others (sodium-sulfur, lead-acid) | Li-ion 65.6% |
| By Technology | Battery storage, Flywheel energy storage | Battery 74.6% |
| By End Use | Automotive, Utilities, Industrial, Commercial & Residential | Automotive 43.7% |
Asia Pacific leads with 46.2% revenue share (2024), anchored by China's dominance in lithium salt refining, electrolyte formulation, and cell manufacturing. North America and Europe follow, both investing heavily in domestic capacity to reduce import dependence.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.46% |
| North America | 0.22% |
| Europe | 0.18% |
| Latin America | 0.05% |
| Middle East & Africa | 0.04% |
Our analysis suggests APAC's share will erode modestly through 2033 as US and EU localization incentives (45X credit, Critical Raw Materials Act) shift electrolyte and cathode-active material production onshore—but the region will still hold a majority of refined chemical capacity.
Growth is driven by renewable integration, EV adoption, and policy incentives; restraints center on raw-material volatility, safety regulation, and qualification bottlenecks.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Renewable energy intermittency | Driver | High | Solar/wind buildout requires storage; each GWh consumes ~1,200–1,500 tonnes of electrolyte/salts |
| EV adoption & battery gigafactories | Driver | High | Automotive 43.7% share; each EV pack uses 10–15 kg of electrolyte |
| Government incentives (45X, EU CRM Act) | Driver | High | Subsidies de-risk domestic chemical capacity |
| Localization of critical material supply | Driver | Medium | Reduces import dependence; creates regional chemical demand |
| Lithium/cobalt price volatility | Restraint | High | Margin compression and delayed capacity commitments |
| PFAS and fluoropolymer regulation | Restraint | Medium | Requires reformulation of binders and additives; raises R&D cost |
| Battery OEM qualification cycles | Restraint | High | 24–36 month cycles lock out new entrants |
The market is moderately to highly concentrated in advanced battery materials, where a limited number of global electrochemical specialists dominate lithium salts, electrolytes, and cathode-active materials.
| Company Archetype | Examples | Strategic Position | Moat |
|---|---|---|---|
| Integrated electrolyte/salt producers | Established APAC chemical majors | High share in LiPF₆, LiFSI | Qualification lock-in, scale |
| Cathode active material specialists | Global CAM producers | NMC/LFP leadership | IP, OEM contracts |
| Solvent & additive formulators | Specialty chemical firms | High-purity solvents, PFAS-free additives | Formulation know-how |
| Emerging regional entrants | US/EU capacity startups | Domestic supply localization | Policy incentives, offtake |
| Flow battery chemical suppliers | Vanadium/zinc electrolyte firms | Long-duration niche | Chemistry IP |
Differentiation rests on qualification status with tier-1 cell makers, vertical integration into lithium salt refining, and IP around next-generation formulations (LiFSI, silicon-carbon binders, PFAS-free additives).
Procurement of energy storage chemicals is mission-critical: a single electrolyte impurity can trigger cell failure and warranty claims. Buyers should prioritize suppliers with validated quality systems (IATF 16949, ISO 9001), demonstrated OEM qualification, and dual-region capacity to hedge geopolitical risk. Switching costs are high—requalification typically takes 18–36 months—so multi-year supply agreements with price-indexed lithium pass-through clauses are standard. Regulatory compliance (REACH, PFAS restrictions, EU Battery Regulation recycled-content thresholds) is becoming a gating criterion; suppliers without a credible PFAS-free additive roadmap will lose access to EU-facing OEMs by 2027.
The balance of evidence favors a selective-chemistry growth thesis: the specialty chemicals layer grows at 16%+ CAGR, but value capture concentrates in lithium salts and electrolytes, not commodity solvents. The strongest counter-argument is that sodium-ion and flow chemistries could displace lithium-ion chemical demand faster than expected in stationary storage—but our analysis suggests lithium-ion retains >60% share through 2033 given sunk gigafactory capacity.
Evidence that would change this conclusion: a breakthrough in solid-state electrolytes reaching commercial scale before 2028 would collapse demand for liquid electrolyte and separator chemicals, fundamentally altering the growth trajectory.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 16.3% from 2020-2034 |
| Segmentation |
|
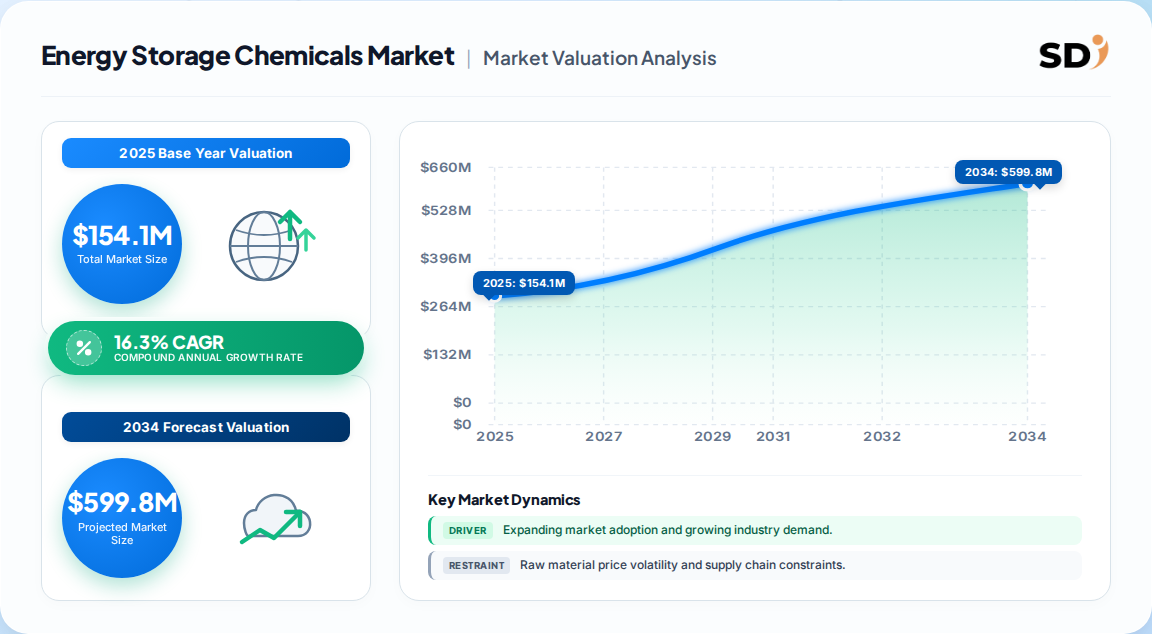
The global market was valued at approximately USD 154 million in 2025, according to our triangulated analysis. It is projected to reach USD 500.3 million by 2033.
The market is expected to grow at a compound annual growth rate (CAGR) of 16.3% from 2026 to 2033.
Asia Pacific held the largest revenue share of 46.2% in 2024, driven by China's integrated battery supply chain and rapid ESS deployment.
The market is segmented by product (lithium-ion battery, flow battery), technology (battery storage, flywheel), and end-use (automotive, utilities, industrial, commercial & residential).
Key players include integrated electrolyte producers, cathode active material specialists, and solvent formulators. The market is moderately to highly concentrated.
Growth is driven by renewable energy integration, EV adoption, government incentives, and the localization of critical material supply chains.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including raw material suppliers, specialty chemical producers, contract formulators, and global distributors. Decision-maker roles interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews validated capacity, pricing, qualification timelines, and demand visibility.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement Directors | 35% |
| Quality & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 45% |
| Formulators & Blenders | 35% |
| Distributors & Traders | 20% |
We triangulated primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and technical standards from recognized industry associations. This ensured our base-year sizing and growth assumptions are anchored to verifiable public data.
We employed simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) modeling. The two approaches were reconciled to produce a single consensus estimate for the base year and forecast horizon.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |