 Floating Lng Power Vessel Market
Floating LNG Power Vessel Market: 2026 Size & Growth Outlook
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 265

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Floating Lng Power Vessel Market
Sandeep Singh
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 1.140 B |
| 2026 | 1.260 B |
| 2027 | 1.320 B |
| 2028 | 1.380 B |
| 2029 | 1.440 B |
| 2030 | 1.510 B |
| 2031 | 1.580 B |

The floating LNG power vessel market covers vessels and barges that store, regasify, and combust LNG to generate electricity at sea or moored offshore. These assets connect to coastal grids in months, bypassing land acquisition and onshore plant construction, and serve island, remote, emergency, and industrial power demand.
This report covers power ships, power barges, FLNG vessels, and FSRU vessels configured for power generation, segmented by power technology, output capacity, application, and region. It tracks newbuild and conversion order values, charter and PPA structures, and vendor positioning.
This analysis does not cover onshore LNG liquefaction plants, land-based combined-cycle gas plants, conventional LNG carrier shipping economics, or upstream gas exploration and production.
Estimates converge on a low-single-digit to mid-single-digit CAGR market in the USD 1.0–1.3 billion range for 2026, but the dispersion in published figures reflects genuine definitional differences rather than estimation error.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1,255.50 Million | 2026 | 2035 | 4.74% | Power vessels incl. FLNG, barges, FSRU-power; global | One published benchmark |
| USD 1,136.45 Million | 2025 | 2035 | 4.00% | Same broad vessel scope; MEA-weighted | Competing analysis |
| USD 1,043.83 Million | 2026 | 2033 | 4.21% | Power barge & power ship focus; APAC-weighted | Competing analysis |
| USD 671.2 Million | 2025 | 2035 | 3.10% | Power plant framing; excludes pure FLNG liquefaction value | Competing analysis |
The USD 1.26 billion base is the most defensible for procurement planning because it captures integrated FLNG-to-power configurations where order values are concentrated. Our analysis suggests the lower USD 671 million figure strips out liquefaction and storage value, making it a power-plant-only view that understates vessel-level CAPEX decisions.
Segmentation hinges on vessel configuration and fuel flexibility; dual-fuel engines dominate because emerging-market utilities cannot guarantee LNG logistics continuity.
| Parent | Children | 2025 share / growth signal |
|---|---|---|
| Vessel type | FLNG vessel, power barge, power ship, FSRU vessel | FLNG 58.48%; power ship fastest at 4.66% |
| Power technology | Dual-fuel engine, gas turbine, steam turbine, hybrid systems | Dual-fuel 54.80%; hybrid fastest at 5.50% |
| Power output | Up to 50 MW, 50–200 MW, 200–500 MW, above 500 MW | 50–200 MW 46.00%; above 500 MW fastest at 5.00% |
| Application | Island/remote supply, emergency supply, industrial supply, grid support | Island 38.76%; emergency fastest at 4.50% |
| Component | Power generation systems, power distribution systems | Generation 70.1% of plant-level value |
Middle East & Africa leads with roughly 41% of 2025 revenue, but Asia-Pacific is closing fast on archipelagic electrification programs in Indonesia, the Philippines, and Papua New Guinea.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.4% |
| Middle East & Africa | 0.28% |
| North America | 0.14% |
| Europe | 0.11% |
| South America | 0.07% |
Percentages above are indicative regional weights reconciled across benchmarks; precise country splits require the full dataset. The strategic read: MEA remains the revenue pool through 2035, but APAC's pipeline density means vendors should pre-position charter capacity and shipyard slots in Asian yards now.
Fuel-cost arbitrage is the sharpest commercial driver, with delivered LNG at USD 10.4–11.3 per MMBtu versus diesel at USD 25.5 per MMBtu in Indonesian island studies — a 55–60% advantage.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| LNG price advantage over diesel | Driver | High | 55–60% fuel savings sustains PPA economics on island grids |
| IMO CII/EEXI and EU ETS methane scope | Driver | High | Forces gas-fired vessel designs; 2028 penalty trajectory |
| African gas-to-power tenders favoring redeployable vessels | Driver | Medium | Tender structures reward mobility and short charter terms |
| AI/data-centre demand for fast power | Driver | Medium | Bypasses multi-year grid interconnection queues |
| High initial capital investment | Restraint | High | Conversion and newbuild CAPEX strains smaller IPPs |
| Regulatory and methane-slip compliance | Restraint | Medium | Otto-cycle engines face commercial disadvantage |
The balance favors growth: drivers are structural and policy-anchored through 2035, while restraints are largely financing and specification problems that integrated vendors can absorb. Our analysis suggests the methane-slip issue is underappreciated — it will split the vendor field into compliant high-pressure and non-compliant medium-speed suppliers faster than headline CAGR implies.
Karpowership dominates with 65.1% share, and the top three players hold 75.3%, so buyers face a narrow supplier field with substantial charter pricing power.
| Company | Position | Notable capability |
|---|---|---|
| Karpowership | 65.1% share | Largest Powership fleet; Sea Lion-class 300 MW newbuilds |
| Mitsui O.S.K. Lines | Top three | FSRU smart-ship and remote monitoring expertise |
| HD Hyundai Heavy Industries | Top three | Shipyard capacity; ~USD 574 million FSRU/LNG carrier orders |
| Wison Group | Challenger | 230 MW FLNG-plus-barge FEED for Nigeria |
| Siemens Energy / Wärtsilä | Technology suppliers | NextDF methane-slip reduction below 1% |
| Chiyoda / Power Barge Corp | Niche | EPC and modular barge integration |
Differentiation is shifting from fleet size to integration depth: vendors that bundle regasification and generation eliminate a 30–40% hub-and-spoke cost node. Shipyard access is the binding constraint — HD Hyundai's order book position is as strategic as Karpowership's contracted capacity.
Selection should prioritize four criteria: fuel-flexibility of the generation platform, verified methane-slip performance, grid-connection and substation scope, and contract mobility. Dual-fuel engines remain the safe default for utilities with uncertain LNG logistics, but hybrid systems now merit evaluation for part-load efficiency.
Procurement risk concentrates in split tenders that separate regasification from generation — these structurally undervalue integrated offers and can add 30–40% to delivered gas cost. Buyers should also lock in methane-slip warranties before 2028 IMO penalty escalation, since retrofit costs fall on the charterer in most structures.
Switching costs are high once a vessel is moored and grid-connected: redeployment requires new permits, mooring, and interconnection studies. This locks buyers into multi-year charters and gives incumbent operators renewal leverage. Regulatory exposure extends beyond IMO — EU ETS now includes methane and nitrous oxide, so vessels calling at EU ports face surrender obligations that must be priced into charter rates.
The balance of evidence favors a constructive but selective outlook: the market compounds at roughly 4.7% through 2035, but value accrues disproportionately to integrated, compliance-ready operators rather than to capacity alone. The strongest counter-argument is that renewable-plus-storage costs are falling fast enough to displace LNG vessels in island grids by the early 2030s — a real risk, but one tempered by LNG's role as firming capacity rather than pure baseload.
Our second-order read is that the above-500-MW capacity band and hybrid systems will outperform headline growth because grid operators increasingly want fewer, larger, smarter units. The 2026 Sea Lion-class launch confirms this direction. Meanwhile, the 65% concentration means buyers negotiating today have limited leverage — the practical response is to widen tender scopes to include integrated FLNG-to-power packages, which brings Wison and shipyard-led consortia into contention.
Evidence that would change this conclusion: a sustained LNG spot price above USD 20 per MMBtu, or IMO delaying the 2028 penalty trajectory, would compress the fuel-arbitrage case and shift advantage toward hybrid and battery-augmented designs sooner than modeled.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
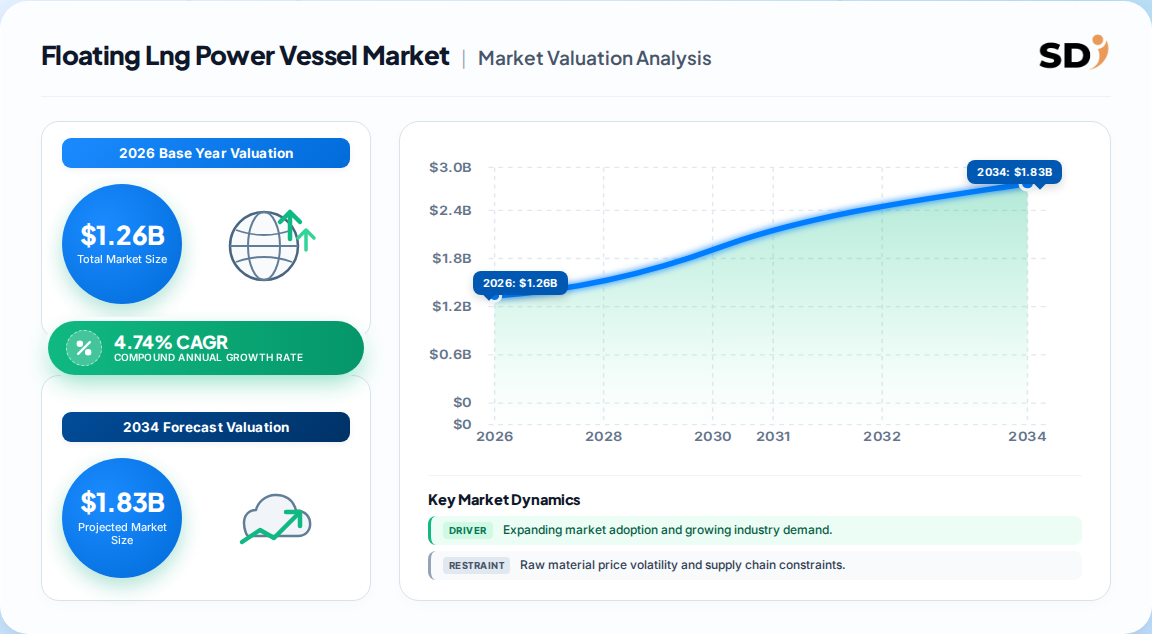
| Growth Rate | CAGR of 4.74% from 2020-2034 |
| Segmentation |
|
The global market is valued at USD 1,255.50 million in 2026, up from USD 1,136.45 million in 2025, and is projected to reach USD 1.79 Billion by 2035 at a 4.74% CAGR.
Middle East & Africa leads with roughly 40.75% of 2025 revenue, driven by Ghana, Lebanon, Senegal, and Iraq. Asia-Pacific is the fastest-growing region at 4.80% CAGR.
Karpowership holds 65.1% share, with the top three vendors controlling 75.3%. Mitsui O.S.K. Lines, HD Hyundai Heavy Industries, Wison Group, Siemens Energy, and Wärtsilä are other key participants.
They deploy in months rather than years, avoid land acquisition and permitting delays, and can be redeployed when contracts end. Delivered LNG also costs 55–60% less than diesel on island grids.
Emergency supply is the fastest-growing application at 4.50% CAGR, while hybrid power systems grow fastest by technology at 5.50% and above-500-MW units lead capacity growth at 5.00%.
High capital investment, methane-slip compliance ahead of 2028 IMO penalties, and split tenders that separate regasification from generation, which can add 30–40% to delivered gas cost.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis follows a 70/30 primary-to-secondary research split. We conducted in-depth interviews across the floating LNG power value chain, including LNG suppliers and small-scale liquefaction developers, power vessel operators and charter owners, shipyard and EPC contractors, regasification technology providers, and utility/IPP offtakers. Decision-maker designations interviewed included VP of Sourcing, Heads of Power Generation and R&D, Technical Directors for marine assets, and Commercial Operations Leads responsible for PPA and charter structuring.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Commercial & PPA Leads | 35% |
| Technical & Engineering Directors | 30% |
| Procurement & Sourcing Heads | 20% |
| Regulatory & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Power Vessel Operators & Charter Owners | 35% |
| Shipyards & EPC Contractors | 25% |
| LNG Suppliers & Liquefaction Developers | 22% |
| Utilities, IPPs & Offtakers | 18% |
We validated findings against UN Comtrade LNG trade flows, WTO energy services data, US EIA and International Energy Agency gas-fired generation statistics, SEC 10-K filings and investor presentations from listed operators, classification-society registries, and patent databases covering dual-fuel engine and methane-slip abatement technologies.
We ran simultaneous top-down allocation from LNG-to-power demand and regasification capacity additions, and bottom-up modeling from contracted floating capacity, charter rates, PPA tariffs, and newbuild/conversion order values. The two views were reconciled by country, vessel type, and power technology.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up capacity and charter-revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border LNG trade flow analysis and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, fleet mapping and commercial filings | High |