 Energy Utilities Analytics Market
: 2025 Size & 2033 Forecast
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 203

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Energy Utilities Analytics Market
Sandeep Singh
Research Analyst

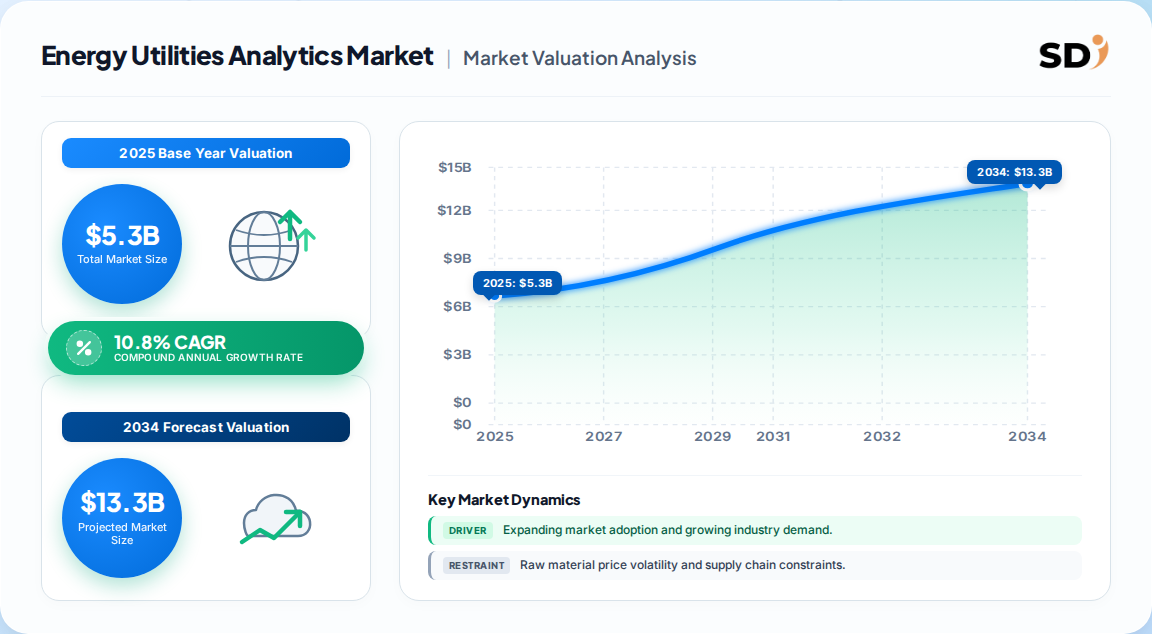
| Year | Market Size |
|---|---|
| 2025 | 5.300 B |
| 2026 | 5.800 B |
| 2027 | 6.400 B |
| 2028 | 7.100 B |
| 2029 | 7.900 B |
| 2030 | 8.700 B |
| 2031 | 9.700 B |

The energy utilities analytics market covers software and services that convert operational, metering, and grid data into decisions — spanning load forecasting, predictive asset maintenance, grid optimization, demand response, and customer analytics. It serves electricity, gas, and water utilities, transmission and distribution operators, and retail suppliers worldwide.
This report covers global energy and utility analytics software platforms and associated professional and managed services across electricity, gas, and water utilities, T&D operators, and retail suppliers. It analyzes component, deployment mode, organization size, utility type, application, and region.
This analysis does not cover smart-meter hardware, SCADA hardware, physical grid equipment, general-purpose BI tools sold outside utility verticals, or enterprise ERP systems unless bundled into a utility analytics deployment.
Estimates for 2025–2026 cluster between USD 4.5 billion and USD 5.9 billion, with the divergence driven mainly by scope — whether metering hardware, adjacent cybersecurity software, and utility-specific managed services are included.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 5.3B → USD 11.9B | 2025 | 2033 | 10.8% | Analytics software + services across electricity, gas, water; excludes hardware | One published estimate |
| USD 5.87B → USD 9.05B | 2026 | 2031 | 9.03% | Utility analytics incl. meter ops, forecasting, demand response; medium concentration | A competing analysis |
| USD 4.55B → USD 15.39B | 2025 | 2034 | 14.49% | Includes utility-specific cybersecurity analytics and cloud services | Alternate published estimate |
Our analysis suggests the 10.8% mid-path is the most defensible baseline: it aligns with observed smart-meter data growth, IEA grid-capacity needs (+30% by 2035), and installed software-plus-services revenue trends. The 14.49% path appears to fold in adjacent cybersecurity and cloud spend, while the 9.03% path under-weights services acceleration. Buyers should anchor on ~10–11% CAGR and stress-test scenarios ±200 bps.
The market segments by component, deployment mode, organization size, utility type, and application — with services and cloud/hybrid the fastest-growing lines.
| Parent Segment | Children |
|---|---|
| By Component | Solutions (analytics platforms, dashboards), Services (consulting, integration, managed services) |
| By Deployment Mode | On-premises, Cloud, Hybrid |
| By Organization Size | Large enterprises, SMEs |
| By Utility Type | Electricity, Gas, Water, Multi-utility |
| By Application | Grid & network optimization, Meter operations & data management, Load & generation forecasting, Predictive asset maintenance, Demand response, Customer analytics |
Solutions captured ~66.9% of 2025 revenue, but services grew at ~12.2% CAGR in one competing analysis — a signal that integration complexity, not license demand, is the binding growth constraint. Meter operations remains the largest single application (~31.6%); demand response the fastest (~13.9% CAGR). Electricity utilities hold ~70% of utility-type revenue.
North America leads with roughly 37–38% of global revenue in 2025, followed by Europe and Asia-Pacific — the latter being the fastest-growing region at nearly 10% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.26% |
| Asia-Pacific | 0.24% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
| Parent Region | Key Countries |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain, Nordics |
| Asia Pacific | China, Japan, India, South Korea, Australia |
| Latin America | Brazil, Mexico, Argentina, Chile |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Nigeria |
North America's lead rests on ~146 million installed smart meters (projected ~183 million by 2029), federal grid-modernization funding, and a dense vendor ecosystem. Asia-Pacific's growth is driven by India's 250-million-meter tender, China's grid digitization, and Australian five-minute settlement rules that penalize forecast error. Europe sits between — high renewable penetration and decarbonization mandates offset by fragmented national utility markets.
Growth is driven by AI-driven predictive analytics, renewable integration, and meter-data scale; restrained by legacy OT-IT integration costs, data silos, and power-domain data-science talent shortages.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| AI-driven predictive analytics | Driver | High | Predictive maintenance and load forecasting yield measurable outage and cost savings; +~2.1% CAGR impact |
| Renewable mandates & decarbonization | Driver | High | Stochastic optimization needed for variable generation; EU and California statutes |
| AMI 2.0 & edge analytics | Driver | High | Meter data volumes require real-time validation and segmentation |
| Wholesale-price volatility | Driver | Medium | 1% day-ahead accuracy gain ≈ USD 5M in ERCOT balancing savings |
| Legacy OT-IT integration costs | Restraint | High | Proprietary SCADA protocols resist cloud, AI, and IoT integration; −~1.4% CAGR impact |
| Data-science talent shortage | Restraint | Medium | Power-domain expertise scarce in APAC and Africa; −~1.1% CAGR impact |
| Cybersecurity / data sovereignty | Restraint | Medium | Compliance mandates slow cross-border cloud adoption; −~0.8% CAGR impact |
Our analysis suggests drivers currently outweigh restraints by roughly 2:1 on a CAGR-impact basis, but the balance is region-specific. In North America and Europe, integration and cybersecurity friction will cap near-term growth; in Asia-Pacific, talent and data quality are the binding constraints. The net implication: vendors that bundle integration and managed services with analytics capture more value than those selling pure software.
The market is moderately fragmented, with large technology and cloud providers, specialized utility-software vendors, and consultancies competing across overlapping functional niches.
| Vendor | Positioning | Primary Strength |
|---|---|---|
| Oracle | Enterprise utility suite | Meter data management, billing, and analytics integration |
| IBM | AI and cloud platform | Watson-driven analytics, hybrid cloud, and utility consulting |
| Siemens | Industrial and grid software | Grid optimization, digital twins, and OT integration |
| Schneider Electric | Energy management | Demand-side analytics, microgrid and DER orchestration |
| SAP | Enterprise ERP + analytics | Utility billing, asset management, and financial analytics convergence |
Differentiation is shifting from feature depth to ecosystem breadth: integration with SCADA, ADMS, and AMI ecosystems determines deployment speed. Incumbents leverage installed bases; start-ups carve niches in virtual power plant orchestration, transformer health scoring, and condition-based maintenance. Partnerships with systems integrators are becoming the primary channel for mid-size utility wins.
Selection criteria should prioritize interoperability over feature breadth. Utilities that buy analytics without validating SCADA, AMI, and ADMS integration paths face 6–12 month deployment delays and hidden services costs that can exceed license fees.
Procurement risk concentrates in three areas: data migration from fragmented legacy systems, cybersecurity compliance across OT and IT boundaries, and vendor lock-in on proprietary data models. Buyers should require contract terms covering data portability, open APIs (e.g., IEEE 2030.5 alignment), and exit assistance.
Switching costs are high — typically 18–24 months and 40–60% of initial deployment value — so first-vendor selection is the most consequential decision. Regulatory compliance (NERC CIP, EU NIS2, data-residency rules) should be validated as a gating requirement, not a post-selection checklist item.
Actionable callout: Require a proof-of-value on at least one live grid or metering use case before signing enterprise-wide licenses. This de-risks both integration and time-to-value.
The balance of evidence favors a mid-path 10–11% CAGR through 2033, with total market value roughly doubling to USD 11–12 billion. The competing 14.5% estimate is plausible only if cybersecurity analytics and cloud services are fully consolidated into scope — a definitional stretch most buyers should discount. Conversely, the 9.0% path likely understates services growth, which is accelerating as utilities outsource integration.
The strongest counter-argument: AI-driven productivity gains could compress software license prices faster than volumes grow, muting nominal revenue even as deployments expand. Our analysis suggests this is a 2028+ risk, not a 2026 one — installed-base inertia and multi-year contracts protect near-term revenue. A secondary counter: talent shortages could delay deployments enough to push growth toward the 9% path in APAC.
Actionable strategy:
What would change our conclusion: a sustained drop in utility capex (e.g., grid-modernization funding cuts) or a step-change in AI model costs that collapses license pricing. Either would compress growth toward 7–8% and shift value decisively toward services and integration players.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.8% from 2020-2034 |
| Segmentation |
|
The global energy and utilities analytics market was valued at approximately USD 5.3 billion in 2025 and is projected to reach USD 11.9 billion by 2033, growing at a 10.8% CAGR from 2026 to 2033.
North America leads with roughly 37–38% of global revenue in 2025, supported by smart-meter penetration, grid-modernization funding, and a dense vendor ecosystem. Asia-Pacific is the fastest-growing region.
The market segments by component (solutions, services), deployment (on-premises, cloud, hybrid), organization size, utility type (electricity, gas, water), and application, with grid optimization and meter operations the largest applications.
AI-driven predictive analytics, renewable integration, AMI 2.0 rollouts, and wholesale-price volatility are the primary growth drivers, offset by legacy OT-IT integration costs, data silos, and power-domain talent shortages.
Leading vendors include Oracle, IBM, Siemens, Schneider Electric, and SAP, alongside specialized analytics providers and virtual-power-plant start-ups competing in niches like transformer health scoring and condition-based maintenance.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, with in-depth interviews across the energy analytics value chain. We conducted structured interviews with utility software platform providers, systems integrators, metering and sensor vendors, cloud infrastructure providers, and utility analytics consultancies. Decision-maker designations interviewed include VP of Digital Transformation, Head of Grid Analytics, Chief Information Security Officer, and Commercial Operations Leads at transmission and distribution operators.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Digital Transformation & Analytics Leads | 35% |
| Grid Operations & Asset Managers | 30% |
| Cybersecurity & Compliance Officers | 20% |
| Procurement & Commercial Operations | 15% |
| Company Type | Representation (%) |
|---|---|
| Utility Software & Platform Providers | 40% |
| Cloud & Technology Providers | 25% |
| Systems Integrators & Consultancies | 20% |
| Metering & Sensor Vendors | 15% |
We corroborate primary findings against official multilateral trade databases (UN Comtrade, WTO, Eurostat), corporate filings (10-K, SEC filings, annual investor presentations), patent databases, and recognized standards bodies including IEEE (2030.5), NERC, and the IEA. No competitor market research is used in validation.
We triangulate simultaneously from the top down (macro grid-investment allocation, utility IT budgets, regional electrification forecasts) and bottom up (vendor revenue, deployment counts, installed meter bases, and per-seat pricing). Divergences are reconciled against public utility disclosures.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |