Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Subsea Power Grid Systems Market Outlook 2026
Subsea Power Grid Systems Market
Subsea Power Grid Systems Market Outlook 2026
Subsea Power Grid Systems Market by Component (Cables, Variable-Speed Drives, Transformers, Switchgear, Connectors, Other Components), by Power-Generation Source (Captive Generation, Offshore Wind, Tidal and Wave Energy, Others), by Installation Depth (Shallow Water, Deepwater, Ultra-Deep), by Voltage Rating (Medium Voltage, High Voltage, Extra-High Voltage), by End-User Industry (Oil and Gas Upstream, Offshore Wind Farm Developers, Utility Companies, Government Organizations, Research Institutions), by North America (USA, Canada, Mexico), by Europe (Germany, UK, Norway, Netherlands, France), by Asia Pacific (China, Japan, South Korea, India), by Latin America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 245
Sandeep Singh
Research Analyst
Subsea Power Grid Systems Market Outlook 2026
Key Takeaways
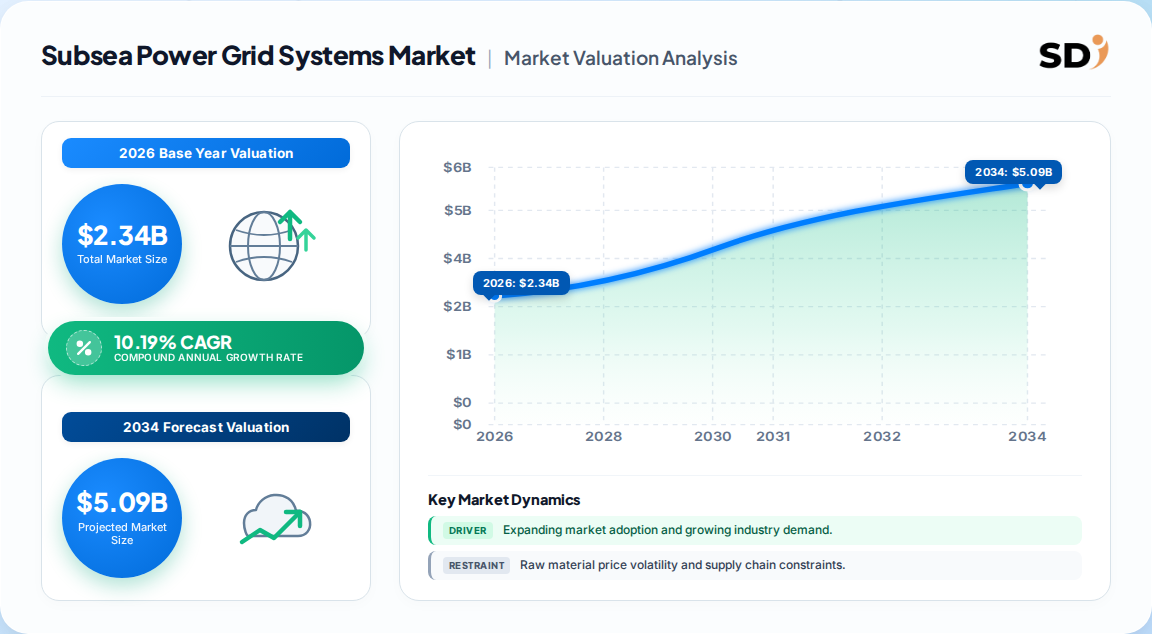
The Subsea Power Grid Systems Market is valued at USD 2.34 billion in 2026 and is projected to reach USD 3.79 billion by 2031, a 10.19% CAGR.
Cables dominate component share at 54.45%, while variable-speed drives grow fastest at 12.08% through 2031.
Captive generation holds 51.65% of 2025 revenue; offshore wind is the fastest-growing source at 13.55% CAGR.
Europe leads with 40.12% revenue share; Asia-Pacific is the fastest-growing region at 12.78% CAGR.
Key players include Prysmian Group, Nexans SA, NKT A/S, ABB Ltd and Siemens Energy AG, with medium market concentration.
Why this matters for decision-makers: Vendors must pivot toward integrated HVDC and modular wet-mate solutions to avoid margin compression as offshore wind becomes the dominant demand engine.
Subsea Power Grid Systems Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.120 B
2025
2.340 B
2026
2.580 B
2027
2.840 B
2028
3.130 B
2029
3.450 B
2030
3.790 B
2031
Subsea Power Grid Systems Market Size (In Billion)
Year
Market Size
2025
2.120 B
2026
2.340 B
2027
2.580 B
2028
2.840 B
2029
3.130 B
2030
3.450 B
2031
3.790 B
What is the Subsea Power Grid Systems Market?
The Subsea Power Grid Systems Market encompasses underwater electrical infrastructure—cables, transformers, switchgear, variable-speed drives and connectors—that transmits and distributes power between offshore installations, islands and onshore grids. These systems enable efficient, safe energy transfer over long distances, supporting offshore wind, oil and gas electrification and cross-border interconnections.
Scope: what this report covers and excludes
This analysis covers the global Subsea Power Grid Systems Market, segmented by component, power-generation source, installation depth, voltage rating, end-user industry and geography, with a base year of 2025 and forecast to 2031. This analysis does not cover onshore power grid systems, subsea telecommunications cables, or standalone subsea processing equipment.
How big is the market for Subsea Power Grid Systems Market?
The Subsea Power Grid Systems Market is estimated at USD 2.34 billion in 2026, with divergent estimates reflecting differing scope definitions and base-year assumptions.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 2.34 Billion
2026
2031
10.19%
Subsea power grid components and systems, global
One published estimate
USD 3.77 Billion
2025
2030
9.3–9.5%
Broader subsea power grid systems, global
A competing analysis
USD 2.50 Billion
2026
2035
9.5%
Subsea power grid by generation type, global
Alternative industry benchmark
USD 1.9 Billion
2024
2034
10.7%
Subsea power grid systems, global
Another published estimate
Our analysis suggests the USD 2.34 billion figure is the most defensible for 2026 because it aligns with the most granular component-level disaggregation and explicit 2025 base-year benchmarks. The higher USD 3.77 billion estimate likely includes broader offshore transmission assets beyond subsea grid systems. The lower USD 1.9 billion figure may reflect a narrower scope excluding certain connector and drive categories. This divergence implies buyers should scrutinize scope definitions when comparing vendor addressable markets.
How is the market segmented?
The Subsea Power Grid Systems Market is segmented by component, power-generation source, installation depth, voltage rating and end-user industry, with cables and captive generation dominating current revenue.
Parent Segment
Children
By Component
Cables, Variable-Speed Drives, Transformers, Switchgear, Connectors, Other Components
By Power-Generation Source
Captive Generation, Offshore Wind, Tidal and Wave Energy, Others
By Installation Depth
Shallow Water (below 100m), Deepwater (100–1,000m), Ultra-Deep (above 1,000m)
By Voltage Rating
Medium Voltage, High Voltage (60–150 kV), Extra-High Voltage (above 150 kV)
By End-User Industry
Oil and Gas Upstream, Offshore Wind Farm Developers, Utility Companies, Government Organizations, Research Institutions
Cables accounted for 54.45% of 2025 share, driven by their role as the physical backbone spanning hundreds of kilometers. High-voltage systems led with 48.95% revenue, while extra-high-voltage systems are expected to grow at 11.49% CAGR as 525 kV HVDC standardization accelerates.
Which region leads in Subsea Power Grid Systems Market?
Europe leads the Subsea Power Grid Systems Market with 40.12% revenue share in 2025, supported by North Sea grid build-out and HVDC standardization, while Asia-Pacific is the fastest-growing region at 12.78% CAGR.
Subsea Power Grid Systems Market Regional Market Share
Loading chart...
Subsea Power Grid Systems Market Regional Market Share
Region
Market Share (%)
Europe
0.4%
Asia-Pacific
0.24%
North America
0.2%
Middle East & Africa
0.09%
South America
0.07%
Global
Europe (Germany, UK, Norway, Netherlands, France)
Asia-Pacific (China, Japan, South Korea, India)
North America (USA, Canada, Mexico)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
South America (Brazil, Argentina)
Region
2025 Share
Europe
40.12%
Asia-Pacific
24.00%
North America
20.00%
Middle East & Africa
9.00%
South America
6.88%
Europe's leadership is anchored by TenneT's 2 GW program standardizing 525 kV HVDC connections with framework agreements near EUR 23 billion. Asia-Pacific's growth reflects Chinese, Korean and Japanese offshore wind pipelines and cable manufacturing scale. Our analysis suggests Europe's share will gradually erode as Asia-Pacific capacity comes online, but Europe will retain technology leadership in extra-high-voltage and deepwater applications through 2031.
What is driving growth — and what is holding it back?
Offshore wind HVDC demand, offshore asset electrification and floating wind build-out are the primary growth drivers, while raw material volatility and vessel bottlenecks constrain near-term expansion.
The balance of evidence favors growth, with drivers collectively adding over 9 percentage points to baseline CAGR. However, the vessel bottleneck is the most underappreciated constraint: our analysis suggests installation capacity, not manufacturing capacity, will determine which projects reach FID on schedule through 2028. This implies buyers should secure vessel slots early and favor vendors with integrated installation partnerships.
Who are the leading vendors?
Prysmian Group, Nexans SA, NKT A/S, ABB Ltd and Siemens Energy AG lead the Subsea Power Grid Systems Market, with medium concentration and differentiation centered on HVDC cable capability and integrated system engineering.
Company
Primary Strength
Differentiator
Prysmian Group
Subsea cables and HVDC
Largest cable manufacturing footprint; 525 kV qualification
Nexans SA
Subsea cables and interconnectors
Strong European utility relationships
NKT A/S
High-voltage cables
Extra-high-voltage cable leadership
ABB Ltd
Power electronics and VFDs
Integrated drive and converter systems
Siemens Energy AG
Subsea power grid modules
Wet-mate switchgear and pressure-compensated modules
Competitive moats rest on qualification cycles—typically 3–5 years—and reference installations. Our analysis suggests cable suppliers hold the strongest bargaining position, but integrated system providers like Siemens Energy are gaining leverage as operators shift procurement from components to availability-guaranteed systems. Vendors unable to offer 300km+ corridor performance guarantees risk marginalization.
What do buyers and operators need to know?
Buyers must prioritize total lifecycle cost over unit pricing, evaluating vendors on availability guarantees, wet-mate modularity and HVDC qualification depth for 300km+ corridors.
Procurement risk is concentrated in cable reliability—insurance data shows cable faults constitute 80% of offshore wind claims—making fatigue life, corrosion resistance and distributed fibre-optic sensing critical selection criteria. Switching costs are high due to 3–5 year qualification cycles and proprietary connector interfaces, so buyers should negotiate interoperability clauses early. Regulatory compliance with EU Offshore Renewable Energy Strategy targets and Norway's carbon pricing regime increasingly favors grid-connected solutions over onboard generation. Our analysis suggests buyers should demand performance-based contracts tied to availability rather than capex minimization.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish medium-term outlook, with the Subsea Power Grid Systems Market compounding at roughly 10% annually through 2031. The strongest counter-argument is that vessel and cable factory bottlenecks could cap growth below consensus, particularly if US offshore wind policy reverses. However, European HVDC standardization and Asia-Pacific scale-up provide sufficient demand diversification to offset regional policy risk.
Our analysis suggests the market is transitioning from a component-sales model to an availability-guaranteed systems model. Vendors that can bundle extra-high-voltage cables, wet-mate switchgear and digital monitoring into performance contracts will capture disproportionate margin, while pure component suppliers face pricing pressure. The TenneT 2 GW program exemplifies this shift, with framework agreements favoring integrated providers.
Actionable Strategy 1: Investors should prioritize companies with 525 kV HVDC qualification and wet-mate switchgear portfolios, as these align with the fastest-growing extra-high-voltage and offshore wind segments.
Actionable Strategy 2: Operators should lock in vessel and cable factory slots 24–36 months ahead of FID to mitigate the installation bottleneck.
Actionable Strategy 3: Vendors should invest in distributed fibre-optic sensing and modular switchgear to differentiate on reliability and installed cost.
Evidence that would change our conclusion: a sustained decline in European offshore wind leasing rounds below 5 GW annually, or a breakthrough in onshore long-duration storage that reduces offshore wind economics.
Subsea Power Grid Systems Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Subsea Power Grid Systems Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.19% from 2020-2034
Segmentation
By Component
Cables
Variable-Speed Drives
Transformers
Switchgear
Connectors
Other Components
By Power-Generation Source
Captive Generation
Offshore Wind
Tidal and Wave Energy
Others
By Installation Depth
Shallow Water
Deepwater
Ultra-Deep
By Voltage Rating
Medium Voltage
High Voltage
Extra-High Voltage
By End-User Industry
Oil and Gas Upstream
Offshore Wind Farm Developers
Utility Companies
Government Organizations
Research Institutions
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
Norway
Netherlands
France
Asia Pacific
China
Japan
South Korea
India
Latin America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Cables
5.1.2. Variable-Speed Drives
5.1.3. Transformers
5.1.4. Switchgear
5.1.5. Connectors
5.1.6. Other Components
5.2. Market Analysis, Insights and Forecast - by Power-Generation Source
5.2.1. Captive Generation
5.2.2. Offshore Wind
5.2.3. Tidal and Wave Energy
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by Installation Depth
5.3.1. Shallow Water
5.3.2. Deepwater
5.3.3. Ultra-Deep
5.4. Market Analysis, Insights and Forecast - by Voltage Rating
5.4.1. Medium Voltage
5.4.2. High Voltage
5.4.3. Extra-High Voltage
5.5. Market Analysis, Insights and Forecast - by End-User Industry
5.5.1. Oil and Gas Upstream
5.5.2. Offshore Wind Farm Developers
5.5.3. Utility Companies
5.5.4. Government Organizations
5.5.5. Research Institutions
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Cables
6.1.2. Variable-Speed Drives
6.1.3. Transformers
6.1.4. Switchgear
6.1.5. Connectors
6.1.6. Other Components
6.2. Market Analysis, Insights and Forecast - by Power-Generation Source
6.2.1. Captive Generation
6.2.2. Offshore Wind
6.2.3. Tidal and Wave Energy
6.2.4. Others
6.3. Market Analysis, Insights and Forecast - by Installation Depth
6.3.1. Shallow Water
6.3.2. Deepwater
6.3.3. Ultra-Deep
6.4. Market Analysis, Insights and Forecast - by Voltage Rating
6.4.1. Medium Voltage
6.4.2. High Voltage
6.4.3. Extra-High Voltage
6.5. Market Analysis, Insights and Forecast - by End-User Industry
6.5.1. Oil and Gas Upstream
6.5.2. Offshore Wind Farm Developers
6.5.3. Utility Companies
6.5.4. Government Organizations
6.5.5. Research Institutions
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Cables
7.1.2. Variable-Speed Drives
7.1.3. Transformers
7.1.4. Switchgear
7.1.5. Connectors
7.1.6. Other Components
7.2. Market Analysis, Insights and Forecast - by Power-Generation Source
7.2.1. Captive Generation
7.2.2. Offshore Wind
7.2.3. Tidal and Wave Energy
7.2.4. Others
7.3. Market Analysis, Insights and Forecast - by Installation Depth
7.3.1. Shallow Water
7.3.2. Deepwater
7.3.3. Ultra-Deep
7.4. Market Analysis, Insights and Forecast - by Voltage Rating
7.4.1. Medium Voltage
7.4.2. High Voltage
7.4.3. Extra-High Voltage
7.5. Market Analysis, Insights and Forecast - by End-User Industry
7.5.1. Oil and Gas Upstream
7.5.2. Offshore Wind Farm Developers
7.5.3. Utility Companies
7.5.4. Government Organizations
7.5.5. Research Institutions
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Cables
8.1.2. Variable-Speed Drives
8.1.3. Transformers
8.1.4. Switchgear
8.1.5. Connectors
8.1.6. Other Components
8.2. Market Analysis, Insights and Forecast - by Power-Generation Source
8.2.1. Captive Generation
8.2.2. Offshore Wind
8.2.3. Tidal and Wave Energy
8.2.4. Others
8.3. Market Analysis, Insights and Forecast - by Installation Depth
8.3.1. Shallow Water
8.3.2. Deepwater
8.3.3. Ultra-Deep
8.4. Market Analysis, Insights and Forecast - by Voltage Rating
8.4.1. Medium Voltage
8.4.2. High Voltage
8.4.3. Extra-High Voltage
8.5. Market Analysis, Insights and Forecast - by End-User Industry
8.5.1. Oil and Gas Upstream
8.5.2. Offshore Wind Farm Developers
8.5.3. Utility Companies
8.5.4. Government Organizations
8.5.5. Research Institutions
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Cables
9.1.2. Variable-Speed Drives
9.1.3. Transformers
9.1.4. Switchgear
9.1.5. Connectors
9.1.6. Other Components
9.2. Market Analysis, Insights and Forecast - by Power-Generation Source
9.2.1. Captive Generation
9.2.2. Offshore Wind
9.2.3. Tidal and Wave Energy
9.2.4. Others
9.3. Market Analysis, Insights and Forecast - by Installation Depth
9.3.1. Shallow Water
9.3.2. Deepwater
9.3.3. Ultra-Deep
9.4. Market Analysis, Insights and Forecast - by Voltage Rating
9.4.1. Medium Voltage
9.4.2. High Voltage
9.4.3. Extra-High Voltage
9.5. Market Analysis, Insights and Forecast - by End-User Industry
9.5.1. Oil and Gas Upstream
9.5.2. Offshore Wind Farm Developers
9.5.3. Utility Companies
9.5.4. Government Organizations
9.5.5. Research Institutions
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Cables
10.1.2. Variable-Speed Drives
10.1.3. Transformers
10.1.4. Switchgear
10.1.5. Connectors
10.1.6. Other Components
10.2. Market Analysis, Insights and Forecast - by Power-Generation Source
10.2.1. Captive Generation
10.2.2. Offshore Wind
10.2.3. Tidal and Wave Energy
10.2.4. Others
10.3. Market Analysis, Insights and Forecast - by Installation Depth
10.3.1. Shallow Water
10.3.2. Deepwater
10.3.3. Ultra-Deep
10.4. Market Analysis, Insights and Forecast - by Voltage Rating
10.4.1. Medium Voltage
10.4.2. High Voltage
10.4.3. Extra-High Voltage
10.5. Market Analysis, Insights and Forecast - by End-User Industry
10.5.1. Oil and Gas Upstream
10.5.2. Offshore Wind Farm Developers
10.5.3. Utility Companies
10.5.4. Government Organizations
10.5.5. Research Institutions
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Subsea Power Grid Systems Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Subsea Power Grid Systems Market Revenue (Billion), by Component 2026 & 2034
Figure 3: North America Subsea Power Grid Systems Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Subsea Power Grid Systems Market Revenue (Billion), by Power-Generation Source 2026 & 2034
Figure 5: North America Subsea Power Grid Systems Market Revenue Share (%), by Power-Generation Source 2026 & 2034
Figure 6: North America Subsea Power Grid Systems Market Revenue (Billion), by Installation Depth 2026 & 2034
Figure 7: North America Subsea Power Grid Systems Market Revenue Share (%), by Installation Depth 2026 & 2034
Figure 8: North America Subsea Power Grid Systems Market Revenue (Billion), by Voltage Rating 2026 & 2034
Figure 9: North America Subsea Power Grid Systems Market Revenue Share (%), by Voltage Rating 2026 & 2034
Figure 10: North America Subsea Power Grid Systems Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 11: North America Subsea Power Grid Systems Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 12: North America Subsea Power Grid Systems Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Subsea Power Grid Systems Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Subsea Power Grid Systems Market Revenue (Billion), by Component 2026 & 2034
Figure 15: Europe Subsea Power Grid Systems Market Revenue Share (%), by Component 2026 & 2034
List of Tables
Table 1: Subsea Power Grid Systems Market Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Subsea Power Grid Systems Market Revenue Billion Forecast, by Power-Generation Source 2020 & 2034
Table 3: Subsea Power Grid Systems Market Revenue Billion Forecast, by Installation Depth 2020 & 2034
Table 4: Subsea Power Grid Systems Market Revenue Billion Forecast, by Voltage Rating 2020 & 2034
Table 5: Subsea Power Grid Systems Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 6: Subsea Power Grid Systems Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Subsea Power Grid Systems Market Revenue Billion Forecast, by Component 2020 & 2034
Table 8: North America Subsea Power Grid Systems Market Revenue Billion Forecast, by Power-Generation Source 2020 & 2034
Table 9: North America Subsea Power Grid Systems Market Revenue Billion Forecast, by Installation Depth 2020 & 2034
Table 10: North America Subsea Power Grid Systems Market Revenue Billion Forecast, by Voltage Rating 2020 & 2034
Table 11: North America Subsea Power Grid Systems Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 12: North America Subsea Power Grid Systems Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Subsea Power Grid Systems Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Subsea Power Grid Systems Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Subsea Power Grid Systems Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the Subsea Power Grid Systems Market size in 2026?
The Subsea Power Grid Systems Market is valued at USD 2.34 billion in 2026, growing at a 10.19% CAGR to reach USD 3.79 billion by 2031, driven by offshore wind and oil and gas electrification.
2. Which region leads the Subsea Power Grid Systems Market?
Europe leads with 40.12% revenue share in 2025, supported by North Sea grid build-out and HVDC standardization, while Asia-Pacific is the fastest-growing region at 12.78% CAGR.
3. What are the key drivers of the Subsea Power Grid Systems Market?
Offshore wind HVDC export-cable demand, offshore oil and gas platform electrification to cut Scope-1 emissions, and floating wind build-out beyond 60m depths are the primary growth drivers.
4. Who are the leading vendors in the Subsea Power Grid Systems Market?
Prysmian Group, Nexans SA, NKT A/S, ABB Ltd and Siemens Energy AG are the major companies, with medium market concentration and differentiation centered on HVDC cable capability and integrated systems.
5. What is the fastest-growing segment in the Subsea Power Grid Systems Market?
Offshore wind is the fastest-growing power-generation source at 13.55% CAGR, while variable-speed drives are the fastest-growing component at 12.08% through 2031.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary research split, prioritizing direct industry engagement. We conducted in-depth interviews with stakeholders across the value chain, including subsea cable manufacturers, power electronics producers, offshore EPC contractors, installation vessel operators and utility procurement teams. Decision-maker designations interviewed included VP of Subsea Engineering, Heads of Offshore Procurement, Technical Directors for HVDC Systems and Commercial Operations Leads, ensuring granular insight into specification, qualification and purchasing behavior.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Subsea Engineering & Technical Directors
40%
Offshore Procurement & Sourcing Leads
35%
Commercial Operations & Strategy Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Subsea Cable & Component Manufacturers
40%
Offshore EPC & Installation Contractors
30%
Utility & Offshore Wind Developers
20%
Power Electronics & Drive Suppliers
10%
Secondary Benchmarking & Public Trade Validation
We triangulated primary findings against official multilateral trade databases (UN Comtrade, Eurostat, US ITC), corporate annual filings (10-K, SEC filings, investor presentations), patent databases and recognized industry associations including the Global Wind Energy Council (GWEC), the European Network of Transmission System Operators for Electricity (ENTSO-E) and DNV technical standards. This validation anchored our estimates to verifiable public benchmarks.
Demand Modeling & Market Sizing Triangulation
Our market sizing applies simultaneous top-down and bottom-up triangulation. The top-down approach allocates macroeconomic offshore energy capex across subsea grid components using project-level FID tracking. The bottom-up approach models manufacturer capacity, product pricing and end-use consumption by segment. Divergences are reconciled through scenario weighting by region and installation depth.
 Subsea Power Grid Systems Market