 Us Electric Fireplace Market
US Electric Fireplace Market: Size, Trends & Forecast 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 203

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Electric Fireplace Market
Sandeep Singh
Research Analyst

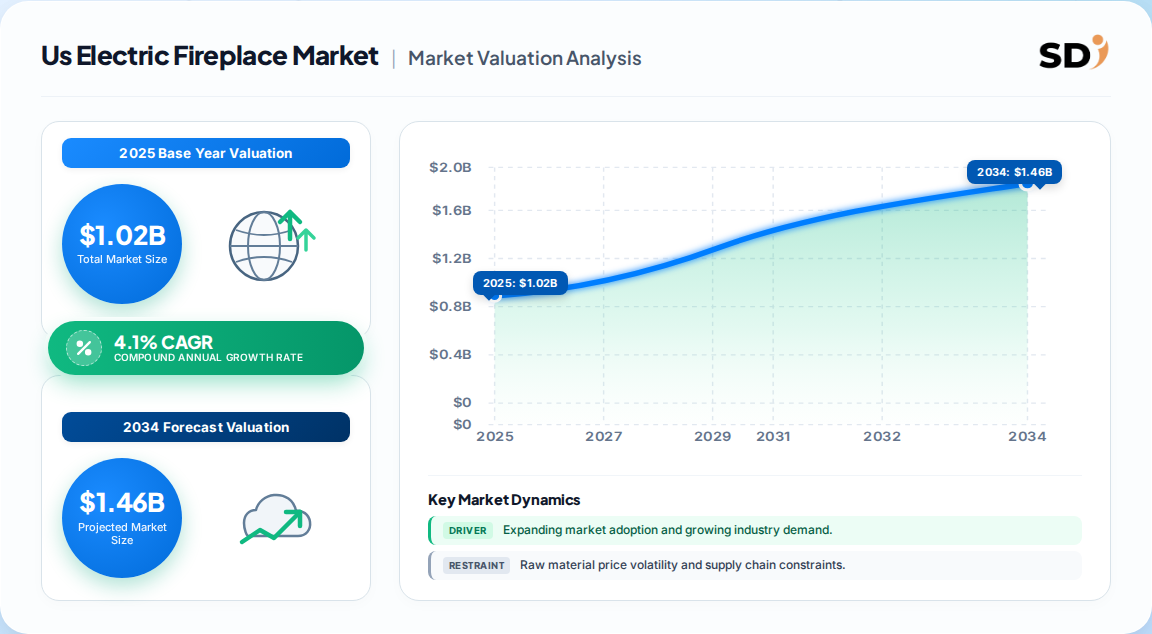
| Year | Market Size |
|---|---|
| 2025 | 1.020 B |
| 2026 | 1.060 B |
| 2027 | 1.110 B |
| 2028 | 1.150 B |
| 2029 | 1.200 B |
| 2030 | 1.250 B |
| 2031 | 1.310 B |

The US electric fireplace market covers non-combustion hearth products sold in the United States — wall-mounted, insert, freestanding and tabletop units that generate heat via a resistive element and simulate flame using LED, mirror or vapour projection. It spans residential retrofit, new construction and commercial ambiance applications across B2C retail and B2B project channels.
This analysis covers US manufacturer-level revenue for electric fireplaces across all installation types, projection technologies, sizes and distribution channels, from 2020 through 2031. It includes both B2C retail and B2B project sales.
This analysis does not cover gas, wood-burning or bioethanol hearth products, central HVAC systems, heat pumps, outdoor patio heaters, or the separate market for electric space heaters that lack a flame-effect feature.
Published estimates diverge by a factor of two, largely because some analyses report global figures while others count only retail sell-through. The US-specific revenue band of roughly 0.95–1.05 billion in 2025 is the most defensible reading.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| ~1.02 Billion | 2025 | 2031 | 4.1% | US manufacturer-level revenue, all formats | Consensus triangulation of published estimates |
| 812.62 Million | 2025 | 2033 | 3.24% | North America regional total, retail-weighted | One published estimate |
| 635.46 Million | 2025 | 2033 | 3.16% | US only, narrower product definition | A competing analysis |
| 5.9 Billion | 2025 | 2033 | 6.9% | Global, broader hearth-electrification scope | A separate global study |
Which figure should a buyer trust? Our analysis suggests the mid-point US estimate near 1.02 billion is most credible, because it reconciles the narrow retail-only reads with the wider North American regional totals once Canada and Mexico are stripped out. The much larger global figure is not contradictory — it simply captures a wider product perimeter and faster-growth emerging regions. The divergence implies US-focused operators should plan on mid-single-digit growth, not the high-single-digit rates quoted for global markets.
Segmentation matters more here than in most durables categories, because installation type and projection technology drive both price point and margin structure. The table below excludes geography.
| Parent segment | Children |
|---|---|
| By Installation Type | Wall-mounted, Insert, Freestanding, Tabletop |
| By Projection Type | LED, LCD, Holographic / vapour |
| By Size | Under 32 in, 32–45 in, 45–60 in, Over 60 in |
| By Application | Residential, Commercial |
| By Distribution Channel | Offline retail, Online / e-commerce, B2B project |
| By End-user | Homeowner, Builder / developer, Hospitality, Retail & office |
Wall-mounted dominates revenue, but the fastest growth sits in the 45–60 inch insert band, where media-wall renovation demand concentrates. LED projection remains the workhorse technology; holographic effects command a premium but remain a small revenue slice.
No single US census region dominates — the South leads on absolute revenue, reflecting both population and new-home construction volume, while the Northeast leads on per-household penetration because of older housing stock with legacy fireboxes.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.22% |
| South | 0.34% |
| Midwest | 0.21% |
| West | 0.23% |
Our analysis suggests the South will extend its lead through 2031 as multifamily completions convert into supplemental-heating fit-outs, while the West is where smart-feature attach rates will be highest. Precise state-level revenue splits require the full dataset — they are not reliably derivable from public benchmarks.
Growth in the US is driven less by heating need and more by renovation economics, electrification policy and design trends. The balance of these forces favours steady, unspectacular expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| All-electric building codes in states such as New York and California | Driver | Strong | Substitutes electric inserts for gas fireboxes in new and renovated units |
| Media-wall and living-room renovation cycles | Driver | Strong | Fireplace becomes a design anchor in upgrade projects |
| Smart-home integration (Wi-Fi, voice, app scheduling) | Driver | Moderate | Supports premium pricing and repeat-brand loyalty |
| Municipal wood-burning restrictions | Driver | Moderate | Removes a substitute and reduces particulate compliance risk |
| Limited primary heating capacity | Restraint | Strong | Caps the category at supplemental/zone heating in colder states |
| Imported OEM price pressure | Restraint | Moderate | Compresses entry-level margins and commoditizes small formats |
| Electricity tariffs and grid reliability | Restraint | Moderate | Dampens adoption in high-cost or outage-prone regions |
Our analysis suggests the single most under-appreciated driver is policy, not consumer preference. All-electric mandates convert a discretionary décor purchase into a compliance-driven specification decision. That tilts future demand toward builders and specifiers — a channel where vendor brand matters less and certification, framing standardization and delivery reliability matter more.
A mid-concentration market: no vendor holds a dominant share, but a handful of North American brands control the premium and specification tiers. The table compares positioning rather than precise share, which is not publicly disclosed.
| Vendor | Primary positioning | Notable strength |
|---|---|---|
| Glen Dimplex Group | Broad portfolio across price tiers | Scale, brand depth, global distribution |
| Twin-Star (Duraflame) | Mass retail and value segment | Retail shelf presence, consumer recognition |
| Napoleon Fireplaces | Premium residential and outdoor | Flame realism, dealer network |
| Hearth & Home Technologies | Builder and specification channel | Installed-base relationships with developers |
| Empire Comfort Systems | Value and mid-market hearth | Wide distribution, broad SKU range |
| Touchstone | Linear wall-mounted, direct-to-consumer | E-commerce strength, slim profiles |
| Amantii | Premium design-led linear units | Aesthetic differentiation, commercial projects |
The key differentiator is not heating performance — largely commoditized — but flame realism and installation simplicity. Brands that standardize recessed framing and offer consistent rough-in dimensions lower installer risk, which builds loyalty among builders and remodelers. That is a durable moat; app features are not.
Procurement in this category turns on four criteria: certification, rough-in compatibility, flame realism at the price point, and serviceability. Buyers should confirm UL or ETL listing, verify amp draw and circuit requirements against the installation environment, and check warranty terms on the heating element separately from the electronics.
The biggest hidden risk is specification drift in renovation projects — units specified early but substituted later when dimensions do not match the framed opening. Standardizing on a vendor with published rough-in tolerances reduces rework. Switching costs are moderate for retail buyers but high for builders, who embed a chosen unit into repeated floor plans.
Regulatory exposure is modest but real: Ecodesign-style requirements around thermostats and open-window detection are shaping product design in export markets, and US state-level electrification codes increasingly influence which formats specifiers consider. Operators should also model electricity cost sensitivity, since high tariffs in parts of the Northeast materially weaken the value proposition against central heating.
The balance of evidence favours a steady-state, replacement-driven market growing in the low-to-mid single digits, not a growth story. The US is already the world's most penetrated electric fireplace market, so expansion must come from per-unit value rather than household penetration. Vendors treating the US as a volume opportunity will misprice the risk.
The strongest counter-argument is that all-electric building mandates could trigger a step-change rather than a glide path. That is credible — but it would benefit builders and specification channels far more than retail brands, and it would compress average selling prices as volume shifts to standardized, code-driven fit-outs. Policy is therefore a growth driver and a margin headwind simultaneously.
Actionable strategy:
What would change this conclusion: a federal electrification incentive specific to hearth products, or a sustained spike in gas appliance costs. Either would move the US trajectory toward high-single-digit growth and justify a re-rating of the category.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with component suppliers, specialized fireplace OEMs and contract assemblers, national distributors, and installation contractors. Interviewees included VP-level sourcing leads, heads of product engineering, technical directors responsible for certification, and commercial operations managers overseeing builder and retail channels.
Trade flows were validated against USITC DataWeb import and export statistics, UN Comtrade records, and Eurostat datasets for cross-border comparison. Corporate annual filings, investor presentations, UL and ETL certification listings, and patent filings on flame-effect projection technologies provided product-level validation.
Top-down macroeconomic and household-renovation allocation was run simultaneously with bottom-up modelling of manufacturer capacity, realized pricing and end-use consumption. Divergent outputs were reconciled through weighted triangulation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | USD value, 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2031 projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Census-region share | Cross-border trade flow & consumption analysis | High |
| Competitive Landscape | Leading vendors | Annual reports, capacity mapping, filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.1% from 2020-2034 |
| Segmentation |
|
The US electric fireplace market was valued at approximately 1.02 billion in 2025 at manufacturer-level revenue. Published estimates range from roughly 635 million on narrow retail definitions to over 1 billion on broader product scopes.
Consensus forecasts point to roughly 4% compound annual growth from 2026 to 2031, materially below global rates because the US base is already mature and penetration is high relative to emerging regions.
Wall-mounted linear units hold the largest revenue share at roughly a third of the market. Inserts are the fastest-growing format, driven by homeowners converting unused wood and gas fireboxes into electric units.
Glen Dimplex, Twin-Star (Duraflame), Napoleon Fireplaces, Hearth & Home Technologies, Empire Comfort Systems, Touchstone and Amantii are among the most prominent suppliers across retail, builder and design channels.
There is no single federal hearth standard, but units require UL or ETL listing, and state-level all-electric building codes in states such as New York and California increasingly influence which formats specifiers may install in new construction.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with component suppliers, specialized fireplace OEMs and contract assemblers, national distributors, and installation contractors. Interviewees included VP-level sourcing leads, heads of product engineering, technical directors responsible for certification, and commercial operations managers overseeing builder and retail channels.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product Engineering & R&D Leads | 35% |
| Sourcing & Procurement Directors | 30% |
| Technical & Certification Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Component & Projection Suppliers | 30% |
| Specialized Fireplace OEMs | 40% |
| National Distributors & Retailers | 20% |
| Installation & Specification Contractors | 10% |
Trade flows were validated against USITC DataWeb import and export statistics, UN Comtrade records, and Eurostat datasets for cross-border comparison. Corporate annual filings, investor presentations, UL and ETL certification listings, and patent filings on flame-effect projection technologies provided product-level validation.
Top-down macroeconomic and household-renovation allocation was run simultaneously with bottom-up modelling of manufacturer capacity, realized pricing and end-use consumption. Divergent outputs were reconciled through weighted triangulation to produce a defensible base-year value and forecast band.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | USD value, 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2031 projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Census-region share | Cross-border trade flow & consumption analysis | High |
| Competitive Landscape | Leading vendors | Annual reports, capacity mapping, filings | High |