Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Ammonia Fuel Market by Product (Green Ammonia, Blue Ammonia, Grey Ammonia, Other), by Application (Power Generation Fuel, Maritime Shipping Fuel, Industrial Process & Heat Fuel, Fuel Cells, Other), by Sales Channel (Direct / Long-term Offtake, Distribution), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands, Norway), by Asia Pacific (China, Japan, South Korea, India, Australia, Southeast Asia), by Latin America (Brazil, Chile, Argentina), by Middle East & Africa (Saudi Arabia, UAE, Egypt, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 183
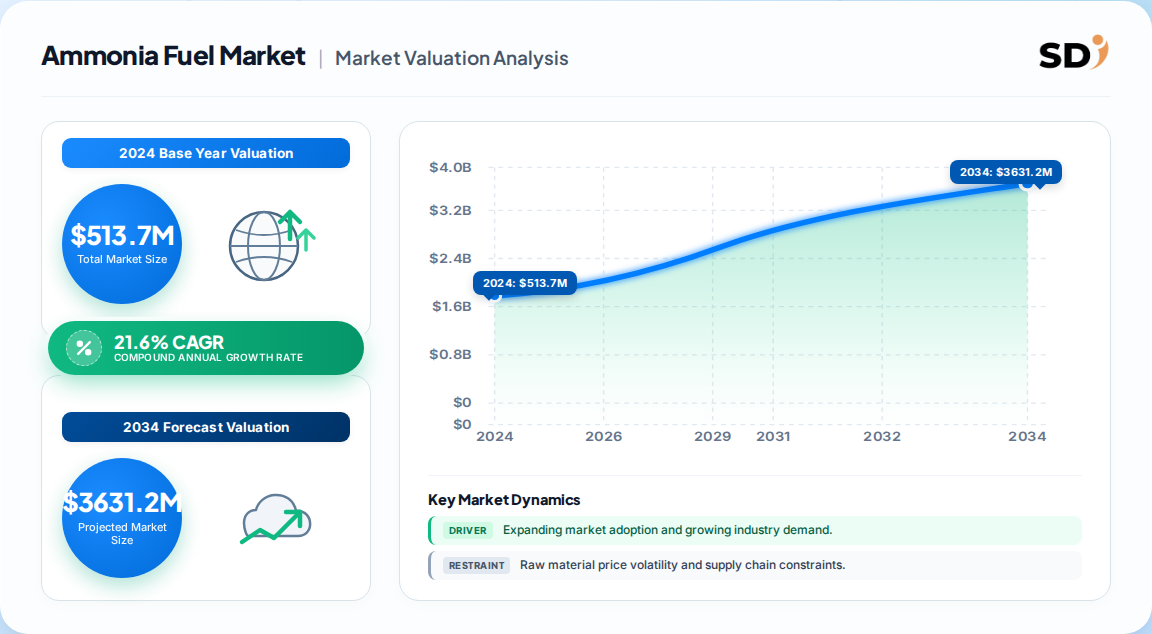
514 Million: The global ammonia fuel market was valued at approximately 514 Million in 2024, with a base-year reading of 620 Million in 2026 as commercial co-firing and bunkering pilots convert to contracts.
21.6% CAGR (2025-2033): Growth is the fastest of any low-carbon fuel category tracked, though it starts from a very small operational base.
2.96 Billion by 2033: Forecast revenue expands nearly sixfold, driven by power generation co-firing in Japan and Korea and IMO-aligned marine fuel offtake.
Blue ammonia leads today at 66.9% share (2024), while green ammonia grows fastest at 22.0% CAGR as electrolyzer costs fall.
Asia Pacific is the largest region, with China alone holding 73.2% of regional revenue; North America is the fastest-growing region.
Yara, CF Industries, Air Products, JERA, Mitsui and ACME anchor the competitive field, with the top five green-ammonia players holding roughly 54% share.
Why this matters for decision-makers: Fuel-ammonia supply remains scarce (only ~0.7 MT low-emission capacity operational), so buyers who lock multi-year offtake now will secure volume and price advantages that late entrants cannot replicate.
Ammonia Fuel Market Size (In Million)
2.0B
1.5B
1.0B
500.0M
0
514.0 M
2024
620.0 M
2025
754.0 M
2026
917.0 M
2027
1.120 B
2028
1.360 B
2029
1.650 B
2030
Ammonia Fuel Market Size (In Million)
Year
Market Size
2024
514.0 M
2025
620.0 M
2026
754.0 M
2027
917.0 M
2028
1.120 B
2029
1.360 B
2030
1.650 B
What is the Ammonia Fuel Market?
The ammonia fuel market covers ammonia (NH₃) sold or contracted as a combustible energy source rather than as a fertilizer feedstock. It spans power-plant co-firing, maritime bunkering, industrial process heat and fuel-cell applications, segmented by green, blue and grey production pathways.
Scope: what this report covers and excludes
This analysis covers fuel-grade ammonia demand across power generation, maritime shipping and industrial heat, segmented by production pathway (green, blue, grey) and region, with forecasts to 2033. This analysis does not cover agricultural fertilizer consumption, refrigerant-grade ammonia, or ammonia as a chemical intermediate for plastics and textiles.
How big is the market for Ammonia Fuel Market?
Estimates converge on a sub-billion-dollar base in 2024 and a multi-billion-dollar horizon by the early 2030s, but definitions diverge sharply on whether fertilizer-adjacent volumes are included. The table below isolates the fuel-only scope.
One published estimate (aggregated industry content)
500 Million (green only)
2025
2035 (17.85 Billion)
37.4%
Green ammonia only, all end uses including fertilizer
A competing analysis (GMI)
172.31 Billion (all ammonia)
2025
2034 (333.14 Billion)
7.6%
All ammonia, predominantly fertilizer (70.8%)
A competing analysis (ammonia market report)
The 513.7 Million fuel-only figure is the most defensible anchor for this report because it correctly excludes the 70%+ of ammonia volume consumed as fertilizer. Our analysis suggests the green-only 37.4% CAGR is directionally right but overstates fuel-specific growth, since it includes low-carbon fertilizer procurement.
How is the market segmented?
Segmentation is defined by production pathway and end-use application; geography is addressed separately below. Production pathway is the sharper commercial lens, because it determines carbon intensity, certification eligibility and price premium.
Parent
Children
By Product
Green Ammonia, Blue Ammonia, Grey Ammonia, Other
By Application
Power Generation Fuel, Maritime Shipping Fuel, Industrial Process & Heat Fuel, Fuel Cells, Other
By Sales Channel
Direct / Long-term Offtake, Distribution
Blue ammonia's 66.9% revenue share reflects existing CCS-equipped natural-gas capacity, not superior economics. This divergence implies blue is a bridge asset whose share erodes post-2030 as green project pipelines (19 MT firm/mature capacity by 2030) commission.
Which region leads in Ammonia Fuel Market?
Asia Pacific leads the ammonia fuel market, accounting for the largest regional revenue share in 2024, with China alone representing 73.2% of regional revenue. North America is the fastest-growing region, while Europe anchors premium green demand.
Ammonia Fuel Market Regional Market Share
Loading chart...
Ammonia Fuel Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.41%
Europe
0.24%
North America
0.21%
Middle East & Africa
0.08%
Latin America
0.06%
Parent
Children
Asia Pacific
China, Japan, South Korea, India, Australia, Southeast Asia
North America
USA, Canada, Mexico
Europe
Germany, UK, France, Italy, Netherlands, Norway
Middle East & Africa
Saudi Arabia, UAE, Egypt, South Africa
Latin America
Brazil, Chile, Argentina
Japan's NEDO target of 30 million tons of annual ammonia utilization by 2050 and Korea's co-firing mandates make Northeast Asia the demand anchor. Our analysis suggests China's 73.2% regional share is a production-side number; on the demand side, Japan and Korea will dominate fuel-grade offtake.
What is driving growth — and what is holding it back?
Binding maritime decarbonization rules and power-sector co-firing mandates are the primary demand drivers, while operational supply scarcity and infrastructure capital requirements are the dominant restraints through 2028.
Factor
Direction
Evidence strength
Mechanism
IMO Net-Zero Framework (2027 entry)
Driver
High
Mandates GHG fuel-intensity cuts on 85% of shipping CO₂
Japan/Korea co-firing mandates
Driver
High
Creates firm utility offtake for blue and green ammonia
Policy stack (45V, EU Delegated Acts, India SIGHT)
Driver
High
De-risks project finance across multiple jurisdictions
Forces longer lead times and higher offtake premiums
~2.49 Trillion infrastructure capital need
Restraint
Medium
Limits bunkering, storage and port buildout pace
Toxicity and NOx handling
Restraint
Medium
Raises safety capex and delays permitting
Our analysis suggests the restraint side is mispriced by the market: buyers plan around price, but the binding constraint through 2028 is deliverable volume, not cost. The balance favors sellers with operating assets until the 2029-2031 commissioning wave.
Who are the leading vendors?
The competitive field splits into three cohorts: established ammonia producers with CCS capability, Asian engineering and utility consortia, and electrolyzer-led green developers. No single player holds more than roughly 18% share, but the top five control over half the green segment.
Company
Positioning
Structural moat
Yara International
Largest green ammonia share (~18%)
Global distribution and fertilizer offtake base
CF Industries
Blue ammonia scale
Blue Point One 3.7 Billion JV with JERA and Mitsui
Air Products
Mega-project developer
NEOM-scale capital access and offtake lock-in
JERA / Mitsui
Utility co-firing demand
Captive power-plant demand and Japanese policy alignment
ACME Cleantech
Green project pipeline
India SIGHT-backed low-cost renewable supply
thyssenkrupp Nucera
Electrolyzer technology
Proprietary alkaline electrolysis IP
Differentiation rests on offtake contracts, not technology. This implies valuation should track contracted backlog and commissioning track record rather than announced capacity.
What do buyers and operators need to know?
Procurement strategy in ammonia fuel is fundamentally a supply-security problem, not a price-negotiation problem. With only about 0.7 MT of low-emission capacity confirmed operational globally, buyers face 2026-2028 lead-time risk; those who sign long-duration offtake with advanced-stage projects secure both volume and price floors before the 2029 supply inflection.
Selection criteria should weight carbon-intensity certification (EU RED III, IMO lifecycle rules) above headline price, because non-certified volumes will be commercially stranded in regulated end markets. Switching costs are high: bunkering infrastructure, engine retrofits and storage permitting create 10-20 year asset lock-in. Operators should also diligence NOx abatement and toxicity handling compliance, which drive hidden capex.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a supply-constrained market through 2028, not a demand-constrained one. The 21.6% CAGR is credible precisely because it is computed off a tiny base; the more important signal is that regulated demand (IMO 2027, Japanese co-firing) arrives before large-scale green capacity commissions. This timing mismatch is the central commercial fact of the market.
The strongest counter-argument is that green ammonia's 37.4% CAGR view, implying a 17.85 Billion green segment by 2035, would flood the market and compress premiums faster than the base case assumes. Our analysis suggests that scenario is possible but depends on the 2.49 Trillion infrastructure buildout materializing on schedule, which historical project slippage makes unlikely.
Investors should underwrite contracted offtake and commissioning milestones, not announced capacity; blue ammonia assets offer near-term cash flow but carry transition risk post-2030.
Operators in shipping and power should secure multi-year offtake now and pre-invest in bunkering and NOx abatement to convert compliance deadlines into cost advantage.
Suppliers should prioritize certified low-carbon volume and port-side logistics to capture the premium that certification scarcity will sustain through 2028.
What would change this conclusion: a wave of 2027-2028 green project FIDs exceeding 5 MT annual capacity, or a delay to IMO entry into force beyond 2028, would materially soften the supply-constrained thesis and shift the recommendation toward price-led procurement.
Ammonia Fuel Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Ammonia Fuel Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 21.6% from 2020-2034
Segmentation
By Product
Green Ammonia
Blue Ammonia
Grey Ammonia
Other
By Application
Power Generation Fuel
Maritime Shipping Fuel
Industrial Process & Heat Fuel
Fuel Cells
Other
By Sales Channel
Direct / Long-term Offtake
Distribution
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Netherlands
Norway
Asia Pacific
China
Japan
South Korea
India
Australia
Southeast Asia
Latin America
Brazil
Chile
Argentina
Middle East & Africa
Saudi Arabia
UAE
Egypt
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Green Ammonia
5.1.2. Blue Ammonia
5.1.3. Grey Ammonia
5.1.4. Other
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Power Generation Fuel
5.2.2. Maritime Shipping Fuel
5.2.3. Industrial Process & Heat Fuel
5.2.4. Fuel Cells
5.2.5. Other
5.3. Market Analysis, Insights and Forecast - by Sales Channel
5.3.1. Direct / Long-term Offtake
5.3.2. Distribution
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. Latin America
5.4.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Green Ammonia
6.1.2. Blue Ammonia
6.1.3. Grey Ammonia
6.1.4. Other
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Power Generation Fuel
6.2.2. Maritime Shipping Fuel
6.2.3. Industrial Process & Heat Fuel
6.2.4. Fuel Cells
6.2.5. Other
6.3. Market Analysis, Insights and Forecast - by Sales Channel
6.3.1. Direct / Long-term Offtake
6.3.2. Distribution
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Green Ammonia
7.1.2. Blue Ammonia
7.1.3. Grey Ammonia
7.1.4. Other
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Power Generation Fuel
7.2.2. Maritime Shipping Fuel
7.2.3. Industrial Process & Heat Fuel
7.2.4. Fuel Cells
7.2.5. Other
7.3. Market Analysis, Insights and Forecast - by Sales Channel
7.3.1. Direct / Long-term Offtake
7.3.2. Distribution
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Green Ammonia
8.1.2. Blue Ammonia
8.1.3. Grey Ammonia
8.1.4. Other
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Power Generation Fuel
8.2.2. Maritime Shipping Fuel
8.2.3. Industrial Process & Heat Fuel
8.2.4. Fuel Cells
8.2.5. Other
8.3. Market Analysis, Insights and Forecast - by Sales Channel
8.3.1. Direct / Long-term Offtake
8.3.2. Distribution
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Green Ammonia
9.1.2. Blue Ammonia
9.1.3. Grey Ammonia
9.1.4. Other
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Power Generation Fuel
9.2.2. Maritime Shipping Fuel
9.2.3. Industrial Process & Heat Fuel
9.2.4. Fuel Cells
9.2.5. Other
9.3. Market Analysis, Insights and Forecast - by Sales Channel
9.3.1. Direct / Long-term Offtake
9.3.2. Distribution
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Green Ammonia
10.1.2. Blue Ammonia
10.1.3. Grey Ammonia
10.1.4. Other
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Power Generation Fuel
10.2.2. Maritime Shipping Fuel
10.2.3. Industrial Process & Heat Fuel
10.2.4. Fuel Cells
10.2.5. Other
10.3. Market Analysis, Insights and Forecast - by Sales Channel
10.3.1. Direct / Long-term Offtake
10.3.2. Distribution
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Ammonia Fuel Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: Ammonia Fuel Market Volume Breakdown (Kilotons, %) by Region 2026 & 2034
Figure 3: North America Ammonia Fuel Market Revenue (Million), by Product 2026 & 2034
Figure 4: North America Ammonia Fuel Market Volume (Kilotons), by Product 2026 & 2034
Figure 5: North America Ammonia Fuel Market Revenue Share (%), by Product 2026 & 2034
Figure 6: North America Ammonia Fuel Market Volume Share (%), by Product 2026 & 2034
Figure 7: North America Ammonia Fuel Market Revenue (Million), by Application 2026 & 2034
Figure 8: North America Ammonia Fuel Market Volume (Kilotons), by Application 2026 & 2034
Figure 9: North America Ammonia Fuel Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Ammonia Fuel Market Volume Share (%), by Application 2026 & 2034
Figure 11: North America Ammonia Fuel Market Revenue (Million), by Sales Channel 2026 & 2034
Figure 12: North America Ammonia Fuel Market Volume (Kilotons), by Sales Channel 2026 & 2034
Figure 13: North America Ammonia Fuel Market Revenue Share (%), by Sales Channel 2026 & 2034
Figure 14: North America Ammonia Fuel Market Volume Share (%), by Sales Channel 2026 & 2034
Figure 15: North America Ammonia Fuel Market Revenue (Million), by Country 2026 & 2034
Figure 16: North America Ammonia Fuel Market Volume (Kilotons), by Country 2026 & 2034
North America Ammonia Fuel Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Ammonia Fuel Market Revenue Million Forecast, by Product 2020 & 2034
Table 7: Ammonia Fuel Market Revenue Million Forecast, by Region 2020 & 2034
Table 8: Ammonia Fuel Market Volume Kilotons Forecast, by Region 2020 & 2034
Table 9: North America Ammonia Fuel Market Revenue Million Forecast, by Product 2020 & 2034
Table 10: North America Ammonia Fuel Market Volume Kilotons Forecast, by Product 2020 & 2034
Table 11: North America Ammonia Fuel Market Revenue Million Forecast, by Application 2020 & 2034
Table 12: North America Ammonia Fuel Market Volume Kilotons Forecast, by Application 2020 & 2034
Table 13: North America Ammonia Fuel Market Revenue Million Forecast, by Sales Channel 2020 & 2034
Table 14: North America Ammonia Fuel Market Volume Kilotons Forecast, by Sales Channel 2020 & 2034
Table 15: North America Ammonia Fuel Market Revenue Million Forecast, by Country 2020 & 2034
Table 16: North America Ammonia Fuel Market Volume Kilotons Forecast, by Country 2020 & 2034
USA Ammonia Fuel Market Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the ammonia fuel market?
The global ammonia fuel market was valued at approximately 514 Million in 2024 and is projected to reach 2,960 Million by 2033. The figure excludes fertilizer-grade ammonia, which dominates total ammonia consumption.
2. What is the ammonia fuel market CAGR?
The market is forecast to grow at a 21.6% CAGR from 2025 to 2033, making it one of the fastest-growing low-carbon fuel categories, albeit from a small operational base.
3. Which segment leads the ammonia fuel market?
Blue ammonia led with 66.9% revenue share in 2024 due to existing CCS-equipped capacity. Green ammonia is the fastest-growing segment at 22.0% CAGR as electrolyzer economics improve.
4. Which region dominates ammonia fuel demand?
Asia Pacific is the largest region, with China holding 73.2% of regional revenue. Japan and Korea drive fuel-grade demand through co-firing mandates, while North America is the fastest-growing region.
5. What are the main applications of ammonia as fuel?
Power generation fuel led with 66.0% revenue share in 2024, followed by maritime shipping and industrial process heat. Maritime shipping is expected to accelerate sharply after IMO rules take effect in 2027.
6. What are the key risks in the ammonia fuel market?
Supply scarcity is the dominant near-term risk, with only about 0.7 MT of low-emission capacity operational. Toxicity, NOx emissions and roughly 2.49 Trillion in infrastructure capital needs also constrain scaling.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. We conducted structured interviews and in-depth briefings with stakeholders across the ammonia fuel value chain, including low-carbon ammonia producers, electrolyzer and synthesis technology vendors, power utilities testing co-firing, marine fuel suppliers and port bunkering operators, and industrial heat users. Decision-maker designations interviewed included VP-level Sourcing and Procurement leads, Heads of Hydrogen and Fuels R&D, Technical Directors for combustion and emissions, and Commercial Operations Leads responsible for offtake structuring.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Leads
38%
R&D & Technical Directors
32%
Commercial Operations & Offtake Leads
18%
Regulatory & Compliance Managers
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Ammonia Producers & CCS Operators
40%
Electrolyzer & Synthesis Technology Vendors
25%
Utilities, Shipping & Bunkering Operators
22%
Industrial Heat & Chemical Offtakers
13%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent filings covering ammonia combustion and electrolysis, and technical standards and data published by recognized non-profit industry associations and intergovernmental bodies. All third-party market research was used only as a directional cross-check.
Demand Modeling & Market Sizing Triangulation
We triangulate a Top-Down allocation (macroeconomic energy transition spending, power and shipping fuel substitution rates, policy-mandated blending targets) against a Bottom-Up model (plant-level capacity, utilization, product pricing and end-use consumption). Reconciliation of the two views produces the base-year value and the compound forecast.
 Ammonia Fuel Market