 Cashew Nut Essential Oil Market
 2025: Size, CAGR & Outlook
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 244

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Cashew Nut Essential Oil Market
Sandeep Singh
Research Analyst

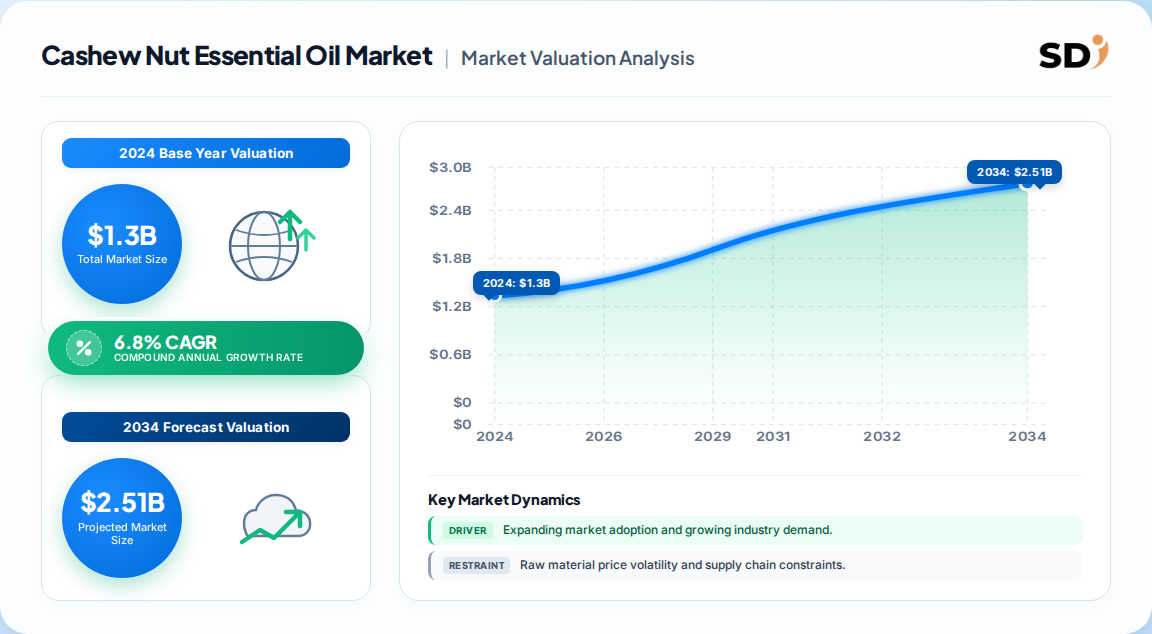
| Year | Market Size |
|---|---|
| 2024 | 1.300 B |
| 2025 | 1.390 B |
| 2026 | 1.500 B |
| 2027 | 1.600 B |
| 2028 | 1.710 B |
| 2029 | 1.820 B |
| 2030 | 1.900 B |

The cashew nut essential oil market covers oils extracted from cashew kernels or shells via cold pressing, distillation, or supercritical CO2, sold for personal care, food, aromatherapy, and pharmaceutical use. It is a niche botanical-oil segment valued for fatty-acid richness, antioxidant, and anti-inflammatory properties.
This report covers global conventional and organic cashew nut essential oil across personal care & cosmetics, food & beverage, aromatherapy, pharmaceutical, and other applications, through supermarkets, convenience stores, specialty stores, and online retail. This analysis does not cover raw cashew kernel trade, cashew shell liquid (CNSL) industrial chemicals, or competing botanical oils such as almond, jojoba, or macadamia.
Published estimates cluster tightly around a USD 1.3 Billion base with mid-single-digit growth, but horizons diverge sharply — a 2030 endpoint at USD 1.9 Billion versus 2035 projections near USD 2.7 Billion imply different underlying assumptions.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.3B → 1.9B | 2024 | 2030 | 6.8% | Global, conventional + organic, all applications | One published estimate |
| USD 1.32B → 2.67B | 2024 | 2035 | 6.59% | Global, product and application segmentation | A competing analysis |
| USD 1.3B → 2.5B | 2023 | 2033 | 6.9% | Global, includes distribution channel split | A competing analysis |
| USD 1.3B → 2.0B | 2025 | 2032 | 6.2% | Global, conventional and organic split | A competing analysis |
The 6.8% / 2030 figure is the most defensible for near-term planning: it sits inside the consensus band, uses a clearly dated base year, and avoids the compounding drift that inflates longer horizons. Our analysis suggests the 2035 and 2033 numbers are arithmetically consistent but rest on aggressive organic-conversion assumptions that the supply chain does not yet support.
Segmentation follows three axes — product grade, end-use application, and distribution route — with product grade the most commercially decisive because it governs pricing power and certification burden.
| Parent segment | Children |
|---|---|
| By Product | Conventional, Organic |
| By Application | Personal Care & Cosmetics, Food & Beverage, Aromatherapy, Pharmaceutical, Others |
| By Distribution Channel | Supermarkets & Hypermarkets, Convenience Stores, Specialty Stores, Online Retailers |
Conventional oil holds roughly 81% of product revenue because of cost and availability; organic commands a premium but faces expensive certification. Personal care leads applications at ~35%, with food & beverage second on flavor and shelf-life functionality.
Asia Pacific leads the global cashew nut essential oil market with approximately 40% revenue share, underpinned by Indian, Vietnamese, and Indonesian raw-material supply and expanding domestic cosmetics demand.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.4% |
| North America | 0.24% |
| Europe | 0.19% |
| South America | 0.09% |
| Middle East & Africa | 0.08% |
| Region | Share |
|---|---|
| Asia Pacific | 40% |
| North America | 24% |
| Europe | 19% |
| South America | 9% |
| Middle East & Africa | 8% |
North America is the fastest-growing demand center on a percentage basis, with the U.S. alone estimated near USD 350 Million, while China is forecast to compound at roughly 9.7% — the highest country-level rate in the dataset. This divergence implies supply-side investment should follow Asian raw material and North American brand demand simultaneously.
Growth is being pulled by clean-label reformulation in beauty and wellness, while being capped by labor-intensive extraction economics and thin clinical validation of health claims.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Clean beauty and plant-based reformulation | Driver | Strong | Brands substitute synthetic additives with botanical oils |
| Aromatherapy and holistic wellness demand | Driver | Moderate | Retail expansion of wellness and relaxation categories |
| Cold-press and supercritical CO2 efficiency gains | Driver | Moderate | Higher purity and yield lower unit cost over time |
| Labor-intensive shell handling and caustic compounds | Restraint | Strong | Keeps price premium and limits mass-market access |
| Seasonal, geographically concentrated raw supply | Restraint | Strong | Input-cost volatility and supply instability |
| Limited clinical trial evidence | Restraint | Moderate | Slows pharmaceutical and therapeutic adoption |
The balance favors growth, but the restraint set is structural rather than cyclical. Our analysis suggests price volatility in raw cashew — not demand — is the single largest threat to margin stability through 2030.
The competitive field is fragmented: no single player holds dominant global share, and differentiation runs along extraction technology, organic certification, and traceability rather than brand alone.
| Vendor archetype | Position | Differentiation lever |
|---|---|---|
| Integrated cashew processors | Strong in conventional supply | Vertical control of raw material |
| Specialty essential-oil houses | Strong in cosmetic grade | Purity, CO2 extraction, documentation |
| Organic-certified niche producers | Growing | Certification and ethical sourcing story |
| Regional distributors and traders | Broad reach | Logistics and multi-origin blending |
Moat durability is highest where certification and traceability are paired with long-term farmer relationships. Blockchain-backed provenance and AI-driven quality control are emerging as credible differentiators, particularly for premium cosmetic customers who audit suppliers.
Buyers should treat specification consistency as the primary procurement risk. Batch-to-batch variation in aroma and fatty-acid profile is a documented weak point, and the absence of standardized global quality benchmarks means purchase contracts must define purity, extraction method, and origin explicitly.
Switching costs are moderate for conventional grades and high for certified organic or cosmetic-grade supply, where re-qualification and documentation take months. Regulatory exposure differs by end-use: cosmetic and food applications face the heaviest compliance burden, while aromatherapy is comparatively light. Operators should also model raw-material seasonality into safety stock, because geographically concentrated harvests create predictable but sharp input-cost swings.
The balance of evidence favors a selective-growth posture rather than a volume play. Demand is real and durable, but the conventional segment — 81% of revenue — is structurally exposed to price competition and raw-material volatility, which caps margin expansion for undifferentiated suppliers.
The strongest counter-argument is that conventional scale still wins on accessibility: in price-sensitive emerging markets, cost leadership will out-compete premium positioning for years. That is credible, but it argues for portfolio positioning rather than against premium investment.
What would change this conclusion: evidence of rapid organic-certification cost deflation, or a credible clinical trial validating therapeutic claims, would shift the balance decisively toward premium specialization and accelerate the forecast curve.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.8% from 2020-2034 |
| Segmentation |
|
The global cashew nut essential oil market was valued at approximately USD 1.3 Billion in 2024 and is projected to reach USD 1.9 Billion by 2030, growing at a 6.8% CAGR across the forecast period.
Asia Pacific leads with roughly 40% revenue share, driven by Indian, Vietnamese, and Chinese raw-material supply and rising domestic cosmetics demand. North America is the fastest-growing demand center on a percentage basis.
Personal care and cosmetics is the largest application at about 35% share, followed by food and beverage, aromatherapy, and pharmaceuticals. Cosmetic use is driven by moisturizing and antioxidant properties.
Organic grades are gaining share on clean-label and sustainability preferences, but certification cost and complexity keep the segment small. Conventional oil still holds roughly 81% of product revenue.
Labor-intensive shell handling, seasonal raw-material supply, and limited clinical validation of health claims are the main restraints, keeping cashew nut essential oil premium-priced and niche relative to mainstream essential oils.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct validation of capacity, pricing, and channel economics. We conducted in-depth interviews with stakeholders across the value chain, including raw material and kernel suppliers, specialized essential-oil producers, contract formulators and blenders, and global distributors serving the cosmetics and food sectors. Interviewees were drawn from decision-maker designations including VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both supply-side and demand-side perspectives were captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 35% |
| Heads of R&D | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Kernel Suppliers | 30% |
| Specialized Essential-Oil Producers | 35% |
| Contract Formulators & Blenders | 20% |
| Global Distributors & Traders | 15% |
Secondary benchmarking draws on official multilateral trade and standards databases, including UN Comtrade, WTO tariff and trade records, US ITC data, and Eurostat, supplemented by corporate annual filings (10-K and SEC submissions), investor presentations, patent databases, and recognized non-profit technical standards and industry associations. These sources anchor trade-flow estimates and validate producer-level capacity claims.
Market sizing triangulates top-down and bottom-up models simultaneously. The top-down approach allocates macroeconomic and industry-segment spending to botanical oils by application; the bottom-up approach models manufacturer capacity, product pricing, and end-use consumption. Divergence between the two is reconciled through interview evidence and trade-flow checks.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |