 Electric Hybrid Construction Equipment Market
 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 208

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Electric Hybrid Construction Equipment Market
Sandeep Singh
Research Analyst
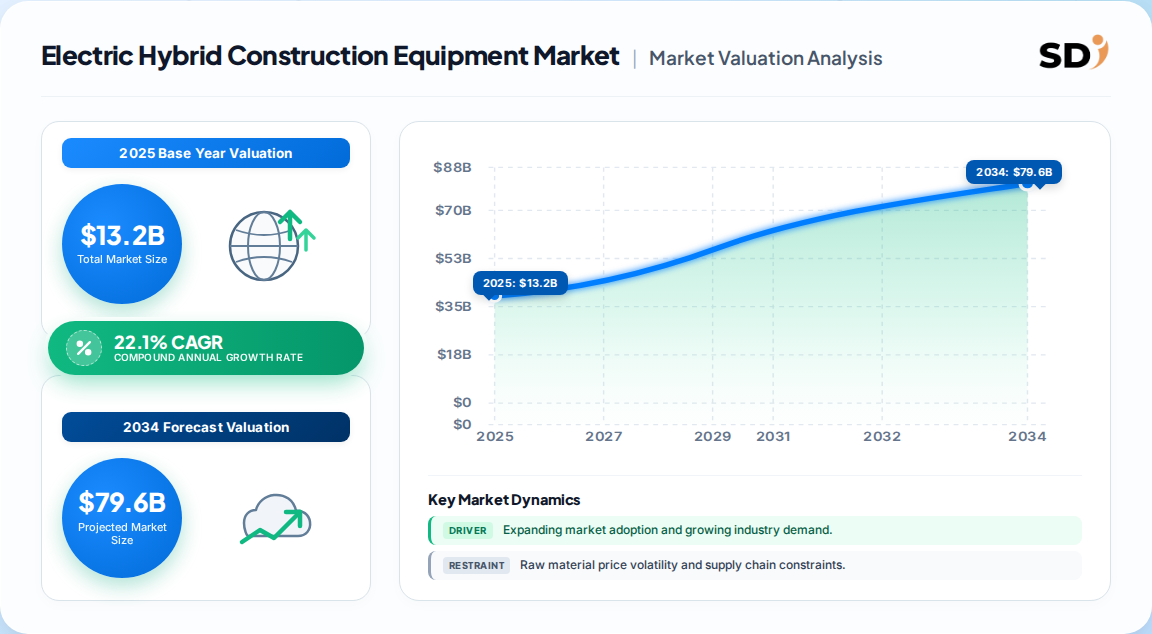
| Year | Market Size |
|---|---|
| 2025 | 13.20 B |
| 2026 | 16.10 B |
| 2027 | 19.70 B |
| 2028 | 24.10 B |
| 2029 | 29.40 B |
| 2030 | 35.90 B |
| 2031 | 43.80 B |

The Electric Hybrid Construction Equipment market covers battery-electric and hybrid-electric excavators, loaders, dump trucks, telehandlers, and compact machinery used in construction, infrastructure, and mining. It spans the machines themselves plus the charging, energy storage, and fleet-management infrastructure required to deploy them in urban and remote project environments.
This report covers global electric and hybrid construction equipment across power source, product type, and end user from 2025 to 2035. It includes battery-electric and plug-in hybrid machines plus associated site-energy and charging solutions. This analysis does not cover conventional diesel equipment, on-road commercial vehicles, or stationary industrial energy storage systems.
Published estimates converge on a USD 13–16 billion base for 2025 but diverge sharply on horizon CAGR, reflecting different definitions of hybrid inclusion. The table below compares the leading estimates and their scope assumptions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 13.2 Billion | 2025 | 2035 | 22.1% | Electric + hybrid, all construction equipment | One published estimate |
| USD 15.8 Billion | 2025 | 2035 | 20.8% | Electric-only, all equipment types | A competing analysis |
| USD 17.1 Billion | 2026 | 2035 | 20.8% | Electric-only, BEV + PHEV | A competing analysis |
Our analysis suggests the USD 13.2 billion figure is the most defensible for the combined electric-and-hybrid definition because it explicitly includes hybrid machines, which captured 56.78% of the power-source mix in 2025. Electric-only estimates understate the near-term market by excluding hybrids that bridge the cost and charging gap.
Segmentation follows three parent axes: power source, product type, and end user. Hybrid electric leads near-term adoption, excavators dominate product demand, and construction companies remain the primary buyer group.
| Parent Segment | Children | 2025 Share |
|---|---|---|
| By Power Source | Hybrid Electric, Battery Electric | 56.78% hybrid |
| By Product | Excavators, Loaders, Dump Trucks, Cranes, Telehandlers, Compact Equipment | 33.67% excavators |
| By End User | Construction Companies, Rental & Leasing, Mining, Municipal | 64.67% construction companies |
Asia-Pacific leads with 37.78% of 2025 global consumption, supported by China's construction-equipment manufacturing base and India's USD 1.4 trillion infrastructure pipeline. Europe follows on regulatory pull, with North America third on infrastructure spending.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.38% |
| Europe | 0.24% |
| North America | 0.22% |
| Latin America | 0.08% |
| Middle East & Africa | 0.08% |
The regional spread implies a two-speed adoption curve: Asia-Pacific drives volume through manufacturing scale, while Europe drives premium adoption through Stage V compliance and public procurement rules. This divergence means vendors must maintain dual product strategies rather than a single global platform.
Urban zero-emission rules and falling battery costs are the primary accelerants, while component supply concentration and upfront capital costs are the main brakes. The net growth balance remains strongly positive but unevenly distributed by region and machine class.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Urban zero-emission rules and public procurement | Driver | High | Site access and tender eligibility |
| Declining battery costs (8% decline in 2025) | Driver | High | Lower TCO for high-utilization machines |
| Fleet-as-a-service bundles | Opportunity | Medium | Shifts buyer focus to productive-hour economics |
| Component supply concentration | Restraint | High | -1.6 pp drag through early 2030s |
| High upfront capital cost | Restraint | High | -1.5 to -2.5 pp CAGR impact |
| Temporary-site charging constraints | Restraint | Medium | Limits medium/heavy-duty deployment |
Our analysis suggests the driver-restraint balance favors early movers in compact and medium excavators, where charging can be depot-based. Heavy-duty deployment remains gated by site power availability, not machine capability.
The competitive landscape is moderately concentrated, with the top five players holding roughly 40% of the electric construction equipment market in 2025. Caterpillar leads with over 14% share, followed by Doosan Infracore, Hitachi Construction, John Deere, and Liebherr.
| Company | Estimated Position | Differentiation |
|---|---|---|
| Caterpillar | Leader, >14% share | Broad portfolio plus R1700 XE underground loader |
| Volvo CE | Strong in Europe | EC230 Electric with 450 kWh full-shift battery |
| Komatsu | Global scale | Hybrid and electric platform integration |
| Liebherr | Niche strength | LPO mobile energy-storage and site-power planning |
| Doosan / Deere / Hitachi | Top-five cohort | Regional distribution and rental channel access |
Differentiation is shifting from machine specs to ecosystem depth. Vendors that bundle chargers, mobile storage, telematics, and residual-value support are building stickier moats than those competing on battery capacity alone.
Buyers should prioritize total productive-hour economics over sticker price. The acquisition premium on electric machines is material, but lower fuel and maintenance costs can close the gap for high-utilization assets. Procurement teams must also assess site-power readiness, transformer capacity, and demand charges before committing to medium or heavy-duty electric fleets. Regulatory compliance is a second gating factor: EU Stage V and U.S. Tier 4 rules, plus urban zero-emission zones, can make electric machines the only compliant option for certain projects. Finally, residual-value risk remains unresolved for first-generation battery packs, so buyers should negotiate battery-health warranties and buy-back clauses. Contractors with intermittent utilization should favor rental or fleet-as-a-service models to avoid stranded capital.
The balance of evidence favors the hybrid-first thesis. Hybrids captured 56.78% of 2025 share because they deliver diesel-free operation without full charging dependency, and they will remain the volume bridge until site-power infrastructure matures. The strongest counter-argument is that battery-cost declines of 20% in 2024 and 8% in 2025 could accelerate pure-electric adoption faster than hybrids can amortize their development costs, particularly in compact equipment where depot charging is already viable. Our analysis suggests this risk is real but contained to the compact segment through 2028.
The more consequential insight is that machine parity is arriving faster than site-energy parity. OEMs that treat charging, mobile storage, and energy-management software as aftermarket adjuncts will lose share to competitors offering integrated 36–60-month machine-plus-energy subscriptions. The supply-chain concentration risk, with China refining roughly 70% of key minerals, reinforces the case for dual sourcing and regional battery-pack assembly as strategic necessities rather than cost centers.
Actionable Strategy:
What would change our conclusion: if fast-charging infrastructure at temporary sites scales faster than projected, or if battery pack costs fall below USD 80/kWh for construction-grade systems before 2028, the hybrid bridge shortens and pure-electric adoption accelerates across medium-duty classes.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 22.1% from 2020-2034 |
| Segmentation |
|
The market was valued at USD 13.2 billion in 2025, with hybrid electric machines representing 56.78% of the power-source mix. Asia-Pacific accounted for 37.78% of global consumption.
The market is projected to grow at a 22.1% CAGR from 2026 to 2035, reaching approximately USD 97.2 billion by 2035, driven by emission regulations and falling battery costs.
Asia-Pacific leads with 37.78% of 2025 global consumption, supported by China's manufacturing scale and India's infrastructure pipeline. Europe follows on regulatory pull from Stage V standards.
Component supply concentration, particularly China's dominance in battery materials and refining, creates a -1.6 percentage-point growth drag. High upfront capital costs and temporary-site charging constraints also limit adoption.
Caterpillar leads with over 14% share, followed by Doosan Infracore, Hitachi Construction, John Deere, and Liebherr. The top five players collectively hold roughly 40% of the market.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split, with in-depth interviews conducted across the construction equipment value chain including battery-cell and component suppliers, OEMs of excavators and loaders, specialized powertrain integrators, rental fleet operators, and global distributors. We interviewed decision-makers including VP-level Sourcing Leads, Heads of Electrification R&D, Technical Directors, and Commercial Operations Leads to validate adoption timelines, pricing expectations, and charging-infrastructure constraints.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Electrification & R&D Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory & Compliance Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| OEMs & Powertrain Integrators | 45% |
| Battery & Component Suppliers | 30% |
| Rental & Distribution Operators | 25% |
We triangulate primary findings against official multilateral trade databases including UN Comtrade, WTO tariff schedules, US ITC trade data, and Eurostat non-road machinery statistics. Corporate annual filings (10-K, SEC disclosures, investor presentations), patent databases, and recognized technical standards bodies including ISO and EU Stage V regulatory frameworks were used to validate product availability and compliance timelines.
We run simultaneous top-down macroeconomic and industry-segment allocation alongside bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. Divergences between the two approaches are reconciled through demand-elasticity adjustments and regional cross-checks.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2035 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
