 Industrial Gas Regulator Market
 Size, CAGR & Forecast 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 185

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Industrial Gas Regulator Market
Sandeep Singh
Research Analyst

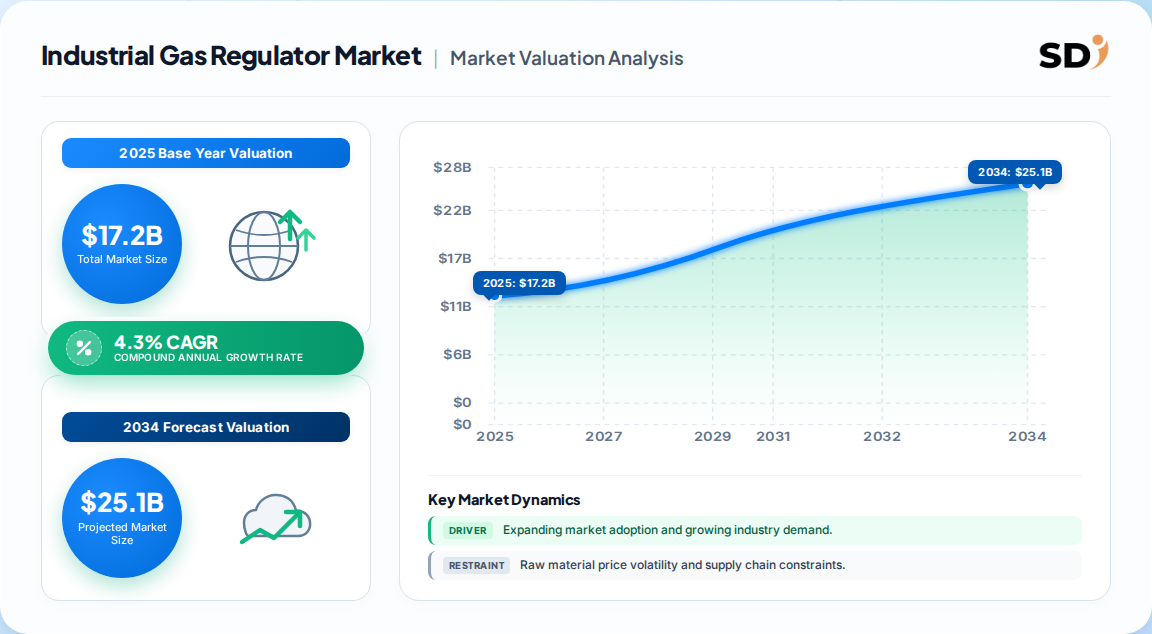
| Year | Market Size |
|---|---|
| 2025 | 17.20 B |
| 2026 | 18.10 B |
| 2027 | 18.80 B |
| 2028 | 19.60 B |
| 2029 | 20.40 B |
| 2030 | 21.30 B |
| 2031 | 22.20 B |

The industrial gas regulator market covers devices that reduce high inlet gas pressure to a stable, controlled outlet pressure and flow, spanning single-stage and dual-stage, brass and stainless-steel, and conventional through smart, sensor-linked configurations. It serves oil and gas, chemicals, metals, medical, food and electronics gas systems.
This analysis covers global demand for pressure regulators used with compressed, cryogenic and specialty gases across industrial, medical and process applications, valued at manufacturer level in USD. It spans single-stage and dual-stage, line and cylinder, and conventional versus digitally enabled units. This analysis does not cover gas cylinders, valves, manifolds, flowmeters, compressors, bulk tanks or pipeline infrastructure except as demand context.
Published estimates cluster between USD 17.2 billion and USD 19.5 billion for 2025–2026, with forecast CAGRs ranging from 3.9% to 6.4%. The spread reflects differing treatment of line regulators, manifold assemblies and aftermarket service, not fundamental disagreement about demand direction.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 17.2 B → 29.3 B | 2025 | 2035 | 4.3% | Value-based industrial gas regulators, broad end-use | One published estimate |
| USD 18.28 B → 24.92 B | 2025 | 2030 | 6.4% | Regulator-only hardware, six end-use verticals | A competing analysis |
| USD 18.10 B → 21.95 B | 2025 | 2030 | 3.9% | Segment-level hardware, medium-concentration field | A competing analysis |
Our assessment: the 4.3% trajectory is the most defensible headline because it reconciles a large, slow-replacement conventional installed base with faster premiumization in hydrogen, semiconductor and medical duty. The 6.4% figure appears to fold in adjacent gas-handling hardware, while 3.9% may under-weight cryogenic and high-purity upgrades. Buyers should treat 4–5% as the planning band and model premium segments separately, where growth runs closer to 5.2–5.6%.
| Year | Value (derived from base value and stated CAGR) |
|---|---|
| 2025 | USD 17.2 Billion |
| 2026 | USD 18.1 Billion |
| 2027 | USD 18.8 Billion |
| 2028 | USD 19.6 Billion |
| 2029 | USD 20.4 Billion |
| 2030 | USD 21.3 Billion |
| 2035 | USD 29.3 Billion |
Segmentation follows four non-geographic axes: gas type, material of construction, pressure range and end-use industry, with type (single vs dual stage) cutting across all four. The critical insight is that mix, not volume, drives value growth.
| Parent segment | Children | 2024 share / growth signal |
|---|---|---|
| By Gas Type | Inert; Reactive; Corrosive/Toxic; Others | Inert 33.1%; reactive 4.9% CAGR |
| By Material | Brass; Stainless Steel; High-Purity Alloys | Brass 45.4%; alloys 5.2% CAGR |
| By Pressure Range | Low; Medium; High | Medium 37.7%; high 4.4% CAGR |
| By Type | Single Stage; Dual Stage | Dual stage favoured in safety-critical duty |
| By End-Use Industry | Oil and Gas; Chemical; Steel and Metal Processing; Medical; Food and Beverage; Electronics; Others | Oil and gas 58.9%; hydrogen systems 5.0% CAGR |
Our analysis suggests brass will defend volume in welding, HVAC and LPG distribution while stainless and nickel alloys absorb the margin pool. Suppliers weighted to brass-only portfolios face structural price pressure; those dual-qualified across materials can price on risk avoidance rather than unit cost.
Asia-Pacific led with 31.7% of 2024 revenue, underpinned by semiconductor fab build-out, steel decarbonization and refinery capacity. The Middle East is the fastest-growing region at 5.60% CAGR, driven by LNG bunkering and hydrogen export projects.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.32% |
| North America | 0.27% |
| Europe | 0.21% |
| Middle East & Africa | 0.12% |
| South America | 0.08% |
| Region | 2024 revenue share | Growth signal |
|---|---|---|
| Asia-Pacific | 31.7% | Largest base; fab and steel pull |
| North America | 26.8% | Mid-stream retrofits, medical gas compliance |
| Europe | 21.4% | PFAS-free sealing, hydrogen corridors |
| Middle East & Africa | 12.1% | Fastest at ~5.6% CAGR |
| South America | 8.0% | Cyclical, import-dependent |
The practical implication: capacity and service footprint decisions should follow Asia-Pacific volume but Middle East margin. Vendors without regional certification support in the Gulf will concede LNG and hydrogen tenders to incumbents already embedded in port and electrolyzer EPC packages.
Growth is driven by hydrogen capital formation, stricter safety regulation and high-purity gas demand; it is restrained by helium supply volatility, cyclical capex and compliance-driven material cost inflation. Net effect is steady rather than explosive expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Energy transition and hydrogen economy | +1.3% CAGR | Strong (IEA: USD 4.3 B low-emissions hydrogen capex, 2024) | Pressure control at electrolyzer, compression, storage, dispensing |
| Stricter safety and regulatory compliance | +0.9% CAGR | Strong (OSHA 29 CFR 1910.101; NFPA 55; FDA cGMP) | Mandated replacement and documented fit-for-service equipment |
| High-purity and specialty gases | +0.8% CAGR | Strong (sub-ppb fab requirements) | Electropolished paths, dual-diaphragm designs |
| Digitalization and smart regulators | +0.7% CAGR | Moderate | IoT pressure/temperature logging shifts procurement to asset performance |
| Labor shortage and automation | +0.6% CAGR | Moderate | Remote monitoring replaces manual inspection rounds |
| Helium supply volatility | −0.6% CAGR | Moderate | Output cuts defer electronics gas projects |
| Cyclical industrial capex downturn | −0.4% CAGR | Moderate | Delayed brownfield and greenfield spending |
| PFAS-free sealing mandate costs | −0.3% CAGR | Emerging | Reformulation and requalification expense |
Balance of evidence: drivers exceed restraints by a comfortable but narrowing margin. Our analysis suggests the marginal growth dollar is regulatory, not industrial — compliance deadlines create non-discretionary replacement demand that survives capex downturns. That makes regulators unusually defensive for an industrial hardware category.
Air Liquide leads with over 8% share in 2025, and the top five together hold about 35%, indicating a medium-concentration market with room for specialists. Competition is shifting from unit price to certification breadth and digital integration.
| Company | Position | Noted strength |
|---|---|---|
| Air Liquide | Leader, >8% share | Integrated gas supply plus equipment; hydrogen and UHP projects |
| Air Products and Chemicals | Top five | Large-project hydrogen and LNG exposure |
| Airgas (Air Liquide) | Top five | Distribution reach across North America |
| Cavagna Group | Top five | LPG, cylinder and pressure-control breadth |
| Colfax Corporation (ESAB) | Top five | Welding and fabrication channel strength |
| Emerson Electric | Challenger | Automation and flow-platform integration |
| Parker Hannifin | Challenger | Instrumentation, alloys and high-pressure expertise |
| Honeywell International | Challenger | Consolidating via Sundyne (USD 2.16 B, June 2025) |
| TESCOM, Swagelok, Rotarex, GCE, Pietro Fiorentini | Specialists | High-purity, cryogenic and precision niches |
Moats are built on three layers: certification portfolios (SEMI, ISO, NFPA, cGMP), installed-base service networks, and materials engineering depth. Software alone is a weak moat — smart regulators are easy to copy, whereas twenty-year qualification records on a fab gas line are not. Consolidation by automation majors signals that end-to-end gas flow platforms, not standalone regulators, will define the next competitive tier.
Selection should start with consequence of failure, not purchase price. A pressure deviation in a semiconductor line destroys yield; in a medical gas system it becomes a patient-safety event; in LNG bunkering it becomes a regulatory breach. Buyers should specify to the highest credible failure consequence the installation can produce.
Four procurement risks deserve board-level attention. First, material certification gaps — PFAS-free sealing and alloy traceability now require documented evidence, and retrofitting documentation post-installation is costly. Second, lead-time asymmetry — extended compressor and equipment lead times push operators toward modular skids, which changes regulator specification and interface requirements. Third, switching costs — integrating a new regulator into plant controls, alarm logic and maintenance workflows typically exceeds the unit cost several times over. Fourth, tariff exposure on imported brass, stainless components, sensors and diaphragms is lengthening replacement cycles in North America and Europe.
Compliance is the quiet procurement lever. OSHA 29 CFR 1910.101, NFPA 55 and FDA cGMP obligations effective December 2025 convert regulator selection from an engineering preference into an auditable record. Operators should demand traceable operating data at the point of specification, because the regulator that cannot log its own performance will eventually become a compliance liability.
The balance of evidence favors a premiumization thesis over a volume thesis. Total market growth near 4.3% understates the value shift: high-purity alloys at ~5.2% CAGR, hydrogen systems at ~5.0% and Middle East demand at ~5.6% all outrun the headline. Vendors pricing on cost per unit will participate in the slow half of the market.
The strongest counter-argument is that conventional regulators dominate installed base and will for a decade — welding shops and beverage distributors will not pay for IoT capability. That is correct on volume but wrong on margin. Our analysis suggests conventional products should be treated as a customer-acquisition channel that funds premium R&D, not as the growth story. The risk is a vendor that optimizes for conventional share and finds itself locked out of hydrogen and fab qualification cycles that take years to enter.
Actionable strategy:
What would change our conclusion: a sustained helium supply normalization combined with faster-than-expected hydrogen project FIDs would pull growth above 5.5%; conversely, durable tariff escalation and further PFAS requalification delays could compress the premium segment toward the base-case rate.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.3% from 2020-2034 |
| Segmentation |
|
It was estimated at USD 17.2 billion in 2025 and roughly USD 18.1 billion in 2026, with competing analyses placing the 2025–2026 range between USD 17.2 billion and USD 19.5 billion depending on scope.
Around 4.3% through 2035 on a value basis, though premium segments such as high-purity alloys, hydrogen systems and Middle East projects are expanding at roughly 5% or more.
Asia-Pacific led with about 31.7% of 2024 revenue, supported by semiconductor fabrication, steel decarbonization and refinery capacity, while the Middle East is the fastest-growing region.
Oil and gas accounted for about 58.9% of 2024 revenue, though hydrogen-linked energy transition applications are the fastest-growing application block.
Helium supply volatility, cyclical industrial capital spending, PFAS-free sealing requalification costs and tariff-driven dual-certification burdens all constrain the pace of expansion.
Air Liquide leads with over 8% share, and Air Liquide, Air Products, Airgas, Cavagna and Colfax together hold roughly 35% of the market.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the value chain with brass and stainless component suppliers, specialised regulator manufacturers, sealing and diaphragm formulators, and global industrial gas distributors. Respondents were designated at decision-maker level: VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads. Interview programmes captured specification behaviour, qualification timelines, tariff exposure and replacement-cycle economics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Technical Directors & Heads of R&D | 35% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Quality Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Component & Materials Suppliers | 30% |
| Regulator Manufacturers | 35% |
| Sealing & Diaphragm Formulators | 15% |
| Global Distributors & Gas Companies | 20% |
Demand and trade values were cross-checked against UN Comtrade, WTO tariff schedules, US ITC and Eurostat industrial production series, alongside corporate 10-K filings, investor presentations and patent activity in pressure-control and sealing technologies. Technical benchmarks were validated against OSHA 29 CFR 1910.101, NFPA 55, SEMI S2, ISO 80079-49 and FDA current good manufacturing practice requirements.
Top-down allocation from macroeconomic and end-use industry output runs simultaneously with bottom-up modelling of manufacturer capacity, product pricing and end-use consumption. Divergence between the two paths is reconciled at segment level before aggregation, with premium and conventional tiers modelled separately.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |