 Middle East Self Drilling Screws Market
 2026: $400M by 2035
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 214

Sandeep Singh
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Self Drilling Screws Market
Sandeep Singh
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 215.0 M |
| 2026 | 228.0 M |
| 2027 | 243.0 M |
| 2028 | 259.0 M |
| 2029 | 275.0 M |
| 2030 | 293.0 M |
| 2031 | 311.0 M |

The Middle East self drilling screws market covers fasteners with drill-point tips that form their own hole and thread in a single operation, sold into steel framing, cladding, solar racking, HVAC and industrial assembly across the GCC, Levant, Iraq and North Africa.
This report covers self-drilling screws by material (stainless, coated alloy, carbon steel), head type, drive, thread, length and end-use across six GCC states, the Levant and Iraq, and North Africa, with 2025 base-year sizing and 2026–2035 forecasts. This analysis does not cover self-tapping screws without drill points, welding fasteners, structural bolts, adhesives, or hand tools and drivers.
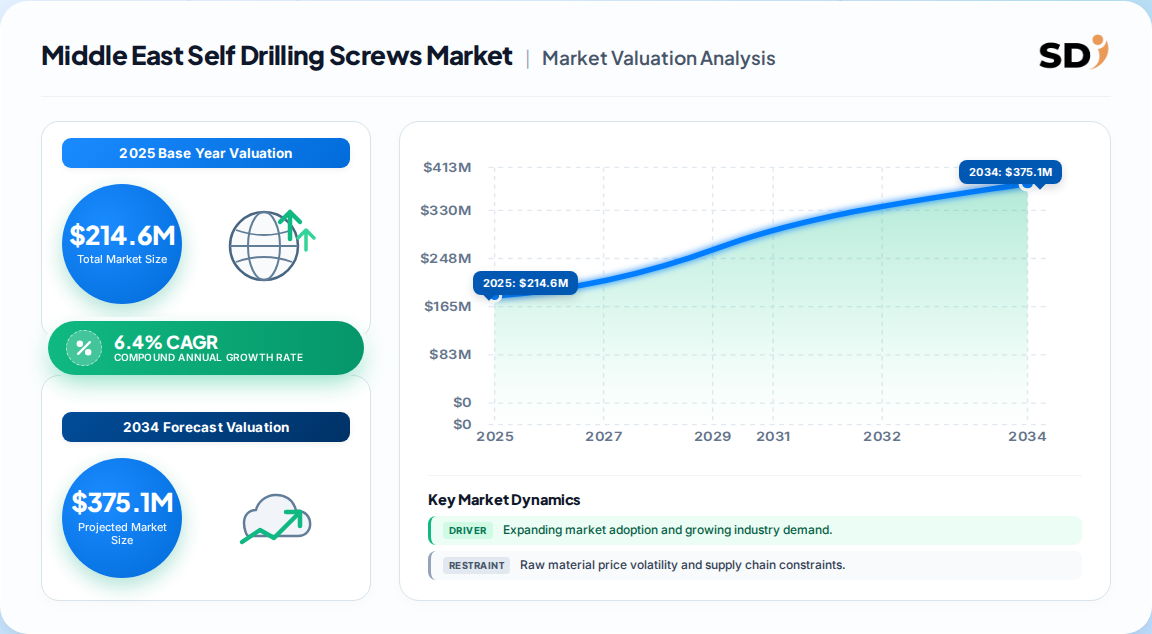
At USD 214.6 million in 2025, the regional base is small relative to global fastener spend but dense in project value: a handful of giga-programmes concentrate demand. The table below reconciles the competing published anchors.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 214.6M | 2025 | 2035 | 6.4% | Middle East regional consumption, manufacturer value | One published estimate (regional study) |
| USD 215.0M | 2025 | 2031 | ~6.4% | Same regional scope, year-table variant | Same source, alternate table |
| ~USD 39M (GCC imports) | 2019 | n/a | n/a | HS 731814 import value, six GCC states only | UN Comtrade / World Bank trade flows |
| USD 0.0686B (MEA) | 2025 | 2032 | 3.91% | MEA aggregate, all self-drilling screws | A competing analysis (global study) |
Our analysis suggests the USD 214.6 million figure is the most defensible regional anchor: it is directionally consistent with the 2019 GCC import base of roughly USD 39 million once nominal growth and post-2019 project inflation are applied, and it sits above the MEA-aggregate estimate's implied Middle East share. The 3.91% CAGR in the global study is a blended MEA number diluted by slower North African consumption; we regard 6.4% as the truer Gulf trajectory.
Segmentation matters here because material choice, not head style, determines who wins a tender. Stainless steel at 44% of value and coated alloy at 36% reflect salt-air and 50°C-plus service conditions.
| Parent | Children | 2025 share / note |
|---|---|---|
| Material | Stainless steel (A2/A4), alloy steel with ceramic/zinc-nickel coating, carbon steel | 44% / 36% / 20% (value) |
| Head type | Hex, flat/countersunk, pan, bugle | 46% / 22% / 18% / 14% |
| Drive type | Phillips, Torx, square, hex | Torx rising in racking |
| Thread type | Self-tapping, machine, metric, wood | Self-tapping dominant |
| Length | <1 in, 1–2 in, 2–3 in, >3 in | 1–3 in core range |
| End use | Construction, utilities & energy, manufacturing, automotive | 58% / 21% / 13% / 8% |
Saudi Arabia leads, carrying an estimated 42% of regional value on NEOM, Red Sea, Qiddiya and Diriyah steel intensity; the UAE follows at roughly 24%, functioning as the warehouse and re-export gateway for Oman, Qatar, Bahrain, Iraq and East Africa.
Growth is driven by giga-project steel intensity and utility-scale solar, while corrosion failure risk and import concentration are the binding restraints. The balance favours demand: drivers are structural and multi-year, restraints are largely solvable through inventory and specification strategy.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Giga-project steel framing | Driver | High | Self-drilling cuts fastening cycle from 11–13s to 7–8s per point |
| Utility-scale solar racking | Driver | High | 50% Saudi renewable target; anti-vibration coated screws |
| Labour cost and Saudization | Driver | Medium-high | Throughput-optimised systems reduce headcount per shift |
| Prefabrication shift | Driver | Medium | 35–40% of new GCC industrial builds are panelised |
| Extreme corrosion | Restraint | High | 1,000-hour salt-spray spec; commodity galvanised fails |
| Import concentration | Restraint | High | Red Sea disruption adds 3–6 weeks lead time |
| Low-tier import undercutting | Restraint | Medium | Non-certified screws 20–30% cheaper |
| Fragmented standards | Restraint | Medium | No unified Gulf fastener certification regime |
The market is served by global engineering-led fastener specialists competing against regional distributors, private-label importers and low-cost exporters. Differentiation rests on certification depth, coating performance and Gulf-held inventory rather than unit price.
| Vendor | Positioning | Regional moat |
|---|---|---|
| SFS Group | Premium envelopes, solar, bi-metal | Certified systems, colour-matched finishes |
| EJOT | Façade and roofing systems | Application-specific A2/A4 architecture |
| Hilti | Integrated contractor systems | Tools, magazines, engineering documents |
| ITW Buildex (TEKS) | Structural steel-to-steel | Drill-point and thread breadth |
| Simpson Strong-Tie | Engineered connections | Published load tables, ASTM alignment |
| Würth | Distribution and VMI | Inventory depth, OEM supply |
| Regional distributors | Re-export and kitting | Jebel Ali, Dammam, Hamad Port proximity |
Our analysis suggests the durable moat in this region is logistics, not manufacturing: a supplier holding certified stainless stock in Jebel Ali can out-compete a lower-cost mill on lead time alone.
Corrosion specification is the single most important purchase criterion in this region, far outweighing price sensitivity relative to other emerging markets. Buyers should treat 1,000-hour salt-spray rating and third-party certification as pass/fail gates, not negotiable line items. Non-certified imports undercut compliant product by 20–30%, and that gap is precisely where warranty disputes and rework costs originate on coastal hospitality and industrial assets.
Procurement risk is concentrated in lead time: Red Sea routing disruption has stretched European delivery windows from 4–5 weeks to 8–10 weeks on certain SKUs. Switching costs are moderate for commodity sizes but high for specified structural and racking fasteners, where load tables and tool compatibility are engineered into the package. Saudi Aramco and major developers increasingly require in-Kingdom value addition, so distributor-led assembly and kitting — rather than full manufacturing — is the practical compliance route.
The balance of evidence favours a supply-side, not demand-side, thesis. Demand is effectively underwritten by sovereign giga-programmes and renewable targets that are unlikely to be cancelled mid-cycle; the winners will be decided by who can hold certified, corrosion-rated inventory near the point of use.
The strongest counter-argument is price: if Chinese and Indian mills localise coating and certification, the specification premium that protects European and global specialists could compress within one procurement cycle. We take this seriously but judge it a 2029-plus risk, not a 2026 one, because Gulf certification regimes remain fragmented and developers still default to documented brands on prestige packages.
Actionable strategy:
Evidence that would change our conclusion: a unified Gulf-wide fastener certification regime, or verified localisation of coated stainless production inside Saudi Arabia, would erode the import-tier premium faster than our base case assumes.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.42% |
| UAE | 0.24% |
| Qatar | 0.09% |
| Kuwait | 0.07% |
| Oman | 0.06% |
| Bahrain | 0.03% |
| Levant & Iraq | 0.05% |
| North Africa | 0.04% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
It was valued at USD 214.6 million in 2025 and is projected to reach USD 399.8 million by 2035, expanding at a 6.4% CAGR driven by giga-project steel framing and utility-scale solar racking.
Saudi Arabia leads with roughly 42% of regional value, followed by the UAE at about 24%, which also functions as the warehouse and re-export gateway for Oman, Qatar, Bahrain and Iraq.
Coastal humidity, salt-laden air and summer temperatures above 50°C demand 1,000-hour salt-spray-rated fasteners, pushing stainless steel to 44% of regional value against carbon steel's 20%.
Import concentration: over 90% of premium volume arrives from China, India and Europe, and Red Sea disruption has extended European lead times from 4–5 weeks to 8–10 weeks on certain SKUs.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw material and steel wire suppliers, specialised screw producers and coaters, contract kitting and assembly operators, and global and regional fastener distributors. Decision-maker designations interviewed included VP-level Sourcing leads at contractors, Heads of R&D at coating specialists, Technical Directors at façade and racking system houses, and Commercial Operations Leads at Gulf distribution hubs. Interview programmes were stratified by country and end-use to avoid over-weighting Saudi giga-project views.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Technical & R&D Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Certification Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Screw Producers & Coaters | 40% |
| Distributors & Re-exporters | 30% |
| Steel Wire & Raw Material Suppliers | 18% |
| Kitting & Assembly Operators | 12% |
Trade flows were validated against UN Comtrade and World Bank HS 731814 import series, WTO tariff schedules, US ITC and Eurostat mirror statistics, and corporate annual filings and investor presentations from listed fastening groups. Patent databases and recognised technical standards bodies — including ASTM, ISO and regional building-code authorities — were used to benchmark corrosion and load-performance specifications.
Top-down allocation from macroeconomic construction and renewable-capacity forecasts was run simultaneously with bottom-up manufacturer capacity, product pricing and end-use consumption modelling. Divergences between the two approaches were reconciled at country and sub-segment level before the base-year value was fixed.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2026–2035 compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, commercial filings | High |