Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Electric Fireplace Market Size, Share & Growth 2026-2033
Electric Fireplace Market
Electric Fireplace Market Size, Share & Growth 2026-2033
Electric Fireplace Market by Installation Type (Wall Mounted, Insert, Built-In, Free Standing, Mantel, Tabletop), by Projection Type (LCD, LED, Holographic), by Heating (With Heater, Flame-Only), by Category (One-Sided, Multi-Sided), by Application (Residential, Commercial), by Size (Small, Medium, Large, Extra Large), by Distribution Channel (B2C Retail, B2B Project), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands, Spain, Nordics), by Asia Pacific (China, Japan, India, South Korea, Australia, Southeast Asia), by Latin America (Brazil, Argentina, Colombia, Chile), by Middle East & Africa (Saudi Arabia, UAE, Turkey, South Africa) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 272
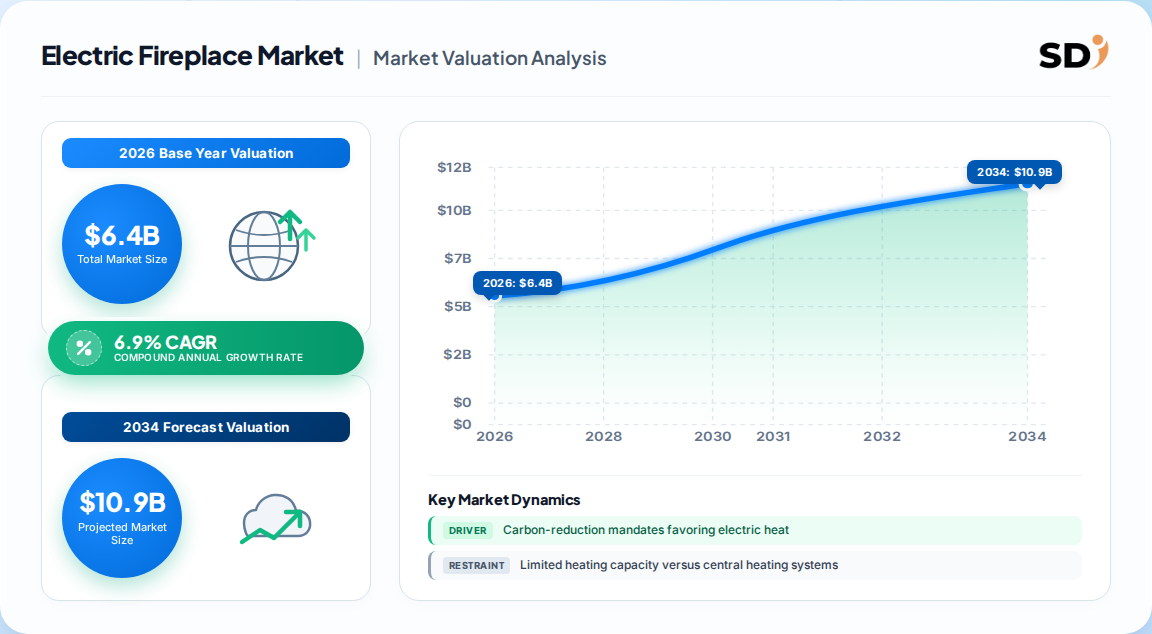
USD 6.4 Billion in 2026, the global electric fireplace market is forecast to double to USD 10.2 Billion by 2033, advancing at a 6.9% CAGR, though a competing published estimate places the 2025 base at USD 5.9 Billion with a 3.5–4.1% trajectory.
Wall-mounted units dominate installation share at 48.5% (2025), while built-in and insert formats post the fastest growth as media-wall construction accelerates.
North America leads with roughly 35–42% of global revenue, and Asia-Pacific is the fastest-growing region, expanding at nearly double the global rate on urban housing and air-quality regulation.
LCD projection now commands 65% of revenue in mature markets, yet LED is the fastest-growing projection type at 7.2% CAGR, meaning incumbents face technology swap risk.
A consolidated leader tier — Glen Dimplex/Dimplex, Twin-Star (Duraflame), Napoleon, Hearth & Home Technologies, Amantii, Touchstone — controls an estimated medium-concentration competitive field.
B2C retail holds 63% of channel share, but B2B/project sales are growing faster at 6.65% CAGR, driven by multifamily and hospitality specifications.
Why this matters for decision-makers: the spread between a 6.9% and a 3.5% CAGR is not a data quirk — it reflects whether buyers model electric fireplaces as decorative electronics or supplemental heating appliances. Vendors and investors must commit to one positioning, because the product roadmap, price ladder and channel investment diverge completely.
Electric Fireplace Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
5.900 B
2025
6.400 B
2026
6.800 B
2027
7.300 B
2028
7.800 B
2029
8.300 B
2030
8.900 B
2031
Electric Fireplace Market Size (In Billion)
Year
Market Size
2025
5.900 B
2026
6.400 B
2027
6.800 B
2028
7.300 B
2029
7.800 B
2030
8.300 B
2031
8.900 B
What is the Electric Fireplace Market?
The electric fireplace market covers manufactured hearth products — wall-mounted, built-in, insert, freestanding, mantel and tabletop units — that produce flame visuals via LCD/LED projection and optional supplemental heat via resistive or infrared elements. Units require no chimney, gas line or venting, and are sold through retail and project channels into residential and commercial interiors.
Scope: what this report covers and excludes
This analysis covers global electric hearth products across installation type (wall-mounted, insert, freestanding, built-in, mantel, tabletop), projection technology (LCD, LED, holographic), heating (with heater, flame-only), application (residential, commercial) and distribution (B2C retail, B2B project).
This analysis does not cover gas, wood-burning or bioethanol hearths, permanent electric baseboard or heat-pump systems, outdoor fire pits, or the upstream semiconductor and display-panel supply chain, each of which is addressed in separate coverage.
How big is the market for Electric Fireplace Market?
The most defensible 2025 base is approximately USD 5.9–6.4 Billion globally, with a 2033 forecast near USD 10.2 Billion at 6.9% CAGR; lower estimates of USD 2.5–2.8 Billion reflect narrower definitions restricted to fixed-hearth appliances excluding decor-led formats.
Our analysis: the divergence is definitional, not factual. The USD 5.9 Billion figure reconciles to U.S. revenue of roughly USD 1.7–1.9 Billion at a 35% North American share, which is internally consistent with the U.S. country estimate. The USD 2.5 Billion series implies a U.S. market of under USD 1 Billion, which is difficult to support once wall-mounted and tabletop units are included. Buyers should treat the broad definition as the true addressable pool and the narrow series as a proxy for the fixed-hearth appliance sub-market only.
How is the market segmented?
Segmentation hinges on installation type and projection technology: wall-mounted formats anchor volume and revenue, while built-in and insert units carry the premium and the growth.
So what: the revenue centre of gravity (wall-mounted, LCD, one-sided, small) is not where the growth is (built-in, LED, medium-format, B2B). That mismatch is the single most important planning fact in this dataset.
Which region leads in Electric Fireplace Market?
North America leads the global electric fireplace market with roughly 35–42% of revenue, supported by a mature retrofit base, high average selling prices and all-electric building mandates; Asia-Pacific is the fastest-growing region at 8.27% CAGR.
Electric Fireplace Market Regional Market Share
Loading chart...
Electric Fireplace Market Regional Market Share
Region
Market Share (%)
North America
0.36%
Europe
0.24%
Asia-Pacific
0.27%
Latin America
0.07%
Middle East & Africa
0.06%
Global
North America — United States, Canada, Mexico
Europe — Germany, United Kingdom, France, Italy, Netherlands, Spain, Nordics
Asia-Pacific — China, Japan, India, South Korea, Australia, Southeast Asia
Latin America — Brazil, Argentina, Colombia, Chile
Middle East & Africa — Saudi Arabia, UAE, Turkey, South Africa
Implication: North America delivers cash today, Asia-Pacific delivers growth tomorrow. A vendor with a single global SKU strategy will over-serve North America's premium wall-mounted demand and under-serve Asia-Pacific's compact, price-competitive apartment formats.
What is driving growth — and what is holding it back?
Growth is driven by decarbonization mandates, retrofit economics and smart-home integration, which together add roughly 3.2 percentage points of CAGR; the binding constraint is limited heating capacity and electricity-price sensitivity, which caps the category as a supplemental rather than primary heat source.
Factor
Direction
Evidence strength
Mechanism
Carbon-reduction mandates favoring electric heat
Driver
Strong (+1.2% CAGR)
All-electric building codes displace gas inserts
Municipal bans on wood/gas hearths
Driver
Strong (+0.8%)
Removes combustion alternatives in urban zones
Smart-home integration
Driver
Strong (+1.1%)
App/voice control supports premium pricing
Renovation and media-wall boom
Driver
Moderate (+0.9%)
Plug-in retrofit without permits or flues
E-commerce channel expansion
Driver
Moderate (+0.4%)
Widens reach, compresses entry-level pricing
Limited heating capacity vs. central systems
Restraint
Strong
Confines units to zone/supplemental heating
High electricity tariffs (notably Europe)
Restraint
Moderate
Weakens operating-cost case vs. heat pumps
OEM price pressure at entry level
Restraint
Moderate
Margin compression in sub-USD 300 tier
Balance of evidence: the drivers are regulatory and structural, which makes them durable; the restraints are economic and cyclical, which makes them volatile. Our analysis suggests the regulatory tailwind outlasts the tariff headwind, but only in jurisdictions that have actually codified all-electric mandates — a distinction that regional averages conceal.
Who are the leading vendors?
The vendor field is medium-concentration, led by Glen Dimplex/Dimplex and Twin-Star (Duraflame) at scale, with Napoleon, Hearth & Home Technologies, Amantii, Touchstone and ClassicFlame occupying premium and design-led niches.
Vendor
HQ
Position
Basis of differentiation
Glen Dimplex / Dimplex
Canada / Ireland
Global scale leader
Broad portfolio, brand heritage, trade distribution
Competitive moats: distribution (dealer and mass-retail shelf space) and flame-visual IP are the durable advantages. Smart-home firmware is not a moat — it is converging fast and will migrate to commodity status within the forecast window, our analysis suggests.
What do buyers and operators need to know?
Procurement decisions turn on five mission-critical criteria: flame realism under ambient light, heater wattage and zone-heating coverage, compliance with local electrical and Ecodesign rules, installation framing tolerance, and serviceability of the LED/LCD module.
Switching costs are asymmetric. Retail buyers face low switching costs and buy on aesthetics and price; project buyers (multifamily, hospitality, senior living) face high switching costs because the unit must fit standardized rough openings, pass electrical inspection and remain serviceable for a decade. Vendors that publish framing specifications and offer low-profile recessed kits win project specifications; those that do not are confined to the retail cycle.
Regulatory exposure is real but uneven. European Ecodesign requirements for electronic thermostats and open-window detection already shape product design, and North American all-electric codes are expanding the addressable retrofit pool. Buyers should verify that flame-only units marketed as heaters carry accurate rated output, since overstated BTU claims are the most common compliance failure in this category.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the broad definition and the higher growth path: a ~USD 6.4 Billion 2026 market compounding near 6.9% to USD 10.2 Billion by 2033. The strongest counter-argument is that electric fireplaces are discretionary decor, and a housing or renovation downturn would compress the category faster than the regulatory tailwind can offset. That risk is genuine — but it is concentrated in the retail wall-mounted tier, not in the project channel where specification cycles are longer.
Our judgment is that the category is undergoing a quiet repositioning from hearth to connected interior appliance. The winners will not be the vendors with the most realistic flame; they will be the vendors who own the rough opening, the framing standard and the service relationship. Flame realism is becoming table stakes, and margin will migrate to installation ecosystems and project specification.
Actionable strategy:
Investors: underwrite targets on project-channel mix and installation-ecosystem attachment, not on retail unit volume; the B2B CAGR premium (6.65% vs. 4%-class retail) is the valuation lever.
Operators: standardize recessed framing and publish rough-opening specs to convert retail brand equity into specification wins in multifamily and hospitality.
Vendors: hedge the LCD-to-LED transition now — LED's 7.2% CAGR against LCD's dominant installed base signals a technology swap that will strand inventory.
What would change our conclusion: evidence that all-electric building codes are being delayed or rolled back in California or New York, or a sustained doubling of residential electricity tariffs in Europe, would push us toward the conservative 3.5–4.1% CAGR series and a smaller addressable pool.
Electric Fireplace Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Electric Fireplace Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.9% from 2020-2034
Segmentation
By Installation Type
Wall Mounted
Insert
Built-In
Free Standing
Mantel
Tabletop
By Projection Type
LCD
LED
Holographic
By Heating
With Heater
Flame-Only
By Category
One-Sided
Multi-Sided
By Application
Residential
Commercial
By Size
Small
Medium
Large
Extra Large
By Distribution Channel
B2C Retail
B2B Project
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Netherlands
Spain
Nordics
Asia Pacific
China
Japan
India
South Korea
Australia
Southeast Asia
Latin America
Brazil
Argentina
Colombia
Chile
Middle East & Africa
Saudi Arabia
UAE
Turkey
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Installation Type
5.1.1. Wall Mounted
5.1.2. Insert
5.1.3. Built-In
5.1.4. Free Standing
5.1.5. Mantel
5.1.6. Tabletop
5.2. Market Analysis, Insights and Forecast - by Projection Type
5.2.1. LCD
5.2.2. LED
5.2.3. Holographic
5.3. Market Analysis, Insights and Forecast - by Heating
5.3.1. With Heater
5.3.2. Flame-Only
5.4. Market Analysis, Insights and Forecast - by Category
5.4.1. One-Sided
5.4.2. Multi-Sided
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Residential
5.5.2. Commercial
5.6. Market Analysis, Insights and Forecast - by Size
5.6.1. Small
5.6.2. Medium
5.6.3. Large
5.6.4. Extra Large
5.7. Market Analysis, Insights and Forecast - by Distribution Channel
5.7.1. B2C Retail
5.7.2. B2B Project
5.8. Market Analysis, Insights and Forecast - by Region
5.8.1. North America
5.8.2. Europe
5.8.3. Asia Pacific
5.8.4. Latin America
5.8.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Installation Type
6.1.1. Wall Mounted
6.1.2. Insert
6.1.3. Built-In
6.1.4. Free Standing
6.1.5. Mantel
6.1.6. Tabletop
6.2. Market Analysis, Insights and Forecast - by Projection Type
6.2.1. LCD
6.2.2. LED
6.2.3. Holographic
6.3. Market Analysis, Insights and Forecast - by Heating
6.3.1. With Heater
6.3.2. Flame-Only
6.4. Market Analysis, Insights and Forecast - by Category
6.4.1. One-Sided
6.4.2. Multi-Sided
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Residential
6.5.2. Commercial
6.6. Market Analysis, Insights and Forecast - by Size
6.6.1. Small
6.6.2. Medium
6.6.3. Large
6.6.4. Extra Large
6.7. Market Analysis, Insights and Forecast - by Distribution Channel
6.7.1. B2C Retail
6.7.2. B2B Project
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Installation Type
7.1.1. Wall Mounted
7.1.2. Insert
7.1.3. Built-In
7.1.4. Free Standing
7.1.5. Mantel
7.1.6. Tabletop
7.2. Market Analysis, Insights and Forecast - by Projection Type
7.2.1. LCD
7.2.2. LED
7.2.3. Holographic
7.3. Market Analysis, Insights and Forecast - by Heating
7.3.1. With Heater
7.3.2. Flame-Only
7.4. Market Analysis, Insights and Forecast - by Category
7.4.1. One-Sided
7.4.2. Multi-Sided
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Residential
7.5.2. Commercial
7.6. Market Analysis, Insights and Forecast - by Size
7.6.1. Small
7.6.2. Medium
7.6.3. Large
7.6.4. Extra Large
7.7. Market Analysis, Insights and Forecast - by Distribution Channel
7.7.1. B2C Retail
7.7.2. B2B Project
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Installation Type
8.1.1. Wall Mounted
8.1.2. Insert
8.1.3. Built-In
8.1.4. Free Standing
8.1.5. Mantel
8.1.6. Tabletop
8.2. Market Analysis, Insights and Forecast - by Projection Type
8.2.1. LCD
8.2.2. LED
8.2.3. Holographic
8.3. Market Analysis, Insights and Forecast - by Heating
8.3.1. With Heater
8.3.2. Flame-Only
8.4. Market Analysis, Insights and Forecast - by Category
8.4.1. One-Sided
8.4.2. Multi-Sided
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Residential
8.5.2. Commercial
8.6. Market Analysis, Insights and Forecast - by Size
8.6.1. Small
8.6.2. Medium
8.6.3. Large
8.6.4. Extra Large
8.7. Market Analysis, Insights and Forecast - by Distribution Channel
8.7.1. B2C Retail
8.7.2. B2B Project
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Installation Type
9.1.1. Wall Mounted
9.1.2. Insert
9.1.3. Built-In
9.1.4. Free Standing
9.1.5. Mantel
9.1.6. Tabletop
9.2. Market Analysis, Insights and Forecast - by Projection Type
9.2.1. LCD
9.2.2. LED
9.2.3. Holographic
9.3. Market Analysis, Insights and Forecast - by Heating
9.3.1. With Heater
9.3.2. Flame-Only
9.4. Market Analysis, Insights and Forecast - by Category
9.4.1. One-Sided
9.4.2. Multi-Sided
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Residential
9.5.2. Commercial
9.6. Market Analysis, Insights and Forecast - by Size
9.6.1. Small
9.6.2. Medium
9.6.3. Large
9.6.4. Extra Large
9.7. Market Analysis, Insights and Forecast - by Distribution Channel
9.7.1. B2C Retail
9.7.2. B2B Project
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Installation Type
10.1.1. Wall Mounted
10.1.2. Insert
10.1.3. Built-In
10.1.4. Free Standing
10.1.5. Mantel
10.1.6. Tabletop
10.2. Market Analysis, Insights and Forecast - by Projection Type
10.2.1. LCD
10.2.2. LED
10.2.3. Holographic
10.3. Market Analysis, Insights and Forecast - by Heating
10.3.1. With Heater
10.3.2. Flame-Only
10.4. Market Analysis, Insights and Forecast - by Category
10.4.1. One-Sided
10.4.2. Multi-Sided
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Residential
10.5.2. Commercial
10.6. Market Analysis, Insights and Forecast - by Size
10.6.1. Small
10.6.2. Medium
10.6.3. Large
10.6.4. Extra Large
10.7. Market Analysis, Insights and Forecast - by Distribution Channel
10.7.1. B2C Retail
10.7.2. B2B Project
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Glen Dimplex / Dimplex
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Twin-Star International (Duraflame)
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Napoleon Fireplaces
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Hearth & Home Technologies
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Amantii
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Touchstone
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. ClassicFlame
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Real Flame
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
12. Research Methodology
List of Figures
Figure 1: Electric Fireplace Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Electric Fireplace Market Revenue (Billion), by Installation Type 2026 & 2034
Figure 3: North America Electric Fireplace Market Revenue Share (%), by Installation Type 2026 & 2034
Figure 4: North America Electric Fireplace Market Revenue (Billion), by Projection Type 2026 & 2034
Figure 5: North America Electric Fireplace Market Revenue Share (%), by Projection Type 2026 & 2034
Figure 6: North America Electric Fireplace Market Revenue (Billion), by Heating 2026 & 2034
Figure 7: North America Electric Fireplace Market Revenue Share (%), by Heating 2026 & 2034
Figure 8: North America Electric Fireplace Market Revenue (Billion), by Category 2026 & 2034
Figure 9: North America Electric Fireplace Market Revenue Share (%), by Category 2026 & 2034
Figure 10: North America Electric Fireplace Market Revenue (Billion), by Application 2026 & 2034
Figure 11: North America Electric Fireplace Market Revenue Share (%), by Application 2026 & 2034
Figure 12: North America Electric Fireplace Market Revenue (Billion), by Size 2026 & 2034
Figure 13: North America Electric Fireplace Market Revenue Share (%), by Size 2026 & 2034
Figure 14: North America Electric Fireplace Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 15: North America Electric Fireplace Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 16: North America Electric Fireplace Market Revenue (Billion), by Country 2026 & 2034
List of Tables
Table 1: Electric Fireplace Market Revenue Billion Forecast, by Installation Type 2020 & 2034
Table 2: Electric Fireplace Market Revenue Billion Forecast, by Projection Type 2020 & 2034
Table 3: Electric Fireplace Market Revenue Billion Forecast, by Heating 2020 & 2034
Table 4: Electric Fireplace Market Revenue Billion Forecast, by Category 2020 & 2034
Table 5: Electric Fireplace Market Revenue Billion Forecast, by Application 2020 & 2034
Table 6: Electric Fireplace Market Revenue Billion Forecast, by Size 2020 & 2034
Table 7: Electric Fireplace Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 8: Electric Fireplace Market Revenue Billion Forecast, by Region 2020 & 2034
Table 9: North America Electric Fireplace Market Revenue Billion Forecast, by Installation Type 2020 & 2034
Table 10: North America Electric Fireplace Market Revenue Billion Forecast, by Projection Type 2020 & 2034
Table 11: North America Electric Fireplace Market Revenue Billion Forecast, by Heating 2020 & 2034
Table 12: North America Electric Fireplace Market Revenue Billion Forecast, by Category 2020 & 2034
Table 13: North America Electric Fireplace Market Revenue Billion Forecast, by Application 2020 & 2034
Table 14: North America Electric Fireplace Market Revenue Billion Forecast, by Size 2020 & 2034
Table 15: North America Electric Fireplace Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 16: North America Electric Fireplace Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1. What is the electric fireplace market size in 2026?
The global market is estimated at USD 6.4 Billion in 2026, forecast to reach USD 10.2 Billion by 2033 at a 6.9% CAGR. Narrower definitions limited to fixed hearth appliances produce estimates of USD 2.5–2.8 Billion.
2. Which region dominates electric fireplace demand?
North America leads with roughly 35–42% of global revenue, driven by a mature retrofit market and higher average selling prices. Asia-Pacific is the fastest-growing region at an estimated 8.27% CAGR through 2031.
3. What is the fastest-growing electric fireplace segment?
Built-in and insert formats are growing fastest, alongside medium-format units of 45–60 inches at 7.84% CAGR and B2B project sales at 6.65% CAGR. LED projection is also outpacing LCD at 7.2% CAGR.
4. Who are the leading electric fireplace manufacturers?
Glen Dimplex/Dimplex, Twin-Star (Duraflame), Napoleon, Hearth & Home Technologies, Amantii, Touchstone, ClassicFlame and Real Flame lead a medium-concentration field, competing on distribution reach, flame IP and project specification.
5. Why do published market sizes differ so widely?
Estimates diverge on definition, not on underlying demand. Broad series include wall-mounted, tabletop and decorative formats; narrow series count only fixed hearth appliances. Buyers should match the definition to their actual addressable segment.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the value chain with display-panel and electronic component suppliers, specialized electric hearth OEMs, contract manufacturers serving retail brands, and regional wholesale distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of Product Development, Technical Directors (electrical compliance) and Commercial Operations Leads across retail and project channels. Interview programmes were designed to capture unit economics, framing specifications, warranty return rates and specification-win drivers.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement Leads
35%
Product Development & R&D Heads
30%
Technical & Compliance Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Component & Display Suppliers
30%
Electric Hearth OEMs
40%
Contract Manufacturers
15%
Distributors & Retailers
15%
Secondary Benchmarking & Public Trade Validation
All sizing is cross-validated against official multilateral and national databases, including UN Comtrade and WTO tariff schedules for hearth and electrical appliance codes, US ITC and Eurostat trade flows, and corporate annual filings (10-K, SEC submissions, investor presentations) for listed and bond-issuing manufacturers. Patent filings for flame-effect projection and smart-control firmware were reviewed to map technology substitution. Recognized technical standards and non-profit industry bodies were used to anchor compliance parameters and product classification.
Demand Modeling & Market Sizing Triangulation
Sizing is triangulated simultaneously Top-Down — allocating macroeconomic construction, renovation and appliance-spend aggregates to electric hearth categories — and Bottom-Up, modelling manufacturer capacity, average selling prices by format, and end-use consumption across residential, multifamily and commercial channels. Divergent published estimates are reconciled by normalizing product definitions before comparison.
 Electric Fireplace Market