 Woodworking Machinery Market
: Size, CAGR & 2031 Outlook
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 277

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Woodworking Machinery Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 5.250 B |
| 2026 | 5.490 B |
| 2027 | 5.750 B |
| 2028 | 6.030 B |
| 2029 | 6.320 B |
| 2030 | 6.620 B |
| 2031 | 6.940 B |

The woodworking machinery market covers the industrial equipment used to cut, shape, drill, sand, bond and finish wood and engineered wood products. It spans manual and semi-automatic tools through fully automatic CNC routers, panel saws, edgebanders and drilling lines sold to furniture, construction, cabinetry and flooring producers.
This report covers global demand for woodworking machinery by product type, operating principle, end-user industry and geography, with value forecasts to 2031. It analyzes vendors, procurement dynamics, regulatory drivers and competitive positioning.
This analysis does not cover hand-held power tools, forestry and logging equipment, sawmill primary breakdown lines, wood pellets or biomass processing, or the wood products themselves. Adjacent automation software is covered only where bundled with machinery.
Published estimates diverge sharply depending on whether hand-held tools, aftermarket parts and traditional machinery are counted. The table below compares the leading published figures and their scope definitions.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 5.49B → 6.94B | 2026 | 2031 | 4.78% | Industrial woodworking machinery, value | One published estimate |
| USD 5.2B → 8.0B | 2023 | 2033 | 4.5% | Woodworking machines, global sales | Trade press citing Fact.MR |
| USD 20.3B → 27.7B | 2025 | 2033 | 4.1% | Broad machinery incl. tools, saws, planers | A competing analysis |
The USD 5.49 billion figure is the most defensible for industrial buyers: it isolates programmable and semi-automatic production equipment where procurement decisions actually occur. Our analysis suggests the USD 20 billion-plus estimate reflects a wider basket that blends stationary tools and aftermarket components, which inflates the base but dilutes the growth signal.
Segmentation follows three non-geographic axes: product type, operating principle and end-user industry. The structure below drives virtually all purchasing decisions in this category.
| Axis | Segments | 2025 share / growth signal |
|---|---|---|
| Product type | CNC routers, panel saws, edgebanders, drilling lines, planers, sanders, others | CNC routers 36.1% share, 5.8% CAGR |
| Operating principle | Conventional/manual, semi-automatic, fully automatic CNC | Semi-automatic 49.3%; full CNC 6.1% CAGR |
| End-user industry | Furniture, construction, flooring, cabinetry, others | Furniture 53.8% share, 5.2% CAGR |
Asia-Pacific leads with 40.8% of 2025 value, anchored by Chinese, Vietnamese and Indian furniture production. Europe follows on strength in high-precision German and Italian machinery, while South America posts the fastest growth at 6.7% CAGR.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.41% |
| Europe | 0.32% |
| North America | 0.18% |
| South America | 0.05% |
| Middle East & Africa | 0.04% |
| Region | 2025 share |
|---|---|
| Asia-Pacific | 41% |
| Europe | 32% |
| North America | 18% |
| South America | 5% |
| Middle East & Africa | 4% |
The regional split reveals a two-speed market. Asia-Pacific's share is volume-led and price-sensitive, while Europe's 32% is value-led and skews toward automated cells. This divergence implies vendors must run dual product strategies: cost-optimized platforms for Asian volume and high-specification CNC systems for European margin.
Growth is being pulled by construction recovery, labor substitution and customization demand, while high capital costs and the skilled-operator shortage cap adoption among smaller shops.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Labor cost pressures | Driver +1.4% CAGR | Strong | Automation replaces scarce skilled labor |
| Construction expansion | Driver +1.3% CAGR | Strong | Lifts cabinetry, millwork, doors demand |
| Furniture manufacturing boom | Driver +1.2% CAGR | Strong | Drives CNC router and edgebander investment |
| Modular/customized furniture | Driver +0.9% CAGR | Medium | Requires flexible nesting and software workflows |
| High initial investment | Restraint | Medium | Limits SME adoption, especially in emerging markets |
| Skilled operator shortage | Restraint | Medium | Undermines utilization and payback |
The net balance favors growth, but the restraints are structural rather than cyclical. Our analysis suggests the binding constraint through 2031 is not demand but the availability of trained CNC programmers. Vendors that bundle training and service contracts will convert more mid-market deals than those competing on machine price alone.
The competitive landscape is moderately concentrated, with European incumbents dominating high-specification automation and a fragmented regional tier serving local furniture clusters.
| Company | Headquarters | Strategic positioning |
|---|---|---|
| HOMAG | Germany | Full-line CNC and networked production systems |
| SCM Group | Italy | Broad portfolio across furniture and construction |
| Biesse | Italy | Integrated machining cells and software |
| Weinig | Germany | Solid-wood machining and planing specialist |
| IMA Schelling | Germany | Panel processing and edgebanding lines |
| Felder | Austria | Premium woodworking machinery and service network |
| Stanley Black & Decker | USA | Stationary and light industrial tools |
Differentiation rests on control software, tool management and after-sales ecosystems rather than iron. The moats are real: installed-base service networks create switching costs, and CAD/CAM integration locks buyers into a vendor's tooling and data environment. Chinese suppliers are closing the hardware gap but remain thin on European service coverage, a gap that matters most in uptime-sensitive plants.
Selection should be driven by total cost of ownership, not sticker price. Buyers should weight software integration capability, tooling availability, spare-parts lead times and service response times, because these determine real uptime in variable-batch production.
Procurement risks cluster around installation and training: under-scoped operator training is the leading cause of poor utilization and delayed payback. Switching costs rise sharply once CAD/CAM workflows and tool libraries are vendor-specific, so negotiate data portability and open interfaces before signing.
Regulatory compliance is becoming a purchasing criterion. The EU Deforestation Regulation will require detailed material traceability at the end of 2026, favoring machinery with documentation and batch-segregation capability. Operators targeting EU export markets should treat digital traceability as a specification, not an add-on.
The balance of evidence favors a steady, mid-single-digit expansion led by automation substitution rather than new capacity. The most credible counter-argument is that a sharper Chinese construction downturn could suppress Asian volume faster than European premium demand offsets it. We judge that risk real but secondary: labor substitution is largely independent of housing cycles.
Our analysis suggests the value pool is shifting decisively toward software-connected cells and service revenue. Hardware margins will compress as Asian builders scale, while integrated suppliers capture premium projects through traceability, training and uptime guarantees. Vendors pricing solely on machine capability are exposed.
Evidence that would change this conclusion: a sustained fall in housing starts below 1.2 million annualized in the US, or a rapid compression in Chinese CNC pricing that erodes European share faster than the service moat defends.
While this overview covers market-level dynamics, precise sub-segment forecasting, country-level demand curves and vendor share modeling require the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
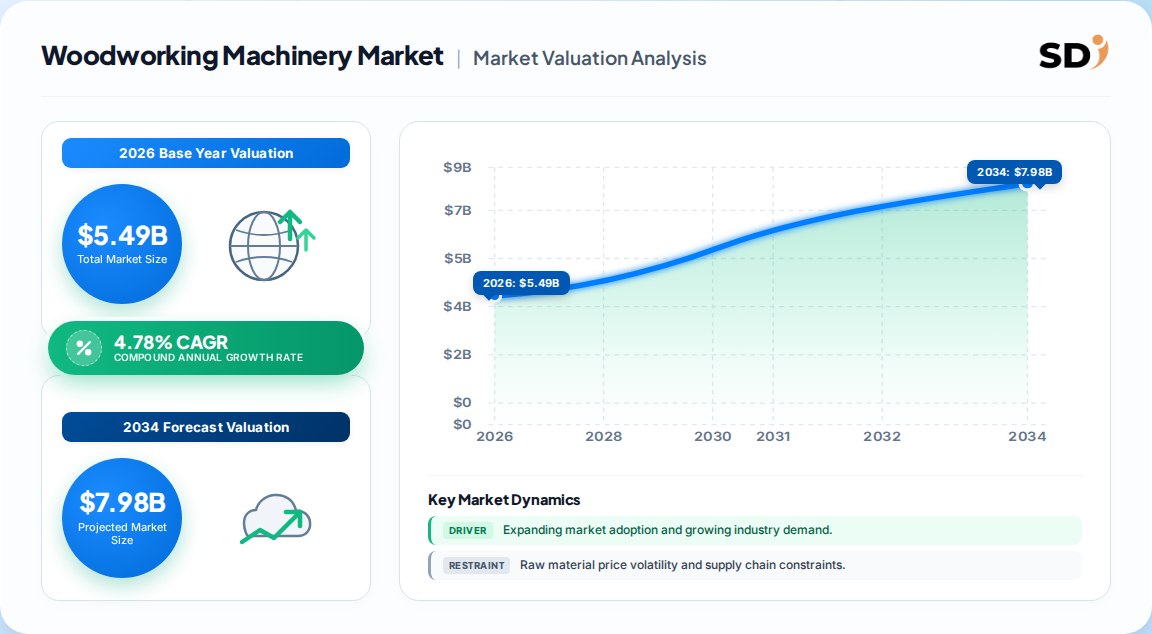
| Growth Rate | CAGR of 4.78% from 2020-2034 |
| Segmentation |
|
The global woodworking machinery market is valued at USD 5.49 billion in 2026 and is projected to reach USD 6.94 billion by 2031, registering a 4.78% CAGR over the forecast period.
CNC routers led with 36.1% of 2025 value and are projected to grow at 5.8% CAGR, the fastest product category, driven by nesting-based panel processing and customization demand.
Asia-Pacific held 40.8% of 2025 value, anchored by Chinese, Vietnamese and Indian furniture production. Europe follows with roughly 32%, concentrated in high-precision automated systems.
Fully automatic CNC equipment is the fastest-growing operating segment at 6.1% CAGR, as manufacturers replace manual workflows to offset labor costs and raise throughput.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including component and tooling suppliers, specialized machinery producers, system integrators and global distributors. Interviewees were selected across decision-maker designations including VP of Sourcing, Heads of Manufacturing Engineering, Technical Directors and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| Manufacturing & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Machinery Producers & OEMs | 45% |
| Component & Tooling Suppliers | 25% |
| Distributors & Dealers | 20% |
| End-User Manufacturers | 10% |
Findings were benchmarked against official multilateral trade databases including UN Comtrade, WTO tariff data, US ITC and Eurostat, supplemented by corporate annual filings and investor presentations, patent activity and recognized technical standards bodies and industry associations.
We run simultaneous top-down allocation from macroeconomic and end-use industry segments and bottom-up modeling of manufacturer capacity, product pricing and end-use consumption. Divergences between the two approaches are reconciled against trade flow evidence to produce a single defensible value estimate.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |