Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Incinerator Market Outlook 2026: Size, Shares & Trends
Incinerator Market
Incinerator Market Outlook 2026: Size, Shares & Trends
Incinerator Market by Incineration Technology (Mass Burn, Fluidized Bed, Rotary Kiln, Modular, Moving Grate, Static/Multiple Hearth), by Waste Type (Municipal Solid Waste, Industrial Waste, Hazardous Waste, Biomedical/Medical Waste, Agricultural Waste), by Application (Energy Recovery, Waste-to-Energy, Volume Reduction, Environmental Protection), by Control Technology (Emission Control Systems, Flue Gas Treatment, Heat Recovery Systems), by Operating Capacity (Small ≤50 t/day, Medium 51–200 t/day, Large >200 t/day, Modular), by End Use (Municipal, Industrial), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Nordics, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Southeast Asia, Australia), by Latin America (Brazil, Argentina, Colombia, Chile, Peru), by Middle East & Africa (Saudi Arabia, UAE, Turkey, Egypt, South Africa) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 233
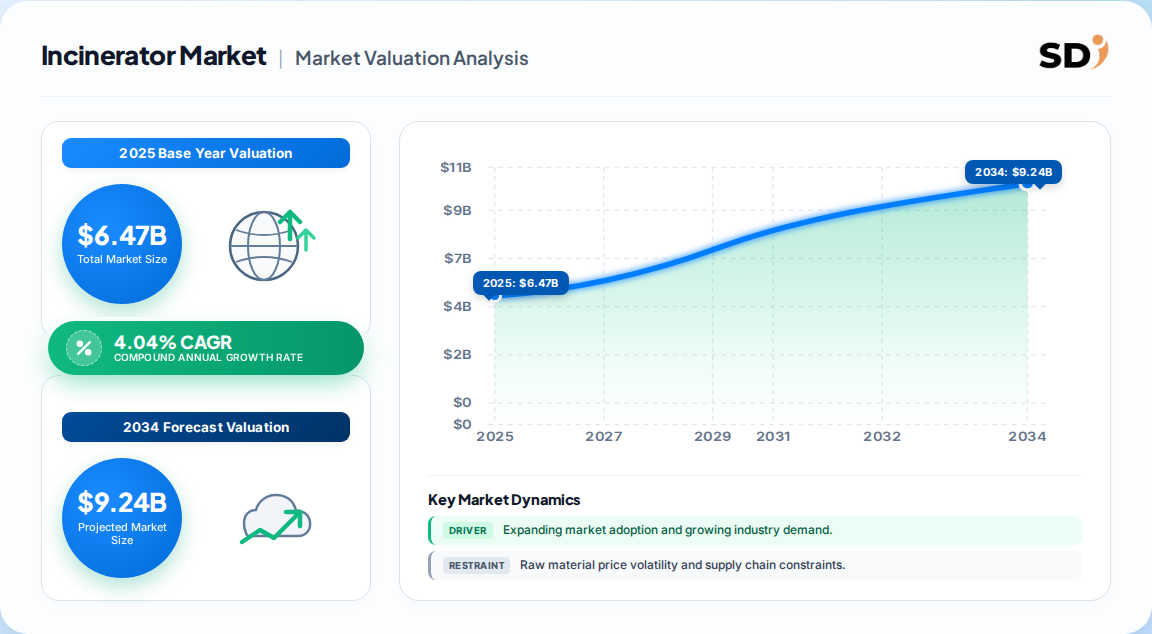
USD 6.47 Billion in 2025, the global incinerator market is projected to reach USD 9.61 Billion by 2035, expanding at a 4.04% CAGR (2025–2035).
Mass burn incineration remains the largest technology segment, while fluidized bed is the fastest-growing, favored for fuel flexibility and lower emissions.
Asia-Pacific is the fastest-growing region (led by China at ~5.2% CAGR in industrial waste incinerators), while North America retains the largest installed base and revenue share.
Municipal solid waste dominates by waste type; industrial hazardous waste and medical waste are the fastest-growing niches, driven by regulation and sterilization needs.
Leading vendors include Veolia, SUEZ, Covanta, Babcock & Wilcox, Hitachi Zosen and Kawasaki Heavy Industries, with Keppel Seghers and Thermax notable in WtE and industrial segments.
Energy recovery and emission control are the twin commercial engines: WtE plants convert disposal into electricity/heat, while tighter flue-gas rules force retrofit and new-build demand.
Why this matters for decision-makers: Buyers must prioritize vendors with proven flue-gas treatment integration and modular capacity options; procurement cycles that ignore emission-control total cost of ownership will face compliance-driven cost overruns within 3–5 years.
Incinerator Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
6.220 B
2024
6.470 B
2025
6.730 B
2026
7.000 B
2027
7.290 B
2028
7.580 B
2029
7.890 B
2030
Incinerator Market Size (In Billion)
Year
Market Size
2024
6.220 B
2025
6.470 B
2026
6.730 B
2027
7.000 B
2028
7.290 B
2029
7.580 B
2030
7.890 B
What is the Incinerator Market?
The incinerator market covers the design, manufacture, installation and servicing of controlled-combustion systems that convert municipal, industrial, hazardous and medical waste into ash, flue gas and recoverable heat. It spans mass-burn, fluidized-bed, rotary-kiln and modular units, plus emission-control and heat-recovery subsystems that determine regulatory compliance and energy revenue.
Scope: what this report covers and excludes
This analysis covers global incinerator equipment and turnkey systems across municipal, industrial, hazardous and biomedical waste streams, including emission-control and heat-recovery subsystems. It addresses technology, capacity, end-use and regional demand. This analysis does not cover landfill gas capture, anaerobic digestion, pyrolysis/gasification-only systems, waste collection logistics, or the downstream ash-disposal market.
How big is the market for Incinerator Market?
Published estimates diverge materially because of scope differences (equipment-only vs turnkey EPC, waste-to-energy inclusion, and base year), so buyers should read sizing figures through the definition column below.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
6.22 Billion
2024
2035
4.04%
Global incinerator equipment and systems (all waste types)
One published market study
18.5 Billion
2023
2033
2.11%
Broad incineration equipment incl. products and end-use (wider scope)
Competing published analysis
2.96 Billion
2026
2036
3.9%
Industrial waste incinerators only
Third-party industry estimate
11.84 Billion
2025
2033
2.9%
Waste incinerators (revenue, global)
Published syndicated estimate
Our analysis suggests the 6.22–9.61 Billion trajectory is the most defensible for a global, all-waste-type equipment scope, because it sits between narrow industrial-only estimates and the very broad 18.5 Billion figure that likely embeds construction and EPC services. The divergence itself is a buying signal: scope definitions vary so widely that procurement teams must normalize what is included before comparing vendor quotes or investment cases.
How is the market segmented?
Segmentation follows technology, waste stream, application, control technology, capacity and end-use, with technology and waste type being the primary axes for vendor positioning and pricing.
Our analysis suggests rotary kiln commands roughly a third of industrial-waste demand, while fluidized bed is the fastest-growing technology because it handles mixed and hazardous feedstocks with tighter combustion control. Mass burn still anchors municipal waste-to-energy economics at scale.
Which region leads in Incinerator Market?
North America leads the global incinerator market by revenue, supported by a mature waste-to-energy installed base and strict emission rules, while Asia-Pacific is the fastest-growing region, led by China's industrial-waste build-out.
Incinerator Market Regional Market Share
Loading chart...
Incinerator Market Regional Market Share
Region
Market Share (%)
North America
0.28%
Europe
0.24%
Asia-Pacific
0.36%
South America
0.06%
Middle East & Africa
0.06%
Parent
Children
North America
United States, Canada, Mexico
Europe
Germany, UK, France, Italy, Spain, Nordics, Rest of Europe
Asia-Pacific
China, Japan, India, South Korea, Southeast Asia, Australia
South America
Brazil, Argentina, Colombia, Chile, Peru
Middle East & Africa
Saudi Arabia, UAE, Turkey, Egypt, South Africa
Asia-Pacific's growth is not uniform: China (≈5.2% CAGR in industrial waste incinerators) and India (≈4.2% in waste incinerators) outpace Japan (≈2.6%), reflecting differing replacement versus new-build dynamics. Europe sits between the two, with Germany and the UK driving retrofit demand under circular-economy policy. This divergence implies vendors should localize capacity and service models rather than export a single global platform.
What is driving growth — and what is holding it back?
Energy-recovery economics and tightening environmental regulation are the primary growth engines, while high capital intensity and public opposition are the main restraints, giving the market a steady but not explosive trajectory.
Factor
Direction
Evidence strength
Mechanism
Rising waste generation (≈3.4 Bt/yr by 2050)
Driver
High
Volume of feedstock requiring treatment
Energy recovery / WtE revenue
Driver
High
Converts disposal cost into electricity/heat income
Stricter emission and landfill rules
Driver
High
Mandates treatment and retrofit of control systems
Urbanization and industrialization in APAC
Driver
High
New-build demand in dense cities
High upfront capital cost
Restraint
Medium
Limits smaller municipal and private entrants
Public opposition / NIMBY
Restraint
Medium
Delays permitting and siting
Technical complexity of integration
Restraint
Medium
Raises engineering and O&M cost
The balance favors growth: regulation is a structural, non-cyclical driver, whereas capital cost is a financing constraint that WtE revenue and modular designs partially offset. Our analysis suggests the restraint that matters most is not cost but social license—projects that win community engagement early compress permitting timelines by quarters, not weeks.
Who are the leading vendors?
The vendor landscape is led by European and Japanese engineering majors with integrated WtE and flue-gas capabilities, plus specialized industrial-incinerator manufacturers serving hazardous and medical niches.
Company
HQ
Core strength
Notable positioning
Veolia
France
Integrated waste and WtE operations
Full value-chain operator
SUEZ
France
Waste treatment and recovery
Strong municipal footprint
Covanta
USA
Municipal WtE plants
North America anchor
Babcock & Wilcox
USA
Boilers and emission control
Technology and retrofit
Hitachi Zosen
Japan
WtE and industrial incineration
APAC and global EPC
Kawasaki Heavy Industries
Japan
Fluidized bed and industrial systems
Technology depth
Keppel Seghers
Singapore
WtE EPC
APAC project delivery
Thermax
India
Industrial boilers and incinerators
Emerging-market cost position
Differentiation rests on flue-gas treatment integration and reference plants, not on basic combustion hardware. Our analysis suggests the moat is service and retrofit annuity: vendors with installed-base O&M contracts enjoy stickier revenue than pure equipment sellers.
What do buyers and operators need to know?
Selection should hinge on total cost of ownership, not headline capex. Flue-gas treatment and heat-recovery subsystems often represent 30–40% of lifecycle cost and determine whether a plant meets tightening dioxin, NOx and particulate limits. Buyers should demand guaranteed emission performance and reference-plant data.
Procurement risks cluster around scope ambiguity (equipment vs turnkey), feedstock variability and permitting. Switching costs are high once a plant is commissioned, so vendor lock-in on controls and spare parts is a real commercial lever—negotiate long-term service agreements upfront. Regulatory compliance is non-negotiable: choose vendors with local permitting experience and verifiable continuous-emission-monitoring credentials.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a steady-growth, regulation-led market rather than a boom: a ~4% CAGR is credible for global equipment scope, and we would treat the 18.5 Billion figure as an inclusive EPC/services number rather than a like-for-like comparison. The strongest counter-argument is that energy-price volatility could weaken WtE economics in liberalized markets, slowing new-build decisions; we judge this a timing risk, not a structural one.
Operators: prioritize modular, emission-ready designs and lock in flue-gas service contracts to hedge compliance risk.
Investors: focus on vendors with installed-base O&M annuities and APAC project pipelines, where growth outpaces mature markets.
Vendors: localize service capacity in China and India; export-only models will lose share to regional EPC players.
What would change our conclusion: a step-change in gasification or carbon-capture economics that undercuts mass-burn capex, or a sharp regulatory rollback in North America or Europe. Absent these, the 4% trajectory holds.
Incinerator Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Incinerator Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.04% from 2020-2034
Segmentation
By Incineration Technology
Mass Burn
Fluidized Bed
Rotary Kiln
Modular
Moving Grate
Static/Multiple Hearth
By Waste Type
Municipal Solid Waste
Industrial Waste
Hazardous Waste
Biomedical/Medical Waste
Agricultural Waste
By Application
Energy Recovery
Waste-to-Energy
Volume Reduction
Environmental Protection
By Control Technology
Emission Control Systems
Flue Gas Treatment
Heat Recovery Systems
By Operating Capacity
Small ≤50 t/day
Medium 51–200 t/day
Large >200 t/day
Modular
By End Use
Municipal
Industrial
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Nordics
Rest of Europe
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Australia
Latin America
Brazil
Argentina
Colombia
Chile
Peru
Middle East & Africa
Saudi Arabia
UAE
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Incineration Technology
5.1.1. Mass Burn
5.1.2. Fluidized Bed
5.1.3. Rotary Kiln
5.1.4. Modular
5.1.5. Moving Grate
5.1.6. Static/Multiple Hearth
5.2. Market Analysis, Insights and Forecast - by Waste Type
5.2.1. Municipal Solid Waste
5.2.2. Industrial Waste
5.2.3. Hazardous Waste
5.2.4. Biomedical/Medical Waste
5.2.5. Agricultural Waste
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Energy Recovery
5.3.2. Waste-to-Energy
5.3.3. Volume Reduction
5.3.4. Environmental Protection
5.4. Market Analysis, Insights and Forecast - by Control Technology
5.4.1. Emission Control Systems
5.4.2. Flue Gas Treatment
5.4.3. Heat Recovery Systems
5.5. Market Analysis, Insights and Forecast - by Operating Capacity
5.5.1. Small ≤50 t/day
5.5.2. Medium 51–200 t/day
5.5.3. Large >200 t/day
5.5.4. Modular
5.6. Market Analysis, Insights and Forecast - by End Use
5.6.1. Municipal
5.6.2. Industrial
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Incineration Technology
6.1.1. Mass Burn
6.1.2. Fluidized Bed
6.1.3. Rotary Kiln
6.1.4. Modular
6.1.5. Moving Grate
6.1.6. Static/Multiple Hearth
6.2. Market Analysis, Insights and Forecast - by Waste Type
6.2.1. Municipal Solid Waste
6.2.2. Industrial Waste
6.2.3. Hazardous Waste
6.2.4. Biomedical/Medical Waste
6.2.5. Agricultural Waste
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Energy Recovery
6.3.2. Waste-to-Energy
6.3.3. Volume Reduction
6.3.4. Environmental Protection
6.4. Market Analysis, Insights and Forecast - by Control Technology
6.4.1. Emission Control Systems
6.4.2. Flue Gas Treatment
6.4.3. Heat Recovery Systems
6.5. Market Analysis, Insights and Forecast - by Operating Capacity
6.5.1. Small ≤50 t/day
6.5.2. Medium 51–200 t/day
6.5.3. Large >200 t/day
6.5.4. Modular
6.6. Market Analysis, Insights and Forecast - by End Use
6.6.1. Municipal
6.6.2. Industrial
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Incineration Technology
7.1.1. Mass Burn
7.1.2. Fluidized Bed
7.1.3. Rotary Kiln
7.1.4. Modular
7.1.5. Moving Grate
7.1.6. Static/Multiple Hearth
7.2. Market Analysis, Insights and Forecast - by Waste Type
7.2.1. Municipal Solid Waste
7.2.2. Industrial Waste
7.2.3. Hazardous Waste
7.2.4. Biomedical/Medical Waste
7.2.5. Agricultural Waste
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Energy Recovery
7.3.2. Waste-to-Energy
7.3.3. Volume Reduction
7.3.4. Environmental Protection
7.4. Market Analysis, Insights and Forecast - by Control Technology
7.4.1. Emission Control Systems
7.4.2. Flue Gas Treatment
7.4.3. Heat Recovery Systems
7.5. Market Analysis, Insights and Forecast - by Operating Capacity
7.5.1. Small ≤50 t/day
7.5.2. Medium 51–200 t/day
7.5.3. Large >200 t/day
7.5.4. Modular
7.6. Market Analysis, Insights and Forecast - by End Use
7.6.1. Municipal
7.6.2. Industrial
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Incineration Technology
8.1.1. Mass Burn
8.1.2. Fluidized Bed
8.1.3. Rotary Kiln
8.1.4. Modular
8.1.5. Moving Grate
8.1.6. Static/Multiple Hearth
8.2. Market Analysis, Insights and Forecast - by Waste Type
8.2.1. Municipal Solid Waste
8.2.2. Industrial Waste
8.2.3. Hazardous Waste
8.2.4. Biomedical/Medical Waste
8.2.5. Agricultural Waste
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Energy Recovery
8.3.2. Waste-to-Energy
8.3.3. Volume Reduction
8.3.4. Environmental Protection
8.4. Market Analysis, Insights and Forecast - by Control Technology
8.4.1. Emission Control Systems
8.4.2. Flue Gas Treatment
8.4.3. Heat Recovery Systems
8.5. Market Analysis, Insights and Forecast - by Operating Capacity
8.5.1. Small ≤50 t/day
8.5.2. Medium 51–200 t/day
8.5.3. Large >200 t/day
8.5.4. Modular
8.6. Market Analysis, Insights and Forecast - by End Use
8.6.1. Municipal
8.6.2. Industrial
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Incineration Technology
9.1.1. Mass Burn
9.1.2. Fluidized Bed
9.1.3. Rotary Kiln
9.1.4. Modular
9.1.5. Moving Grate
9.1.6. Static/Multiple Hearth
9.2. Market Analysis, Insights and Forecast - by Waste Type
9.2.1. Municipal Solid Waste
9.2.2. Industrial Waste
9.2.3. Hazardous Waste
9.2.4. Biomedical/Medical Waste
9.2.5. Agricultural Waste
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Energy Recovery
9.3.2. Waste-to-Energy
9.3.3. Volume Reduction
9.3.4. Environmental Protection
9.4. Market Analysis, Insights and Forecast - by Control Technology
9.4.1. Emission Control Systems
9.4.2. Flue Gas Treatment
9.4.3. Heat Recovery Systems
9.5. Market Analysis, Insights and Forecast - by Operating Capacity
9.5.1. Small ≤50 t/day
9.5.2. Medium 51–200 t/day
9.5.3. Large >200 t/day
9.5.4. Modular
9.6. Market Analysis, Insights and Forecast - by End Use
9.6.1. Municipal
9.6.2. Industrial
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Incineration Technology
10.1.1. Mass Burn
10.1.2. Fluidized Bed
10.1.3. Rotary Kiln
10.1.4. Modular
10.1.5. Moving Grate
10.1.6. Static/Multiple Hearth
10.2. Market Analysis, Insights and Forecast - by Waste Type
10.2.1. Municipal Solid Waste
10.2.2. Industrial Waste
10.2.3. Hazardous Waste
10.2.4. Biomedical/Medical Waste
10.2.5. Agricultural Waste
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Energy Recovery
10.3.2. Waste-to-Energy
10.3.3. Volume Reduction
10.3.4. Environmental Protection
10.4. Market Analysis, Insights and Forecast - by Control Technology
10.4.1. Emission Control Systems
10.4.2. Flue Gas Treatment
10.4.3. Heat Recovery Systems
10.5. Market Analysis, Insights and Forecast - by Operating Capacity
10.5.1. Small ≤50 t/day
10.5.2. Medium 51–200 t/day
10.5.3. Large >200 t/day
10.5.4. Modular
10.6. Market Analysis, Insights and Forecast - by End Use
10.6.1. Municipal
10.6.2. Industrial
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Incinerator Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Incinerator Market Revenue (Billion), by Incineration Technology 2026 & 2034
Figure 3: North America Incinerator Market Revenue Share (%), by Incineration Technology 2026 & 2034
Figure 4: North America Incinerator Market Revenue (Billion), by Waste Type 2026 & 2034
Figure 5: North America Incinerator Market Revenue Share (%), by Waste Type 2026 & 2034
Figure 6: North America Incinerator Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Incinerator Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Incinerator Market Revenue (Billion), by Control Technology 2026 & 2034
Figure 9: North America Incinerator Market Revenue Share (%), by Control Technology 2026 & 2034
Figure 10: North America Incinerator Market Revenue (Billion), by Operating Capacity 2026 & 2034
Figure 11: North America Incinerator Market Revenue Share (%), by Operating Capacity 2026 & 2034
Figure 12: North America Incinerator Market Revenue (Billion), by End Use 2026 & 2034
Figure 13: North America Incinerator Market Revenue Share (%), by End Use 2026 & 2034
Figure 14: North America Incinerator Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Incinerator Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Incinerator Market Revenue (Billion), by Incineration Technology 2026 & 2034
The global incinerator market was estimated at USD 6.47 Billion in 2025 and is forecast to reach USD 9.61 Billion by 2035, growing at a 4.04% CAGR, based on one published estimate for all-waste-type equipment scope.
2. Which region leads the incinerator market?
North America leads by revenue, underpinned by a mature waste-to-energy base and strict emission rules. Asia-Pacific is the fastest-growing region, led by China and India, where urbanization and industrial expansion drive new-build demand.
3. What is the fastest-growing incinerator technology?
Fluidized bed incineration is the fastest-growing technology segment, valued for feedstock flexibility, uniform combustion and lower emissions. Mass burn remains the largest segment, anchoring municipal waste-to-energy economics at scale.
4. What are the main challenges in the incinerator market?
High upfront capital costs, permitting delays and public opposition are the principal challenges. These are partially offset by energy-recovery revenue and modular designs that lower entry barriers for smaller municipalities and industrial operators.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, with structured interviews across the incinerator value chain: combustion-equipment manufacturers, flue-gas treatment specialists, turnkey EPC contractors, and municipal/industrial plant operators. We conduct in-depth interviews with decision-makers including VP-level Sourcing leads, Heads of Engineering and R&D, Plant Operations Directors and Commercial Strategy Leads, capturing procurement criteria, retrofit triggers and compliance priorities.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Engineering & R&D Directors
40%
Procurement & Sourcing Leads
35%
Plant Operations & Compliance Managers
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Combustion Equipment Manufacturers
40%
Flue-Gas & Emission Control Specialists
30%
EPC & Turnkey Contractors
30%
Secondary Benchmarking & Public Trade Validation
We triangulate against official multilateral databases including UN Comtrade and WTO trade statistics, US ITC and Eurostat filings, corporate annual reports (10-K and investor presentations), patent databases, and recognized standards bodies such as ISO and national environmental agencies. These anchor equipment trade flows, vendor capacity and regulatory timelines.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down allocation from macroeconomic and waste-generation data and bottom-up modeling of manufacturer capacity, unit pricing and end-use consumption, reconciling the two into a single base-year value and forecast path.


 Incinerator Market