 L Cysteine Derivatives Market
: 2026 Growth & Vendor Guide
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 214

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 L Cysteine Derivatives Market
Srinwanti Kar
Senior Research Analyst
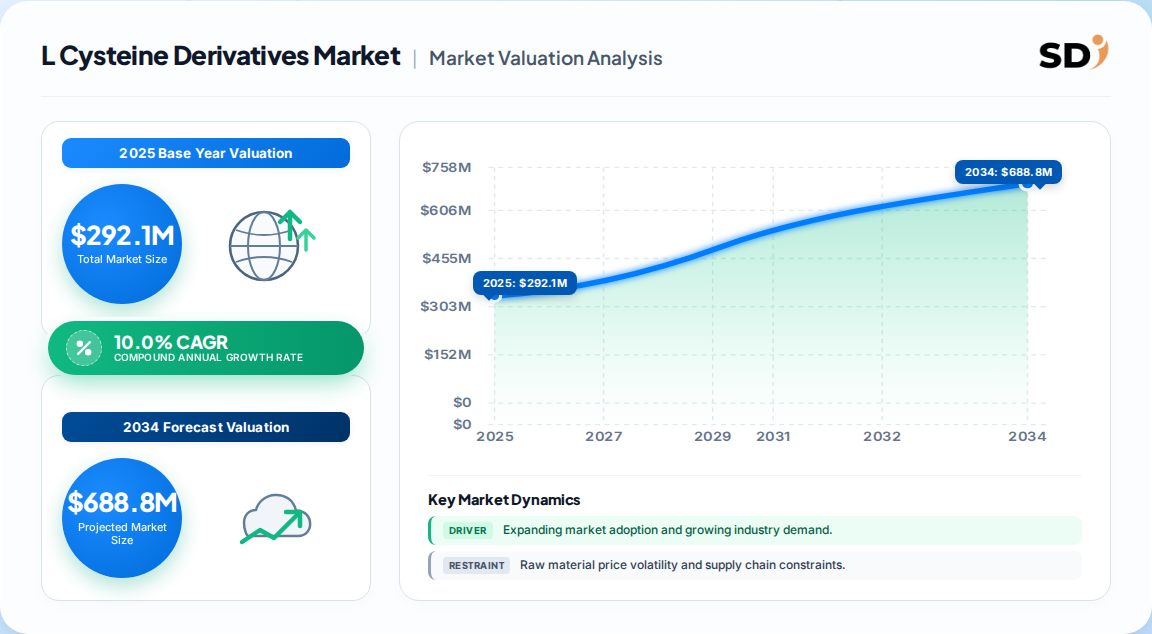
| Year | Market Size |
|---|---|
| 2025 | 292.0 M |
| 2026 | 320.0 M |
| 2027 | 352.0 M |
| 2028 | 387.0 M |
| 2029 | 425.0 M |
| 2030 | 468.0 M |
| 2031 | 515.0 M |

The L Cysteine Derivatives Market covers L-cysteine and its chemically modified forms — L-cysteine monohydrochloride, N-acetylcysteine (NAC), cysteamine and L-cystine — produced synthetically or by fermentation and sold into food, pharmaceutical, supplement and personal-care applications.
This analysis covers global demand for L-cysteine and its principal derivatives by product, source and application across five regions. It includes synthetic and fermentation-based supply, but excludes bulk amino acid categories such as glycine, methionine and glutathione finished products. This analysis does not cover downstream formulated drugs, retail supplements or cosmetic finished goods.
Published estimates diverge sharply — from roughly USD 140 Million to USD 292 Million for the same base period — because definitions, derivative scope and currency treatment differ. Our analysis treats USD 292.1 Million (2025) as the most defensible figure for the full derivative basket.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 292.1 Million | 2025 | 2033 | 10.0% | Full derivative basket incl. NAC, cysteamine, cystine | One published estimate (GVR) |
| USD 140.7 Million | 2023 | 2033 | 6.16% | Narrower product and regional set | A competing analysis |
| USD 162.6 Million | 2025 | 2034 | 6.9% | Core cysteine plus selected derivatives | A competing analysis |
| USD 319.5 Million | 2026 | 2033 | 10.0% | Full basket, forward base year | One published estimate (GVR) |
Our analysis suggests the higher valuation is credible because it captures NAC, the single largest revenue line at 29.7% share. The lower figures appear to under-count NAC and nutraceutical-grade volumes, which have grown fastest since 2023.
| Metric | Value |
|---|---|
| Base-year value (2025) | USD 292.1 Million |
| 2026 estimate | USD 319.5 Million |
| 2033 forecast | USD 622.5 Million |
| CAGR (2026–2033) | 10.0% |
The market splits three ways: by product (NAC leads at 29.7%), by source (synthetic holds 82.9% but fermentation is expanding) and by application (food & beverages leads at 35.1%, with pharmaceuticals and supplements close behind).
| Parent | Children |
|---|---|
| By Product | L-Cysteine, L-Cysteine Monohydrochloride, N-Acetylcysteine (NAC), Cysteamine, L-Cystine, Other Products |
| By Source | Natural (Fermentation), Synthetic |
| By Application | Food & Beverages, Pharmaceuticals & Healthcare, Supplements, Beauty & Personal Care, Animal Feed, Others |
Segment insight: NAC's lead is not merely a volume story — it reflects the supplement sector's shift toward glutathione-precursor positioning. Suppliers that cannot deliver USP-grade NAC at scale are structurally excluded from the fastest-growing revenue pool.
Asia Pacific leads with 51.3% of 2025 revenue, anchored by China's large-scale fermentation and synthetic capacity, low feedstock costs and expanding domestic food and pharma consumption.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.51% |
| North America | 0.22% |
| Europe | 0.18% |
| South America | 0.05% |
| Middle East & Africa | 0.04% |
| Region | Share (2025) |
|---|---|
| Asia Pacific | 51.3% |
| North America | 22.1% |
| Europe | 17.6% |
| Latin America | 5.2% |
| Middle East & Africa | 3.8% |
The concentration in Asia Pacific is a supply-chain risk as much as a cost advantage. Our analysis suggests buyers in Europe and North America face exposure to freight volatility, anti-dumping scrutiny and single-origin dependency — a case for dual-sourcing fermentation-grade material.
Demand is being pulled by food-processing and pharmaceutical expansion, while supply is being reshaped by a clean-label shift toward fermentation; the main drags are production cost and regulatory burden.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Food processing & bakery demand | Growth | High | Dough conditioner and flavor precursor volume follows baked-goods consumption |
| Pharmaceutical & supplement expansion | Growth | High | NAC as glutathione precursor; parenteral nutrition demand |
| Clean-label / vegan shift | Growth | Medium-High | Fermentation replaces animal-hair extraction; enables vegan claims |
| High production cost (fermentation) | Restraint | High | Specialized equipment, QC and energy raise unit cost |
| Regulatory complexity | Restraint | High | Food, pharma and cosmetic purity, traceability and labeling rules |
| Raw-material price volatility | Restraint | Medium | Sugar and corn steep liquor swings compress margins |
The balance favors growth: demand drivers are structural while cost pressures are cyclical and increasingly addressed through titer improvements. Our analysis suggests fermentation titer gains of roughly one-third, cited in industry reporting, are the single most important cost lever over the forecast window.
The market is moderately concentrated, with fermentation technology separating leaders from commodity synthetic suppliers. Wacker Chemie, Evonik, Ajinomoto, CJ CheilJedang, Merck KGaA, Zhejiang NHU and Shine Star anchor the competitive set.
| Company | Production route | Strategic positioning |
|---|---|---|
| Wacker Chemie AG | Fermentation (FERMOPURE) | Vegan, pharma-grade fermentation leader |
| Evonik Industries AG | Fermentation / peptides | High-solubility cell-culture derivatives (cQrex) |
| Ajinomoto Co., Inc. | Fermentation | Large-scale amino acid platform, food and pharma |
| CJ CheilJedang Corp. | Fermentation | Flavor and nutrition applications, clean-label |
| Merck KGaA | Synthetic / hybrid | Life-science and GMP-grade portfolio |
| Zhejiang NHU Co., Ltd. | Synthetic | Cost-competitive Asian supply scale |
| Shine Star (Hubei) Biological | Synthetic | High-volume export-oriented producer |
Differentiation rests on three moats: fermentation IP and titer economics, GMP/pharma certification, and long-term supply contracts with global food and pharma majors. Our analysis suggests certified fermentation capacity is the scarcest asset in the market.
Buyers should treat source route as the primary selection criterion, not price alone. Fermentation-grade material commands a premium but unlocks vegan labeling, cleaner regulatory positioning and pharmaceutical acceptance.
Procurement risk centers on single-region exposure to Asia Pacific and to grain-linked feedstock costs. Dual-sourcing across at least two regions, with contracted price bands, materially reduces exposure to freight and raw-material swings.
Switching costs are moderate in food applications but high in pharma, where supplier qualification and change-control cycles take time. Buyers entering pharma should budget for qualification lead time and prioritize vendors with existing GMP documentation.
Regulatory compliance — purity, traceability and allergen documentation — is non-negotiable across food, supplement and cosmetic channels. Operators expanding into regulated markets should verify certifications before capacity commitments.
The balance of evidence favors a constructive, supply-constrained growth thesis. The 10.0% CAGR is aggressive relative to the 6–7% estimates of competing analyses, but it is credible for the full derivative basket because NAC and clean-label fermentation demand are compounding faster than legacy L-cysteine volumes.
The strongest counter-argument is that high fermentation costs and regulatory friction could cap penetration, pulling growth toward the mid-single digits. That risk is real but manageable — it delays substitution rather than preventing it, and titer improvements are steadily eroding the cost gap.
Actionable strategy:
What would change our conclusion: sustained feedstock inflation combined with slower pharmaceutical substitution would compress the CAGR toward 6–7%, shifting the recommendation from capacity lock-in toward flexible, spot-weighted procurement.
Our approach combined primary fieldwork, trade validation and triangulated demand modeling to produce a decision-ready market view.
Fieldwork followed a 70/30 primary-to-secondary split. We conducted in-depth interviews across the value chain — raw material suppliers, specialized cysteine producers, contract formulators and global distributors — with decision-makers including VP Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads.
Benchmarks were cross-checked against UN Comtrade, WTO, US ITC and Eurostat trade data, corporate annual filings such as 10-K and SEC reports, patent databases, and recognized technical standards bodies. This validated volumes and pricing against independent official records.
We ran simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, pricing and end-use consumption) models, reconciling the two to a single base-year value and forecast path.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.0% from 2020-2034 |
| Segmentation |
|
The global market is estimated at USD 319.5 Million in 2026, up from USD 292.1 Million in 2025, and is projected to reach USD 622.5 Million by 2033 at a 10.0% CAGR.
Asia Pacific leads with 51.3% of 2025 revenue, driven by China's large-scale fermentation and synthetic capacity plus expanding domestic food and pharmaceutical demand.
N-Acetylcysteine (NAC) is the largest product segment at 29.7% of 2025 revenue, supported by supplement and glutathione-precursor demand.
Estimates range from roughly USD 140 Million to USD 292 Million because published studies differ on whether NAC, cysteamine and cystine are fully included and on base-year currency treatment.
High production costs and raw-material price volatility in fermentation, plus regulatory complexity across food and pharma, remain the main risks — mitigated by dual-region sourcing and multi-year contracts.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement | 35% |
| Heads of R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Quality Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Feedstock Suppliers | 30% |
| Specialized Cysteine Producers | 35% |
| Contract Formulators & Blenders | 20% |
| Global Distributors & Traders | 15% |
Our research followed a 70/30 primary-to-secondary split. We conducted in-depth interviews across the value chain — raw material suppliers, specialized cysteine producers, contract formulators and global distributors — with decision-makers including VP Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads.
Benchmarks were cross-checked against UN Comtrade, WTO, US ITC and Eurostat trade data, corporate annual filings such as 10-K and SEC reports, patent databases, and recognized technical standards bodies. This validated volumes and pricing against independent official records.
We ran simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, pricing and end-use consumption) models, reconciling both to a single base-year value and forecast path.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
