 Instant Grocery Market
 Size, Share & 2035 Forecast
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 214

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Instant Grocery Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 168.3 B |
| 2025 | 193.9 B |
| 2026 | 223.4 B |
| 2027 | 257.4 B |
| 2028 | 296.6 B |
| 2029 | 341.7 B |
| 2030 | 393.7 B |

The instant grocery market covers on-demand and scheduled delivery of groceries, fresh produce, beverages, and household essentials, typically fulfilled within 30–60 minutes from dark stores or micro-fulfillment centers. It is distinct from traditional e-commerce grocery through its speed promise and hyperlocal inventory model.
This report covers the global instant grocery market across service type (on-demand, scheduled, click-and-collect), product category (groceries, fresh produce, meat and seafood, beverages, household, pet, health and beauty), and delivery time bands (under 30 minutes, 30–60 minutes, over 60 minutes).
This analysis does not cover traditional brick-and-mortar grocery retail, wholesale grocery distribution, or the broader online grocery market beyond instant and same-day fulfillment. Adjacent markets such as meal-kit delivery and restaurant food delivery are also excluded except where they inform competitive dynamics.
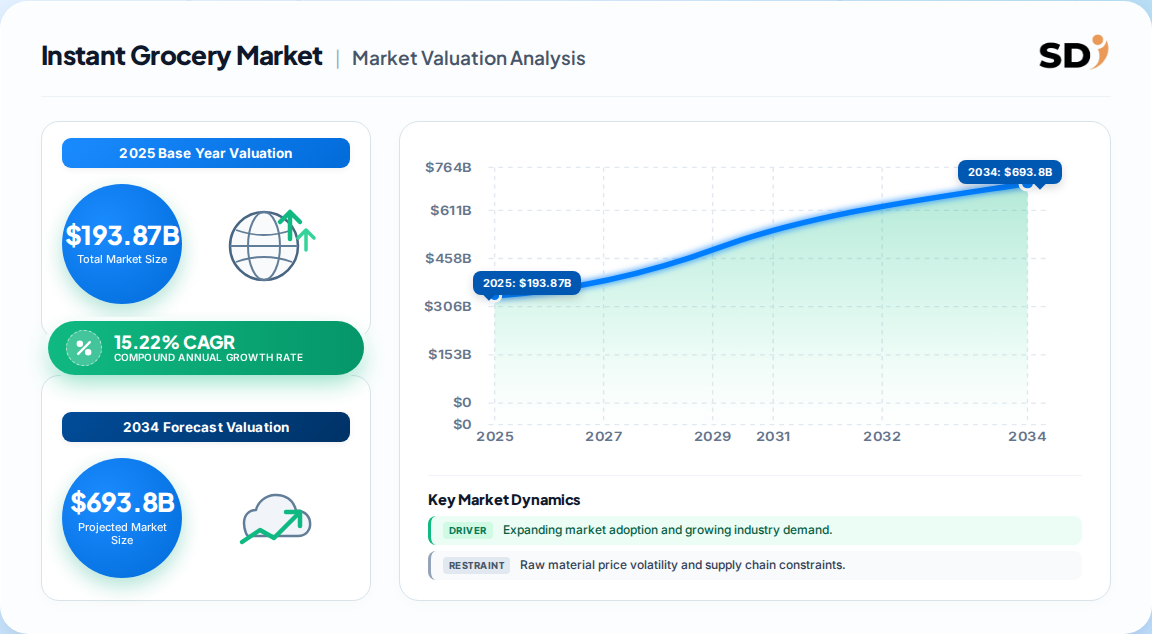
The market is estimated at 193.87 Billion in 2025, with a forecast of 799.46 Billion by 2035 at a 15.22% CAGR. However, competing estimates diverge materially depending on scope definition and base year.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 168.26 Billion | 2024 | 2035 | 15.22% | Global instant grocery, all service types | One published estimate |
| 193.87 Billion | 2025 | 2035 | 15.22% | Global instant grocery, all service types | One published estimate |
| 1.06 Trillion | 2026 | 2031 | 10.47% | Broader online grocery, incl. scheduled delivery | Competing analysis |
Our analysis suggests the mid-point estimate of ~194 Billion for 2025 is the most defensible for the instant grocery category, because it isolates on-demand and hyperlocal fulfillment rather than bundling the full online grocery basket. The 1.06 Trillion figure reflects a broader definition that includes scheduled delivery and click-and-collect, which dilutes the speed premium that defines this market.
Segmentation is driven primarily by service type and delivery time, with product category and platform type shaping margin and retention outcomes.
| Parent Segment | Children |
|---|---|
| Service Type | On-Demand Delivery, Scheduled Delivery, Click-and-Collect |
| Product Category | Groceries, Fresh Produce, Meat and Seafood, Beverages, Household Items, Pet Supplies, Health and Beauty |
| Delivery Time | Under 30 Minutes, 30–60 Minutes, Over 60 Minutes |
| Platform Type | Own Website/App, Aggregator Platforms |
On-demand delivery holds the largest revenue share, but scheduled delivery is growing fastest as operators seek higher basket sizes and lower fulfillment costs. Fresh produce is the fastest-growing product category, reflecting health-oriented consumer behavior.
North America leads with approximately 36% revenue share, followed by Europe (~28%) and Asia-Pacific (~26%). Asia-Pacific is the fastest-growing region at ~21% CAGR, driven by rapid quick-commerce adoption in India, China, and Southeast Asia.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.28% |
| Asia-Pacific | 0.26% |
| Latin America | 0.06% |
| Middle East & Africa | 0.04% |
| Region | Share |
|---|---|
| North America | 36% |
| Europe | 28% |
| Asia-Pacific | 26% |
| Latin America | 6% |
| Middle East & Africa | 4% |
Growth is driven by urbanization, time-poor consumers, dark-store expansion, and AI-driven inventory optimization. Restraints include unit-economics pressure, regulatory scrutiny of gig employment, and high customer acquisition costs.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Urban convenience demand | Driver | High | 60% of consumers prefer online grocery due to time constraints |
| Dark-store expansion | Driver | High | 30-minute delivery windows enabled within 2–3 mile radius |
| Subscription loyalty | Driver | Medium | Retention and basket-size uplift through auto-reorder |
| Sustainability sourcing | Driver | Medium | 70% of consumers willing to pay premium for eco-friendly products |
| Unit economics | Restraint | High | High CAC and low basket sizes compress margins |
| Gig-labor regulation | Restraint | Medium | Employment classification risk in EU and US markets |
Our analysis suggests the balance favors growth, but margin sustainability is the critical swing factor. Operators that cannot push basket sizes above $35–40 will struggle to justify 30-minute fulfillment costs without subscription revenue.
Competition is fragmented between pure-play instant delivery platforms and retail incumbents extending into quick commerce.
| Company | HQ | Model | Differentiation |
|---|---|---|---|
| Instacart | USA | Aggregator | Retail partnerships and ad revenue |
| GoPuff | USA | Own inventory | Broad convenience assortment |
| Gorillas | Germany | Dark store | Ultra-fast 10-minute promise |
| Getir | Turkey | Dark store | Multi-country footprint |
| Flink | Germany | Dark store | European urban density |
| Zapp | UK | Dark store | Premium assortment |
| Dija | UK | Dark store | London-centric operations |
Differentiation hinges on dark-store density, brand trust, and subscription retention. Pure-plays face structural cost disadvantages versus retail incumbents that can cross-subsidize delivery from existing store networks.
Buyers selecting instant grocery partners must evaluate fulfillment reliability, SKU freshness, cold-chain integrity, and pricing transparency. Procurement risk is concentrated in vendor financial stability, given the sector's history of consolidation and exit.
Switching costs are moderate for consumers but high for B2B buyers integrating inventory and last-mile logistics. Regulatory compliance around gig-worker classification, food safety, and packaging sustainability varies materially by jurisdiction and should be built into contract terms.
The balance of evidence favors cautious optimism with a margin-first lens. The 15.22% CAGR is credible, but it masks widening divergence between operators with dark-store density and those reliant on aggregator traffic. Our analysis suggests the next phase of growth will be won on retention economics, not delivery speed.
The strongest counter-argument is that retail incumbents will commoditize instant delivery as a free loyalty perk, collapsing standalone platform pricing power. If Walmart, Amazon, and Tesco absorb 30-minute delivery into membership programs, pure-plays will face existential pressure.
What would change our conclusion: a sustained decline in customer acquisition costs below $25, or regulatory clarity on gig-worker classification, would materially improve the risk profile for pure-play operators.
Our analysis applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews with dark-store operators, grocery retail chains, last-mile logistics providers, and technology platform vendors. Decision-makers interviewed include VP of Operations, Head of Fulfillment, Commercial Directors, and Supply Chain Leads.
We triangulate against UN Comtrade, WTO trade statistics, US ITC filings, Eurostat retail data, corporate 10-K filings, and industry association reports from food retail and logistics bodies.
We run simultaneous top-down macroeconomic allocation and bottom-up dark-store capacity, order volume, and basket-size modeling to validate market size.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 15.22% from 2020-2034 |
| Segmentation |
|
The global instant grocery market was valued at 193.87 Billion in 2025 and is projected to reach 799.46 Billion by 2035, growing at a 15.22% CAGR.
North America leads with approximately 36% revenue share, followed by Europe at 28% and Asia-Pacific at 26%. Asia-Pacific is the fastest-growing region at around 21% CAGR.
Urban convenience demand, dark-store expansion, subscription loyalty models, and AI-driven inventory optimization are the primary growth drivers, supported by changing consumer lifestyles and e-commerce expansion.
Leading players include Instacart, GoPuff, Gorillas, Getir, Flink, Zapp, and Dija, alongside retail incumbents such as Amazon Fresh, Walmart Grocery, and BigBasket.
Fresh produce is the fastest-growing product category, while scheduled delivery is the fastest-growing service type, reflecting consumer demand for flexibility and healthier options.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews with dark-store operators, grocery retail chains, last-mile logistics providers, and technology platform vendors. Decision-makers interviewed include VP of Operations, Head of Fulfillment, Commercial Directors, and Supply Chain Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Operations | 35% |
| Head of Fulfillment | 30% |
| Commercial Directors | 20% |
| Supply Chain Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Dark Store Operators | 40% |
| Retail Grocery Chains | 30% |
| Logistics Providers | 20% |
| Technology Platforms | 10% |
We triangulate against UN Comtrade, WTO trade statistics, US ITC filings, Eurostat retail data, corporate 10-K filings, and industry association reports from food retail and logistics bodies.
We run simultaneous top-down macroeconomic allocation and bottom-up dark-store capacity, order volume, and basket-size modeling to validate market size.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |