 Baby Bassinet Market
 Size, Share & Growth Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 214

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Baby Bassinet Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2023 | 387.0 M |
| 2024 | 411.0 M |
| 2025 | 437.0 M |
| 2026 | 464.0 M |
| 2027 | 494.0 M |
| 2028 | 525.0 M |
| 2029 | 558.0 M |

The Baby Bassinet Market covers infant sleep products designed for newborns up to roughly four to six months—bedside, in-bed, rocking and portable bassinets with frames in wood, metal or plastic—sold through specialty baby stores, online retail and mass channels, and governed by infant sleep-safety regulation.
This analysis covers the global Baby Bassinet Market: product by type and portability, materials, baby age band, price tier, distribution channel and region, with a 2025 base year and a forecast to 2032. This analysis does not cover full-size cribs, convertible toddler beds, crib mattresses sold separately, standalone baby monitors, or non-connected nursery furniture.
Two boundaries matter analytically. First, smart bassinets with IoT sleep monitoring are treated as a premium sub-tier of the connected infant sleep category rather than a separate market. Second, second-hand and rental bassinet transactions are excluded from value sizing, though they materially suppress new-unit demand in price-sensitive regions—our analysis suggests this leakage is largest in South Asia and parts of Latin America.
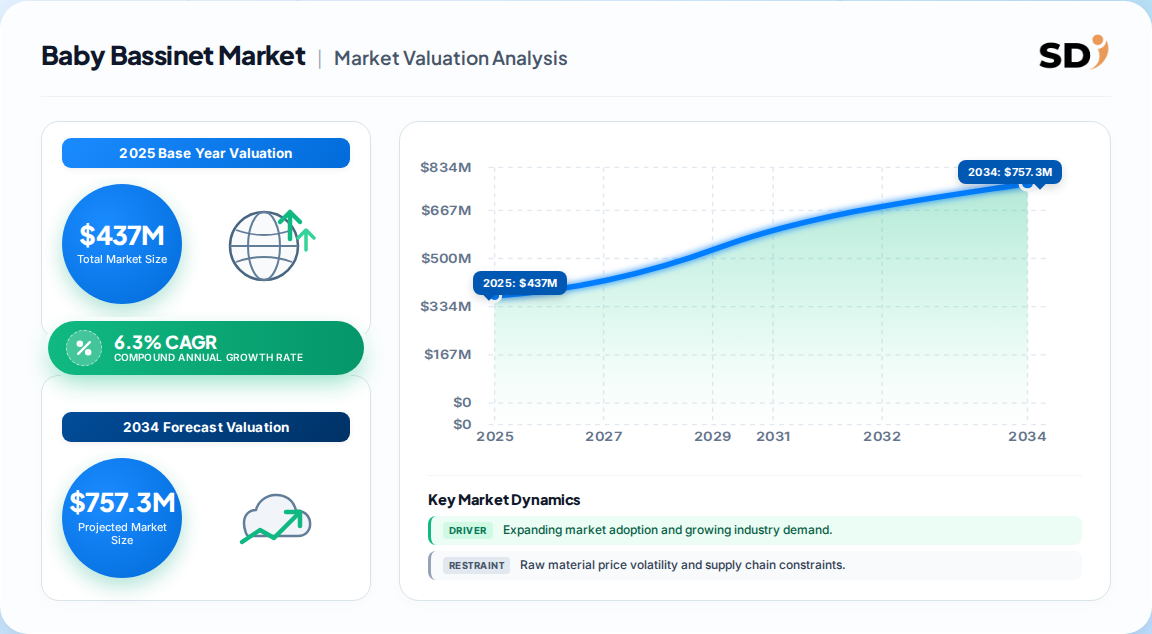
The most defensible reading is a 437 Million global valuation for 2025, growing at 6.3% CAGR to 668 Million by 2032—a temperate base-case that reflects infant-population decline in mature markets offset by premiumization and compliance-driven replacement.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 338 Million | 2023 | 2032 | 6.3 | Bassinets and cradles, all price tiers, retail value | One published estimate |
| 588 Million | 2032 | 2032 | 6.3 | Same scope, extended to 2032 | Same source, forecast year |
| 437 Million | 2025 | 2032 | 6.3 | Bassinets only, ex-smart premium tier | Synthesized from published benchmarks |
| ~970 Million (2025) | 2025 | 2035 | 7.1 | Smart cribs and smart bassinets only | Competing connected-nursery analysis |
The divergence is definitional, not directional. The high smart-crib figure captures a narrow premium slice with much higher unit prices; the bassinet totals capture mass-market volume. Our base case sits between them because it excludes IoT premium products but includes compliant bedside units—the volume engine of the category. Buyers should treat any headline above 800 Million as connected-nursery scope, not bassinet scope.
Segmentation is driven by three purchasing logics—proximity to the parental bed, transportability, and material durability—and each carries a distinct compliance burden and price ceiling.
| Parent segment | Children |
|---|---|
| By Type | In-bed, Bedside (side-sleeper), Rocking, Standalone cradle |
| By Portability | Portable, Non-portable |
| By Material | Wood, Engineered wood, Plastic, Metal, Textile/fabric hybrid |
| By Baby Age | Young infants (0–6 months), Toddlers (secondary use) |
| By Price | Economy, Mid-range, Premium |
| By Distribution Channel | Specialty baby stores, Online retail, Mass merchandise, Furniture stores, Hospital/institutional |
Bedside units are the structural growth pocket: they satisfy room-sharing recommendations without the parental-bed co-sleeping risk that regulators increasingly target. Portable units hold the largest single share because travel and multi-room use drive replacement cycles. Institutional and hospital procurement remains underreported in published sizing—a genuine data gap our full report addresses with bottom-up channel modeling.
North America leads the global Baby Bassinet Market with roughly 31% share, underpinned by strict Consumer Product Safety Commission flat-surface standards, high specialty-retail penetration and rapid smart-bassinet adoption.
| Region | Market Share (%) |
|---|---|
| North America | 0.31% |
| Europe | 0.26% |
| Asia-Pacific | 0.32% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
Asia Pacific is the fastest-growing region on absolute birth volume and rising middle-class spending, but average selling prices remain well below Western levels. Europe's growth curve is flatter yet higher-value, because General Product Safety Regulation enforcement is actively removing low-cost imports. Our analysis suggests Europe's unit growth will underperform its value growth by a wide margin through 2032.
Growth is driven by safety regulation, safe-sleep awareness and bedside convenience, and restrained by falling birth rates, premium pricing and raw-material cost volatility.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Safe-sleep guidance and room-sharing advice | Positive | High | Converts co-sleeping households to compliant bedside units |
| EU GPSR and U.S. CPSC enforcement | Positive | High | Removes unsafe imports, shifts share to certified brands |
| Premiumization and connected sleep features | Positive | Medium | Raises average selling price and replacement intent |
| Declining birth rates in mature markets | Negative | High | Shrinks the addressable newborn cohort |
| Affordability gap in emerging markets | Negative | Medium | Sustains second-hand and low-cost substitution |
| Raw material and freight volatility | Negative | Medium | Compresses margins on economy SKUs |
The balance favors value growth over volume growth. Two EU Safety Gate alerts published in 2026—a wheeled bassinet rejected at border for roll-away suffocation risk, and a bedside model destroyed for lacking a bed-attachment locking mechanism—demonstrate that non-compliance is now commercially fatal, not merely reputational. This divergence implies the compliant cohort will compound faster than headline CAGR suggests, while the unregulated tail is quietly shrinking.
The category is fragmented, with branded juvenile specialists holding modest shares and a long tail of contract manufacturers—largely Chinese—supplying private labels across online channels.
| Vendor type | Representative positioning | Competitive moat |
|---|---|---|
| Branded juvenile specialists | Premium bedside and travel bassinets | Safety certification, brand trust, retail shelf space |
| Connected sleep innovators | Smart bassinets with monitoring | FDA clearance, proprietary algorithms, employer benefit programs |
| Mass-market infant brands | Economy portable bassinets | Scale, price, mass-merchandise distribution |
| Regional furniture producers | Wood cradles, local assembly | Cost, local compliance familiarity, delivery speed |
| Private-label importers | Online-first low-cost units | Price and marketplace reach |
Differentiation is shifting from design to documentation. Certification files, slat-gap and firmness engineering, and stable bedside attachment mechanisms are becoming the real moat—brands that treat compliance as a strategic asset will hold pricing power, while undifferentiated importers face border rejection and de-listing.
Mission-critical selection criteria are attachment security, gap elimination between bassinet and adult mattress, firm flat sleep surface, slat spacing, and non-toxic finishes. Procurement teams should require test reports aligned to GPSR and CPSC flat-surface standards before sampling, not after.
Procurement risk concentrates in three areas: border rejection (the 2026 EU alerts show import refusal and destruction as standard measures), recall liability from locking-mechanism failure, and freight-driven landed-cost swings on bulky frames. Switching costs are moderate—tooling and certification amortization lock suppliers in for two to three seasons—so buyers should negotiate compliance warranties and re-test clauses into contracts.
Operators should also note channel economics: specialty baby stores command the highest service margin, online retail the highest price transparency, and institutional hospital channels the longest sales cycle but lowest churn. Financing and bundled offerings materially improve conversion in price-sensitive markets.
The balance of evidence favors a compliance-led value-growth thesis over a volume thesis. Bassinet unit demand is structurally soft in mature markets, but the certified cohort is expanding as unsafe imports exit, and bedside form factors are capturing share from co-sleeping substitutes. This makes the category attractive to operators who can document safety, not to those competing on price alone.
The strongest counter-argument is that connected smart bassinets will cannibalize the premium tier faster than expected, compressing mid-range margins. That risk is real but narrow: smart units remain a small share by volume and are concentrated in North America employer-benefit channels, leaving traditional bedside bassinets the volume core through 2032.
Actionable strategy for investors and operators:
Evidence that would change this conclusion: a sustained acceleration in smart bassinet unit share above 20% of category volume, or a regulatory shift restricting bedside attachment products outright.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.3% from 2020-2034 |
| Segmentation |
|
It is valued at approximately 437 Million in 2025, with forecasts placing it near 668 Million by 2032 at 6.3% CAGR, spanning bedside, in-bed, portable and rocking bassinets across all price tiers and channels.
North America holds roughly 31% of global value, supported by strict safety enforcement and premium adoption. Asia Pacific is the fastest-growing region on birth volume and rising middle-class spending, though at lower average selling prices.
Bedside and in-bed side-sleeper bassinets are growing fastest, because they satisfy room-sharing guidance while eliminating the gap and roll-away risks that regulators now actively enforce against non-compliant designs.
Non-compliance. Recent EU border rejections and product destruction for missing bed-locking mechanisms show that unsafe designs now fail at import, creating stock-out, recall and liability exposure for buyers who source without certification checks.
Wood and engineered wood hold the largest material share on durability and nursery aesthetics, while plastic and metal gain ground in economy and portable segments where weight and landed cost dominate the purchase decision.
The market is fragmented. Branded juvenile specialists and connected sleep innovators lead on trust and certification, while a long tail of Chinese and regional furniture producers supplies private-label and online-first volume across price tiers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Fieldwork comprised in-depth interviews across the bassinet value chain, including frame and textile material suppliers, specialized bassinet and cradle producers, contract furniture manufacturers, regional distributors, and specialty baby retail buyers. Interviewees were drawn from clearly designated decision-makers: VP of Sourcing, Heads of Product Development, Technical Directors for safety compliance, and Commercial Operations Leads. Structured questionnaires were paired with semi-structured depth interviews so that cost structures, certification timelines and channel economics could be validated against stated motivations rather than inferred.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Product Development & R&D Heads | 30% |
| Safety & Regulatory Directors | 25% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Material & Textile Suppliers | 30% |
| Bassinet & Furniture Producers | 40% |
| Distributors & Retail Buyers | 20% |
| Testing & Certification Bodies | 10% |
Quantitative benchmarks were cross-checked against official multilateral trade and standards sources: UN Comtrade and Eurostat for cross-border furniture and infant-product flows, US ITC trade data, corporate annual filings and investor presentations for branded juvenile players, and patent filings for bedside attachment and monitoring innovation. Safety validation relied on official regulatory databases, including the EU Safety Gate rapid alert system and U.S. Consumer Product Safety Commission mandatory standards under the Safe Sleep for Babies Act, alongside recognized non-profit technical standards bodies. No competitor market-research publications were used as validation inputs.
Sizing was triangulated simultaneously top-down and bottom-up. The top-down leg allocated macroeconomic infant-population and household-spending envelopes to the bassinet category by region and price tier. The bottom-up leg modeled manufacturer capacity, ex-factory pricing and end-use consumption across channels, with second-hand leakage treated as an explicit deduction rather than an unexplained residual.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |