 Anesthesia Co2 Absorbent Market
 Size & Outlook 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 252

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Anesthesia Co2 Absorbent Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 87.00 M |
| 2026 | 93.00 M |
| 2027 | 98.00 M |
| 2028 | 102.0 M |
| 2029 | 107.0 M |
| 2030 | 113.0 M |
| 2031 | 118.0 M |

The Anesthesia Co2 Absorbent Market covers chemical compounds — primarily soda lime, medisorb, dragersorb, amsorb, and litholyme — used in anesthesia breathing circuits to remove exhaled carbon dioxide and prevent rebreathing. It excludes standalone CO2 monitors, filters, and anesthetic gas delivery machines, though absorbents are consumed within those systems.
This report covers global demand for anesthesia CO2 absorbents by product, type (premium vs. traditional), form (powder vs. granular), and end user (hospitals, clinics, others), with a base year of 2025/2026 and forecast horizon to 2034. This analysis does not cover medical gas cylinders, anesthesia ventilators, CO2 monitoring devices, or industrial CO2 scrubbing markets.
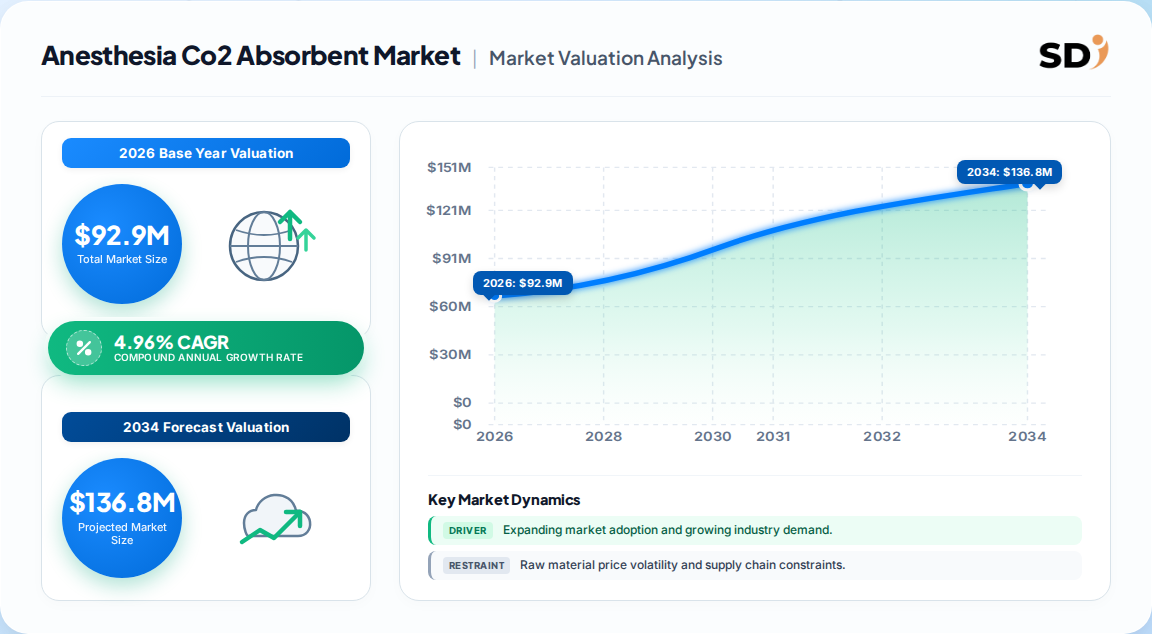
The global Anesthesia Co2 Absorbent Market is most defensibly sized at 92.9 Million in 2026, growing to 136.8 Million by 2034 at a 4.96% CAGR. This is a compact, procedure-linked consumable market where value is constrained by low unit pricing and reuse cycles.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 87.4 Million (2025) → 136.8 Million (2034) | 2025 | 2034 | 4.96% | Global anesthesia CO2 absorbents, manufacturer-level revenue | One published estimate |
| 83.0 Million (2023) → 117.3 Million (2030) | 2023 | 2030 | 4.9% | Global anesthesia CO2 absorbents, product-level segmentation | A competing analysis |
| 74.1 Million (2022) → 121.9 Million (2032) | 2022 | 2032 | 5.2% | Global anesthesia CO2 absorbents, premium-heavy mix | A competing analysis |
| 8.67 Billion (2024) → 16.77 Billion (2035) | 2024 | 2035 | 6.18% | Broad anesthesia circuits and related disposables (definitional outlier) | One published estimate |
Our analysis suggests the 4.9–5.0% range is the most defensible, because three independent estimates cluster around 83–93 Million for the base period and converge on 117–137 Million by 2030–2034. The 8.67 Billion figure clearly captures a broader anesthesia circuit and disposable category rather than absorbents alone, and should not be used for procurement or investment sizing.
Segmentation is driven by chemistry (product), performance tier (premium vs. traditional), physical form, and care setting. Premium absorbents dominate value because they reduce compound formation and support low-flow anesthesia protocols.
| Parent | Children |
|---|---|
| By Product | Soda Lime, Medisorb, Dragersorb, Amsorb, Litholyme, Others |
| By Type | Premium, Traditional |
| By Form | Powder, Granular |
| By End User | Hospitals, Clinics, Others |
Medisorb leads with roughly 29% revenue share, while Amsorb is the fastest-growing product at about 6% CAGR, reflecting its sodium-hydroxide-free safety profile. Powder form held 53.2% of 2023 revenue, but granular is gaining at 5.1% CAGR due to lower channeling and longer usable life.
North America leads with 35.4% of global revenue in 2023, supported by high surgical volumes, stringent patient-safety standards, and rapid adoption of premium absorbents. Asia-Pacific is the fastest-growing region, driven by healthcare infrastructure investment and expanding surgical access.
| Region | Market Share (%) |
|---|---|
| North America | 0.35% |
| Europe | 0.24% |
| Asia-Pacific | 0.26% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
| Region | Share |
|---|---|
| North America | 35.4% |
| Asia-Pacific | 26.3% |
| Europe | 24.1% |
| Latin America | 7.8% |
| Middle East & Africa | 6.4% |
This divergence implies that vendors with a North American premium portfolio should defend installed-base relationships, while Asia-Pacific growth is best captured through distributor partnerships and clinic-focused packaging.
Growth is anchored by rising surgical volumes, an aging population, and stricter patient-safety requirements, while restraints include low product differentiation, compound-formation risks, and pricing pressure from commodity soda lime.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Increasing surgical procedures | Driver | High | Higher anesthesia circuits in use translate directly into absorbent consumption |
| Expansion of healthcare infrastructure | Driver | High | New hospitals and ASCs in emerging markets expand the installed base |
| Sustainability and eco-friendly formulations | Driver | Medium | Sodium-hydroxide-free absorbents reduce byproducts and support low-flow anesthesia |
| Regulatory compliance and safety standards | Driver | Medium | Standards bodies push facilities toward premium, validated absorbents |
| Compound formation risk | Restraint | Medium | Concerns over compound A and toxic byproducts slow conversion in cost-sensitive facilities |
| High cost of premium absorbents | Restraint | Medium | Price-sensitive clinics and low-resource hospitals default to traditional soda lime |
Our analysis suggests the balance favors premiumization, because safety-driven demand is less elastic than cost-driven demand. However, the restraint is strongest in clinics and emerging markets, where price sensitivity can delay upgrades and compress vendor margins.
The vendor landscape is consolidated at the top but fragmented regionally. Drägerwerk, GE Healthcare, Medtronic, and Baxter International anchor the premium tier, while Armstrong Medical, Molecular Products, and regional soda lime producers compete on price and local supply.
| Company | Positioning | Moat / Differentiator |
|---|---|---|
| Drägerwerk AG & Co. KGaA | Premium absorbents (Dragersorb) | Integrated anesthesia ecosystem and clinical validation |
| Medtronic | Broad anesthesia and respiratory portfolio | Installed-base lock-in and hospital relationships |
| GE Healthcare | Anesthesia machines and absorbents | Bundled equipment-plus-consumable contracts |
| Baxter International | Premium and traditional absorbents | Hospital distribution scale and formulary access |
| Smiths Medical (ICU Medical) | Specialized consumables | Clinical training and device compatibility |
| Armstrong Medical | Regional premium absorbents | Niche product innovation and local service |
| Molecular Products Group | Soda lime and specialty chemistry | Low-cost manufacturing and raw material access |
Differentiation is increasingly tied to low-flow anesthesia compatibility and byproduct minimization, not raw absorption capacity. This implies vendors without a validated premium story will face margin compression as hospitals consolidate purchasing.
Buyers should prioritize absorbent validation data — specifically compound-formation profiles, granule hardness, dust generation, and compatibility with low-flow circuits — because these directly affect patient safety and machine maintenance costs. Procurement risk is concentrated in single-source contracts, where a supplier’s formulation change can require revalidation and staff retraining.
Switching costs are moderate but non-trivial: absorbent changes can require canister recalibration, updated SOPs, and clinician education, which favors incumbents in hospital settings. Regulatory compliance with pharmacopeial and device standards is table stakes, but buyers should also demand sustainability documentation as hospitals adopt green anesthesia targets.
The balance of evidence favors a premiumization-led growth strategy over volume expansion. The market is too small and too slow-growing for commodity players to win on scale alone; the defensible position is in validated, low-byproduct absorbents that support low-flow anesthesia and hospital sustainability mandates.
The strongest counter-argument is that price-sensitive clinics and emerging markets will continue to favor traditional soda lime, limiting premium penetration. This is credible, but it is a segment-level constraint rather than a market-level one: hospital purchasing, which holds 56% of revenue, is moving toward premium specifications.
Actionable strategy:
Our conclusion would change if regulatory bodies mandated sodium-hydroxide-free absorbents across all care settings, which would accelerate premium conversion beyond current forecasts; conversely, a sustained pricing collapse in soda lime would delay premium adoption in emerging markets.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.96% from 2020-2034 |
| Segmentation |
|
The global Anesthesia Co2 Absorbent Market is valued at approximately 92.9 Million in 2026, based on manufacturer-level revenue for absorbent products used in anesthesia breathing circuits.
The market is projected to grow at a 4.96% CAGR from 2026 to 2034, reaching approximately 136.8 Million by the end of the forecast period.
Medisorb holds the largest product share at roughly 29%, while premium-type absorbents dominate overall value with about 62% of revenue.
North America leads with a 35.4% revenue share, supported by high surgical volumes and stringent patient-safety standards; Asia-Pacific is the fastest-growing region.
Leading vendors include Drägerwerk, Medtronic, GE Healthcare, Baxter International, Smiths Medical, Armstrong Medical, and Molecular Products Group.
Rising surgical volumes, an aging population, healthcare infrastructure expansion, and patient-safety regulations are the primary growth drivers for absorbent demand.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the anesthesia CO2 absorbent value chain, including raw material suppliers (calcium hydroxide, sodium hydroxide, and indicator suppliers), specialized absorbent producers, contract formulators and blenders, and global medical device distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of both technical and commercial perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 40% |
| Absorbent Formulators & Blenders | 35% |
| Medical Device Distributors | 25% |
We triangulate primary findings against official multilateral trade and standards databases, including UN Comtrade, WTO, US ITC, and Eurostat, to validate cross-border absorbent flows and pricing. Corporate annual filings (10-K, SEC filings, and investor presentations) are analyzed for capacity, product mix, and geographic revenue splits. Patent databases and recognized non-profit technical standards and industry associations are screened to track formulation innovation and regulatory direction.
Market sizing is derived from simultaneous top-down and bottom-up modeling. The top-down approach allocates macroeconomic and healthcare segment spending to anesthesia consumables, while the bottom-up approach models manufacturer capacity, product pricing, and end-use consumption across hospitals, clinics, and ambulatory surgical centers. The two approaches are reconciled to produce a single consensus estimate.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |