Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Polyoxymethylene POM Market Outlook 2026
Polyoxymethylene POM Market Outlook 2026
Polyoxymethylene Pom Market
Polyoxymethylene POM Market Outlook 2026
Polyoxymethylene Pom Market by Form Type (Sheet, Rod, Tube, Others), by Grade (Homopolymer, Copolymer, Specialty), by Processing Technique (Injection Molding, Extrusion, Machining), by End-User Industry (Automotive, Electrical & Electronics, Industrial & Machinery, Aerospace, Medical, Others), by Asia Pacific (China, Japan, India, South Korea, Vietnam, Malaysia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Middle East & Africa (Saudi Arabia, UAE, South Africa), by South America (Brazil, Argentina, Mexico) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 207
1.92 million tons is the 2026 global Polyoxymethylene POM market volume, projected to reach 2.41 million tons by 2031.
The market is forecast to grow at a 4.72% CAGR over 2026–2031, with value growth outpacing tonnage due to premium grade mix.
Sheet form led with 64.88% share in 2025; automotive was the top end-user at 30.71%.
Asia-Pacific dominates with 66.72% of 2025 volume; Middle East & Africa is the fastest-growing region at 5.94% CAGR.
Celanese leads with over 18% share; the top five players hold 53%, indicating medium concentration.
Low-emission copolymer and recycled-content grades are structurally reshaping price and grade mix.
Why this matters for decision-makers: Buyers must lock in low-VOC and recycled-content POM grades now, or face premium pricing and compliance-driven supply scarcity by 2027.
Polyoxymethylene Pom Market Size (In Billion)
5.0B
4.0B
3.0B
2.0B
1.0B
0
3.560 B
2025
3.720 B
2026
3.920 B
2027
4.130 B
2028
4.350 B
2029
4.580 B
2030
4.820 B
2031
Polyoxymethylene Pom Market Size (In Billion)
Year
Market Size
2025
3.560 B
2026
3.720 B
2027
3.920 B
2028
4.130 B
2029
4.350 B
2030
4.580 B
2031
4.820 B
What is the Polyoxymethylene Pom Market?
The Polyoxymethylene POM market covers the global production and sale of semi-crystalline acetal resins — homopolymer, copolymer, and specialty compounds — used for precision parts requiring high stiffness, low friction, and dimensional stability. Demand is measured by converter consumption across automotive, electronics, industrial, and medical applications.
Scope: what this report covers and excludes
This report covers virgin and recycled POM resin demand by form type (sheet, rod, tube, and others), end-user industry, and geography for 2026–2031. Volume is measured in metric tons; value in USD at manufacturer-level prices. This analysis does not cover downstream finished-part manufacturing, POM compounding equipment, or adjacent engineering plastics such as polyamide and PBT.
How big is the market for Polyoxymethylene Pom Market?
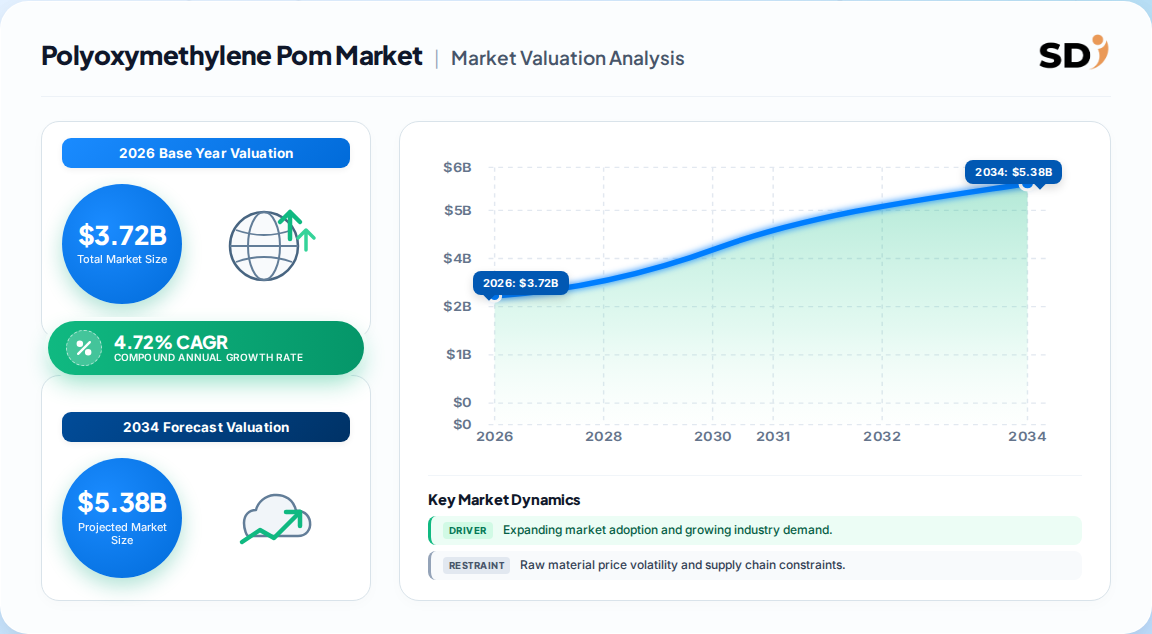
Two credible estimates frame the global market: 1.92 million tons (volume) and USD 3.72 billion (value) for 2026. The divergence is methodological, not contradictory — one tracks converter tonnage, the other tracks resin revenue.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
1.92 million tons → 2.41 million tons
2026
2031
4.72%
Volume of POM resin sold to molders
One published estimate
USD 3.72 billion → USD 5.91 billion
2026
2035
5.29%
Value of homopolymer, copolymer, specialty POM
A competing analysis
1,490 thousand tonnes demand
2025
—
—
Converter consumption, all grades
Industry expert interviews (cited via secondary)
The volume-based 4.72% CAGR is the most defensible for operational planning because it aligns with observed converter consumption of 1.49 million tonnes in 2025 and is corroborated by capacity additions in China. The higher 5.29% value CAGR reflects grade-mix enrichment — low-VOC and recycled grades carry 15–25% price premiums — rather than faster physical demand. Our analysis suggests buyers should plan volume at ~4.7% and budget value at ~5.3% to avoid understating procurement costs.
How is the market segmented?
POM segments along form type, grade, processing technique, and end-user industry. Automotive and electrical/electronics together account for over 50% of consumption, while sheet and rod forms serve machining-intensive industrial applications.
Sheet captured 64.88% of 2025 share and is growing at 5.15% CAGR, reflecting demand for machined wear parts. Aerospace, though small, is the fastest-growing end-use at 5.56% CAGR, driven by lightweight interior and avionics components.
Which region leads in Polyoxymethylene Pom Market?
Asia-Pacific leads with 66.72% of 2025 global POM volume, underpinned by integrated coal-to-POM complexes in China and cost-optimized ASEAN logistics that compress delivered resin costs versus natural-gas routes.
Polyoxymethylene Pom Market Regional Market Share
Loading chart...
Polyoxymethylene Pom Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.67%
North America
0.14%
Europe
0.12%
Middle East & Africa
0.05%
South America
0.03%
Parent Region
Key Countries / Sub-Regions
Asia-Pacific
China, Japan, India, South Korea, Vietnam, Malaysia
North America
USA, Canada, Mexico
Europe
Germany, UK, France, Italy
Middle East & Africa
Saudi Arabia, UAE, South Africa
South America
Brazil, Argentina, Mexico
Asia-Pacific's dominance is structural, not cyclical: China's coal-based feedstock advantage and India's automotive-component export surge create a durable cost moat. The Middle East & Africa's 5.94% CAGR — the fastest globally — is driven by Saudi and UAE automotive-assembly localization, which pulls POM demand into the Gulf. Europe and North America face margin pressure from anti-dumping duties and higher energy costs, making them price-takers in copolymer grades.
What is driving growth — and what is holding it back?
Automotive lightweighting (+1.2% CAGR impact) and electronics miniaturization (+0.9%) are the dominant demand drivers, while bio-based substitution (−0.8%) and raw-material volatility (−0.6%) are the principal restraints.
Factor
Direction
Evidence Strength
Mechanism
Automotive lightweighting
Driver
High
POM replaces zinc/aluminum in gears, brackets, seat mechanisms
Electronics miniaturization
Driver
High
Low moisture absorption (0.2%) holds tolerances in shrinking connectors
APAC manufacturing expansion
Driver
High
Coal-to-POM complexes and new compounding lines in India, Malaysia
Low-VOC EV interior regulations
Driver
Medium
EU Reg 2024/1257 and China GB/T 27630 favor low-emission grades
Bio-based / high-performance plastics
Restraint
Medium
PA11 and PPA displace POM in high-temp and renewable-content applications
Raw-material volatility & trade barriers
Restraint
High
Methanol price swings; US and China anti-dumping duties fragment supply
Methanol diversion to SAF
Restraint
Low
Long-term feedstock competition for methanol
The net balance favors growth: driver impacts sum to +4.2% versus restraint impacts of −1.7%, consistent with the observed 4.72% CAGR. The critical second-order effect is that regulatory drivers (low-VOC) are pushing demand toward premium copolymer grades, tightening supply of standard grades and widening the price gap between compliant and non-compliant resin. Smaller compounders without low-VOC chemistry face rising compliance costs and share loss to integrated majors.
Who are the leading vendors?
Celanese leads with over 18% share, and the top five producers — Celanese, BASF, Mitsubishi Gas Chemical, Asahi Kasei, and LG Chem — collectively hold 53%, confirming a medium-concentration market.
Company
Estimated Positioning
Key Differentiator
Celanese Corporation
Market leader (>18% share)
Hostaform low-emission XAP platform; Li Auto design wins
BASF SE
Top-5
Integrated global production; broad grade portfolio
Mitsubishi Gas Chemical
Top-5
Iupital homopolymer/copolymer strength in Asia
Asahi Kasei Corporation
Top-5
Tenac specialty grades; Japanese OEM relationships
LG Chem
Top-5
Korean capacity; electronics and automotive supply
Polyplastics (Daicel)
Specialty leader
DURACON LV low-VOC; 30% recycled-content line
Kolon Plastics
Regional challenger
Ulsan plant serving Korean and regional OEMs
Differentiation is shifting from capacity to chemistry. Celanese's XAP3 grade cuts formaldehyde emissions by up to 90%, and Daicel's 30% post-consumer recycled DURACON line targets circularity mandates. Our analysis suggests the moat is no longer resin volume but formulation IP and OEM design wins — a structural advantage for integrated players with R&D depth.
What do buyers and operators need to know?
Procurement strategy must now prioritize grade qualification over spot price. Low-VOC copolymer grades are becoming specification-mandatory for EV interiors in Europe and China, and requalifying a new resin can take 9–12 months — meaning buyers who delay face both compliance risk and switching-cost exposure. Anti-dumping duties (up to 74.9% on copolymer into China; US duties on Chinese copolymer) have fragmented supply, so dual-sourcing across duty jurisdictions is essential. Recycled-content grades offer a circularity path but require verified consistency data, which remains thin outside Japan and Europe. Operators should also monitor methanol feedstock costs, since non-integrated producers face margin compression that can translate into allocation risk during demand peaks. Finally, homopolymer and modified grades sit outside China's anti-dumping scope, creating a deliberate sourcing arbitrage for high-load gear and fastener applications.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a grade-mix-led growth thesis over a volume-led one. Physical demand grows at a steady 4.72%, but value growth of 5.29% is being driven by premium low-VOC and recycled grades that carry 15–25% price premiums. The strongest counter-argument is that bio-based polyamides and high-temperature PPA could erode POM's automotive share faster than expected — but this is concentrated in high-temperature under-hood applications, while POM's core interior, connector, and precision-gear demand remains defensible on cost and dimensional stability.
Our analysis suggests the market is entering a compliance-driven consolidation phase. Regulatory tightening (EU 2024/1257, China GB/T 27630) raises the cost of entry for small compounders, and anti-dumping duties redraw trade flows. Integrated majors with low-emission chemistry and multi-jurisdiction production will capture disproportionate share through 2031. The Middle East & Africa's 5.94% CAGR is the most underappreciated growth pocket, driven by Gulf automotive localization.
Actionable Strategy:
Buyers: Qualify low-VOC copolymer and 30% recycled-content grades now; dual-source across duty jurisdictions to hedge anti-dumping exposure.
Operators: Prioritize homopolymer and modified grades for China-bound high-load applications to exploit the anti-dumping carve-out.
Investors: Favor integrated producers with formulation IP and Gulf/ASEAN capacity exposure over commodity copolymer players.
The evidence that would change our conclusion: if recycled-content collection infrastructure scales faster than expected and matches virgin consistency, the premium-grade thesis accelerates; if China extends anti-dumping duties to homopolymer and modified grades, the sourcing arbitrage collapses and APAC cost advantages narrow.
Polyoxymethylene Pom Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Polyoxymethylene Pom Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.72% from 2020-2034
Segmentation
By Form Type
Sheet
Rod
Tube
Others
By Grade
Homopolymer
Copolymer
Specialty
By Processing Technique
Injection Molding
Extrusion
Machining
By End-User Industry
Automotive
Electrical & Electronics
Industrial & Machinery
Aerospace
Medical
Others
By Geography
Asia Pacific
China
Japan
India
South Korea
Vietnam
Malaysia
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Middle East & Africa
Saudi Arabia
UAE
South Africa
South America
Brazil
Argentina
Mexico
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Form Type
5.1.1. Sheet
5.1.2. Rod
5.1.3. Tube
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by Grade
5.2.1. Homopolymer
5.2.2. Copolymer
5.2.3. Specialty
5.3. Market Analysis, Insights and Forecast - by Processing Technique
5.3.1. Injection Molding
5.3.2. Extrusion
5.3.3. Machining
5.4. Market Analysis, Insights and Forecast - by End-User Industry
5.4.1. Automotive
5.4.2. Electrical & Electronics
5.4.3. Industrial & Machinery
5.4.4. Aerospace
5.4.5. Medical
5.4.6. Others
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. Asia Pacific
5.5.2. North America
5.5.3. Europe
5.5.4. Middle East & Africa
5.5.5. South America
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Form Type
6.1.1. Sheet
6.1.2. Rod
6.1.3. Tube
6.1.4. Others
6.2. Market Analysis, Insights and Forecast - by Grade
6.2.1. Homopolymer
6.2.2. Copolymer
6.2.3. Specialty
6.3. Market Analysis, Insights and Forecast - by Processing Technique
6.3.1. Injection Molding
6.3.2. Extrusion
6.3.3. Machining
6.4. Market Analysis, Insights and Forecast - by End-User Industry
6.4.1. Automotive
6.4.2. Electrical & Electronics
6.4.3. Industrial & Machinery
6.4.4. Aerospace
6.4.5. Medical
6.4.6. Others
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Form Type
7.1.1. Sheet
7.1.2. Rod
7.1.3. Tube
7.1.4. Others
7.2. Market Analysis, Insights and Forecast - by Grade
7.2.1. Homopolymer
7.2.2. Copolymer
7.2.3. Specialty
7.3. Market Analysis, Insights and Forecast - by Processing Technique
7.3.1. Injection Molding
7.3.2. Extrusion
7.3.3. Machining
7.4. Market Analysis, Insights and Forecast - by End-User Industry
7.4.1. Automotive
7.4.2. Electrical & Electronics
7.4.3. Industrial & Machinery
7.4.4. Aerospace
7.4.5. Medical
7.4.6. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Form Type
8.1.1. Sheet
8.1.2. Rod
8.1.3. Tube
8.1.4. Others
8.2. Market Analysis, Insights and Forecast - by Grade
8.2.1. Homopolymer
8.2.2. Copolymer
8.2.3. Specialty
8.3. Market Analysis, Insights and Forecast - by Processing Technique
8.3.1. Injection Molding
8.3.2. Extrusion
8.3.3. Machining
8.4. Market Analysis, Insights and Forecast - by End-User Industry
8.4.1. Automotive
8.4.2. Electrical & Electronics
8.4.3. Industrial & Machinery
8.4.4. Aerospace
8.4.5. Medical
8.4.6. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Form Type
9.1.1. Sheet
9.1.2. Rod
9.1.3. Tube
9.1.4. Others
9.2. Market Analysis, Insights and Forecast - by Grade
9.2.1. Homopolymer
9.2.2. Copolymer
9.2.3. Specialty
9.3. Market Analysis, Insights and Forecast - by Processing Technique
9.3.1. Injection Molding
9.3.2. Extrusion
9.3.3. Machining
9.4. Market Analysis, Insights and Forecast - by End-User Industry
9.4.1. Automotive
9.4.2. Electrical & Electronics
9.4.3. Industrial & Machinery
9.4.4. Aerospace
9.4.5. Medical
9.4.6. Others
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Form Type
10.1.1. Sheet
10.1.2. Rod
10.1.3. Tube
10.1.4. Others
10.2. Market Analysis, Insights and Forecast - by Grade
10.2.1. Homopolymer
10.2.2. Copolymer
10.2.3. Specialty
10.3. Market Analysis, Insights and Forecast - by Processing Technique
10.3.1. Injection Molding
10.3.2. Extrusion
10.3.3. Machining
10.4. Market Analysis, Insights and Forecast - by End-User Industry
10.4.1. Automotive
10.4.2. Electrical & Electronics
10.4.3. Industrial & Machinery
10.4.4. Aerospace
10.4.5. Medical
10.4.6. Others
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Polyoxymethylene Pom Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Polyoxymethylene Pom Market Volume Breakdown (Million Tons, %) by Region 2026 & 2034
Figure 3: Asia Pacific Polyoxymethylene Pom Market Revenue (Billion), by Form Type 2026 & 2034
Figure 4: Asia Pacific Polyoxymethylene Pom Market Volume (Million Tons), by Form Type 2026 & 2034
Figure 5: Asia Pacific Polyoxymethylene Pom Market Revenue Share (%), by Form Type 2026 & 2034
Figure 6: Asia Pacific Polyoxymethylene Pom Market Volume Share (%), by Form Type 2026 & 2034
Figure 7: Asia Pacific Polyoxymethylene Pom Market Revenue (Billion), by Grade 2026 & 2034
Figure 8: Asia Pacific Polyoxymethylene Pom Market Volume (Million Tons), by Grade 2026 & 2034
Figure 9: Asia Pacific Polyoxymethylene Pom Market Revenue Share (%), by Grade 2026 & 2034
Figure 10: Asia Pacific Polyoxymethylene Pom Market Volume Share (%), by Grade 2026 & 2034
Figure 11: Asia Pacific Polyoxymethylene Pom Market Revenue (Billion), by Processing Technique 2026 & 2034
Figure 12: Asia Pacific Polyoxymethylene Pom Market Volume (Million Tons), by Processing Technique 2026 & 2034
Figure 13: Asia Pacific Polyoxymethylene Pom Market Revenue Share (%), by Processing Technique 2026 & 2034
Figure 14: Asia Pacific Polyoxymethylene Pom Market Volume Share (%), by Processing Technique 2026 & 2034
Figure 15: Asia Pacific Polyoxymethylene Pom Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 16: Asia Pacific Polyoxymethylene Pom Market Volume (Million Tons), by End-User Industry 2026 & 2034
List of Tables
Table 1: Polyoxymethylene Pom Market Revenue Billion Forecast, by Form Type 2020 & 2034
Table 2: Polyoxymethylene Pom Market Volume Million Tons Forecast, by Form Type 2020 & 2034
Table 6: Polyoxymethylene Pom Market Volume Million Tons Forecast, by Processing Technique 2020 & 2034
Table 7: Polyoxymethylene Pom Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 8: Polyoxymethylene Pom Market Volume Million Tons Forecast, by End-User Industry 2020 & 2034
Table 9: Polyoxymethylene Pom Market Revenue Billion Forecast, by Region 2020 & 2034
Table 10: Polyoxymethylene Pom Market Volume Million Tons Forecast, by Region 2020 & 2034
Table 11: Asia Pacific Polyoxymethylene Pom Market Revenue Billion Forecast, by Form Type 2020 & 2034
Table 12: Asia Pacific Polyoxymethylene Pom Market Volume Million Tons Forecast, by Form Type 2020 & 2034
Table 13: Asia Pacific Polyoxymethylene Pom Market Revenue Billion Forecast, by Grade 2020 & 2034
Table 14: Asia Pacific Polyoxymethylene Pom Market Volume Million Tons Forecast, by Grade 2020 & 2034
Table 15: Asia Pacific Polyoxymethylene Pom Market Revenue Billion Forecast, by Processing Technique 2020 & 2034
Table 16: Asia Pacific Polyoxymethylene Pom Market Volume Million Tons Forecast, by Processing Technique 2020 & 2034
Frequently Asked Questions
1. How big is the Polyoxymethylene POM market?
The global POM market is estimated at 1.92 million tons in 2026, projected to reach 2.41 million tons by 2031. In value terms, a competing analysis pegs the 2026 market at USD 3.72 billion, rising to USD 5.91 billion by 2035.
2. What is the Polyoxymethylene POM market growth rate?
Volume-based forecasts indicate a 4.72% CAGR from 2026 to 2031. Value-based estimates show a higher 5.29% CAGR through 2035, reflecting premium grade mix rather than faster physical demand.
3. Which region dominates the Polyoxymethylene POM market?
Asia-Pacific leads with 66.72% of 2025 global volume, supported by China's integrated coal-to-POM complexes and ASEAN logistics advantages. The Middle East & Africa is the fastest-growing region at 5.94% CAGR.
4. Who are the leading Polyoxymethylene POM producers?
Celanese leads with over 18% market share. The top five — Celanese, BASF, Mitsubishi Gas Chemical, Asahi Kasei, and LG Chem — collectively hold 53%, indicating medium market concentration.
5. What are the main applications of Polyoxymethylene POM?
Automotive is the largest end-use at 30.71% share, followed by electrical and electronics, industrial machinery, aerospace, and medical devices. Sheet form dominates with 64.88% share, serving machined wear parts.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary split, anchored in 42 in-depth interviews conducted across the global POM value chain. Participants include raw material and methanol suppliers, specialized POM producers, contract formulators and compounders, and global distributors. Interviewees are decision-makers with direct procurement and technical authority: VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads. Interviews are structured to capture capacity utilization, grade qualification timelines, pricing mechanics, and regulatory compliance costs.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Leads
35%
R&D & Technical Directors
30%
Commercial Operations Leads
20%
Regulatory Affairs Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Methanol Suppliers
25%
Specialized POM Producers
40%
Formulators & Compounders
20%
Distributors & Traders
15%
Secondary Benchmarking & Public Trade Validation
Findings are triangulated against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and recognized technical standards bodies and industry associations. Trade-flow data is used to validate regional supply-demand balances and anti-dumping impacts; corporate filings verify capacity, grade portfolios, and revenue splits.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down and Bottom-Up models. The Top-Down model allocates macroeconomic and end-user industry output (automotive, electronics, industrial) to POM consumption intensity. The Bottom-Up model builds from manufacturer capacity, product pricing, and end-use consumption modeling by grade and form. Divergences are reconciled through expert validation.
 Polyoxymethylene Pom Market