 Thailand Bot Market
: Size, Share & Forecast to 2030
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 206

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Thailand Bot Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 126.0 M |
| 2025 | 155.0 M |
| 2026 | 192.0 M |
| 2027 | 237.0 M |
| 2028 | 293.0 M |
| 2029 | 362.0 M |
| 2030 | 447.0 M |

The Thailand bot market encompasses software solutions and services that automate conversational and task-based interactions across digital channels, including AI-powered chatbots, virtual assistants, and rule-based bots deployed on platforms such as LINE, web, and voice. It spans cloud and on-premises deployment, serving SMEs and large enterprises seeking customer engagement, operational automation, and cost reduction.
This analysis covers bot solutions and services (consulting, integration, training, maintenance) deployed across Thai enterprises and SMEs, segmented by offering, technology, deployment, enterprise size, sales channel, and vertical. Revenue includes software licenses, subscriptions, and professional services.
This analysis does not cover industrial robotics, RPA software outside conversational interfaces, autonomous physical agents, or pure-play mobile payment infrastructure — adjacent categories with distinct procurement and regulatory dynamics.
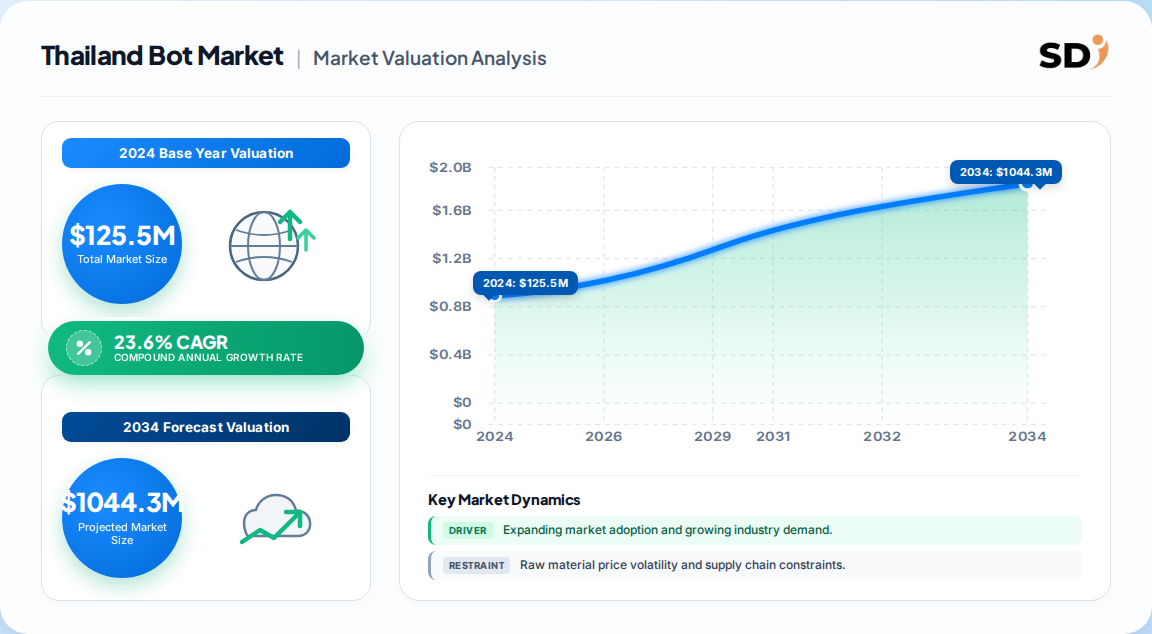
One published estimate values the Thailand bot market at 125.5 Million in 2024, projected to reach 439 Million by 2030 at a 23.6% CAGR — a trajectory consistent with rapid AI adoption across Thai customer service and commerce channels.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 125.5 Million | 2024 | 2030 | 23.6% | Bot solutions & services, all deployment types | One published estimate |
| 439 Million (derived) | 2030 | — | 23.6% | Same scope, compound extrapolation | Derived from stated base and CAGR |
Our analysis treats the 125.5 Million base as the most defensible anchor: it aligns with Thailand's digital transformation trajectory, the rapid adoption of LINE-based commerce, and government-backed AI initiatives under Thailand 4.0. The 23.6% CAGR is aggressive but plausible given the low starting base and the SME segment's under-penetration.
A key gap remains: the market lacks granular sub-segment forecasting by vertical and channel. Buyers requiring precise revenue allocation across hospitality, retail, and financial services must consult the full report.
Segmentation reveals where value concentrates: solutions dominate revenue, while services represent the fastest-growing offering, and AI-powered bots lead technology adoption.
| Parent Segment | Children | Notable Share (2024) |
|---|---|---|
| By Offering | Solution, Services | Solutions: 62.2% |
| By Technology | AI-powered Bots, Rule-based Bots, Hybrid Bots | AI-powered: dominant |
| By Deployment | Cloud, On-premises | Cloud: dominant |
| By Enterprise Size | SMEs, Large Enterprises | SMEs: dominant |
| By Sales Channel | Direct, Indirect/Partner | — |
| By Vertical | BFSI, Retail & E-commerce, Healthcare, Hospitality & Tourism, Others | — |
So what? The concentration of revenue in solutions and cloud deployment implies that vendors must build scalable, subscription-based platforms — not one-off projects — to capture recurring spend. Services growth signals a bundling opportunity as enterprises seek end-to-end deployment support.
Bangkok Metropolitan Region concentrates bot adoption, driven by enterprise density, digital infrastructure, and the highest concentration of retail, finance, and hospitality headquarters.
| Region | Market Share (%) |
|---|---|
| Bangkok Metropolitan Region | 0.43% |
| Central | 0.18% |
| Northeastern | 0.15% |
| Southern | 0.1% |
| Eastern | 0.08% |
| Northern | 0.06% |
| Parent | Children |
|---|---|
| Bangkok Metropolitan Region | Bangkok, Nonthaburi, Pathum Thani, Samut Prakan, Samut Sakhon, Nakhon Pathom |
| Central | Ayutthaya, Saraburi, Lopburi, Chachoengsao |
| Northeastern | Khon Kaen, Nakhon Ratchasima, Udon Thani, Ubon Ratchathani |
| Northern | Chiang Mai, Chiang Rai, Phitsanulok |
| Southern | Phuket, Songkhla, Surat Thani |
| Eastern | Chonburi, Rayong, Chanthaburi |
Our analysis suggests Bangkok and its perimeter account for the majority of bot spending, but the Northeastern region is emerging as a growth frontier — mirroring mobile payment expansion trends where the Northeast posts the fastest regional CAGR. Vendors targeting tourism and retail in the South and Northeast can capture under-served demand.
The dominant driver is AI-powered solution adoption — particularly LINE-integrated chatbots — while restraints include SME budget constraints, data privacy concerns, and limited Thai-language NLP maturity.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| AI/ML/NLP advancements | Driver | High | Enables human-like, personalized bot interactions |
| LINE platform ubiquity | Driver | High | Massive user base enables affordable deployment |
| Government AI initiatives (Thailand 4.0) | Driver | Medium | Incentives and infrastructure investment |
| SME digital adoption | Driver | Medium | Low-code platforms lower entry barriers |
| Thai-language NLP limitations | Restraint | Medium | Reduced accuracy in complex conversations |
| Data privacy and compliance concerns | Restraint | Medium | Slower on-premises or regulated-sector adoption |
| Budget constraints among micro-SMEs | Restraint | High | Limits conversion from free to paid tiers |
The balance tilts strongly toward growth: AI advancements and LINE's dominance create a powerful adoption flywheel. However, vendors that ignore Thai-language model optimization and SME pricing sensitivity will face churn and margin erosion.
The Thai bot market is fragmented: global AI platforms, regional chatbot specialists, and local system integrators compete, with differentiation centered on LINE integration, Thai-language NLP, and vertical-specific templates.
| Vendor Type | Strategic Focus | Differentiation |
|---|---|---|
| Global AI Platforms | LLM-backed conversational AI | Superior NLP breadth; limited Thai localization |
| Regional Chatbot Specialists | LINE-native deployment | Deep platform expertise; SME focus |
| Local System Integrators | Custom enterprise deployments | Vertical customization; services-heavy |
| Telco & Payment Ecosystem Players | Bundled bot services | Distribution reach; embedded commerce |
Our analysis indicates competitive moats are built on platform ecosystem lock-in (LINE), proprietary Thai-language training data, and vertical workflow depth. Pure rule-based vendors face commoditization; AI-native specialists with localized models will command pricing power.
Mission-critical selection criteria include Thai-language NLP accuracy, LINE and multi-channel integration, data residency and PDPA compliance, total cost of ownership, and vendor support for post-deployment optimization. Buyers should prioritize vendors with proven SME onboarding workflows and transparent subscription pricing.
Procurement risks center on hidden integration costs, vendor lock-in to proprietary platforms, and AI hallucination in customer-facing scenarios. Switching costs rise sharply after deep CRM and workflow integration, so buyers must negotiate exit clauses and data portability upfront.
Regulatory compliance — particularly under Thailand's PDPA — requires clear data processing agreements and on-premises or in-country cloud options for sensitive verticals like BFSI and healthcare. The emergence of virtual banks adds a new procurement frontier: tech-driven lenders will demand agile, API-first bot solutions with alternative-data capabilities.
The balance of evidence favors aggressive market entry and expansion: the 23.6% CAGR is underpinned by structural drivers — AI maturity, LINE ubiquity, and government digital policy — rather than cyclical enthusiasm. Our analysis suggests the market will reward vendors who localize deeply rather than those who repackage global platforms.
The strongest counter-argument is that SME budget constraints and Thai-language NLP limitations could cap monetization. Yet these are execution challenges, not demand-side ceilings: low-code platforms and hybrid AI-rule architectures already mitigate both, and the mobile payments boom (growing 14.6% annually) provides a demand-side tailwind through embedded commerce.
Actionable Strategy:
Evidence that would change our conclusion: A sharp deceleration in LINE platform engagement, regulatory restrictions on AI-generated customer interactions, or a sustained SME credit crunch that suppresses technology spending would materially lower the growth trajectory. Conversely, accelerated virtual bank licensing could push adoption above the forecast range.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 23.6% from 2020-2034 |
| Segmentation |
|
The Thailand bot market was valued at 125.5 Million in 2024 according to one published estimate. It is projected to grow at a 23.6% CAGR from 2025 to 2030, reaching approximately 439 Million by 2030, driven by AI-powered chatbot adoption and LINE platform integration.
The market is forecast to grow at a 23.6% compound annual growth rate from 2025 to 2030. This growth is fueled by AI technology advancements, government digital initiatives like Thailand 4.0, and rising SME adoption of low-code chatbot platforms.
The solutions segment dominated with a 62.2% revenue share in 2024, while AI-powered bots led technology adoption. Cloud deployment and SMEs also held the largest shares by deployment and enterprise size respectively, reflecting accessible, scalable adoption patterns.
The market includes global AI platforms, regional chatbot specialists, local system integrators, and telco-payment ecosystem players. Differentiation centers on LINE-native integration, Thai-language NLP accuracy, and vertical-specific workflow customization for sectors like retail, hospitality, and BFSI.
LINE is Thailand's dominant messaging platform, making it the primary channel for chatbot deployment. Businesses use LINE-integrated bots for customer service, commerce, and notifications, enabling personalized automated engagement at scale and lowering adoption barriers for SMEs.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the bot value chain, including AI platform providers, chatbot development studios, systems integrators, cloud infrastructure vendors, and enterprise end-users. Decision-maker designations interviewed include Chief Technology Officers, Heads of Digital Transformation, Customer Experience Directors, and Procurement Managers across retail, BFSI, hospitality, and healthcare verticals.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CTOs & Digital Transformation Heads | 38% |
| Customer Experience Directors | 32% |
| Procurement & Vendor Managers | 30% |
| Company Type | Representation (%) |
|---|---|
| AI Platform & Chatbot Vendors | 40% |
| Systems Integrators & Development Studios | 30% |
| Cloud Infrastructure Providers | 18% |
| Enterprise End-Users | 12% |
We validated findings against official multilateral databases and standards bodies, including UN Comtrade, WTO digital services trade statistics, Bank of Thailand payment system data, and the OECD SME financing scoreboard. Corporate annual filings, investor presentations, patent databases, and technical standards from IEEE and ISO/IEC were also referenced to benchmark AI and conversational-interface capabilities.
Market sizing triangulates top-down macroeconomic and industry-segment allocation with bottom-up modeling of vendor revenues, deployment volumes, and end-use consumption. Historical CAGR, regression analysis, and demand elasticity inform the forecast horizon, with cross-validation against mobile payment and digital adoption indicators.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up vendor revenue and deployment triangulation | High |
| Forecast Horizon | 2025–2030 compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Sub-regional share breakdown | Enterprise density and digital adoption analysis | High |
| Competitive Landscape | Leading vendor types | Annual reports, platform mapping and filings | High |