 Endodontic Files Market
: Size, Forecast & Strategic Outlook
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 253

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Endodontic Files Market
Srinwanti Kar
Senior Research Analyst

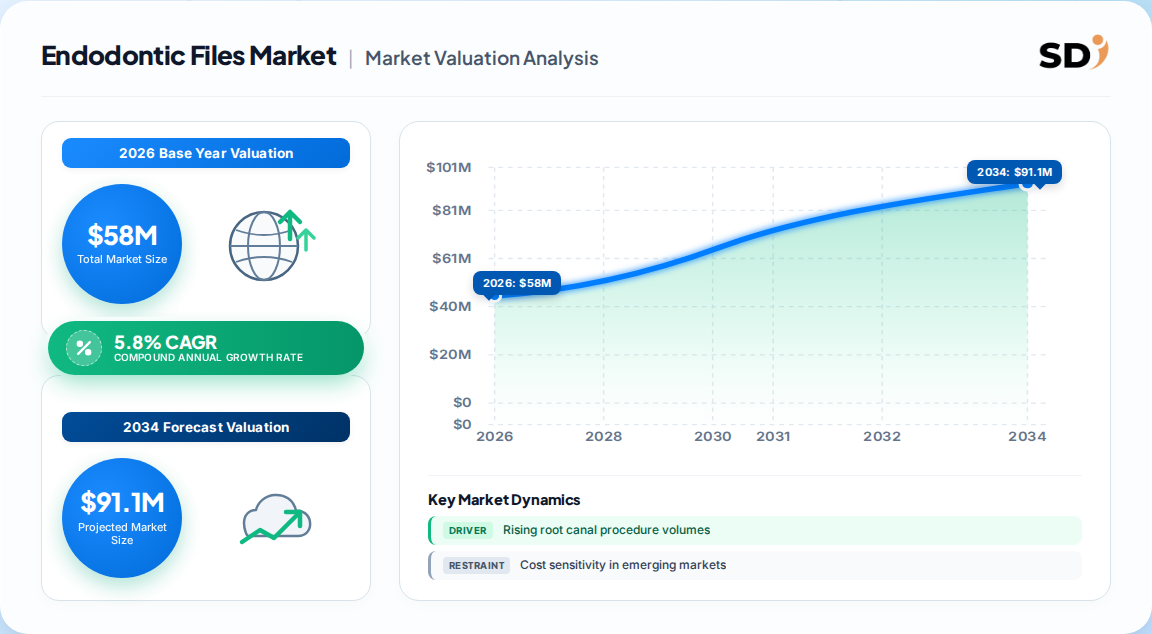
| Year | Market Size |
|---|---|
| 2024 | 52.00 M |
| 2025 | 55.00 M |
| 2026 | 58.00 M |
| 2027 | 61.00 M |
| 2028 | 65.00 M |
| 2029 | 69.00 M |
| 2030 | 73.00 M |

The Endodontic Files Market comprises precision-engineered instruments used in root canal therapy to clean, shape, and debride the root canal system. It spans manual and rotary files made from stainless steel or nickel-titanium, sold through offline and online channels to hospitals, OPDs, and dental clinics worldwide.
This analysis covers the global Endodontic Files Market across type (manual, rotary), material (stainless steel, NiTi), distribution channel (offline, online), end-use (hospitals & OPDs, dental clinics, others), and five major regions. This analysis does not cover broader endodontic consumables such as obturation materials, sealers, irrigants, apex locators, or dental handpieces, nor does it address general dental equipment or implantology markets.
Published estimates diverge materially because of differing scope definitions, base years, and whether consumable accessories are included. The table below reconciles the leading published benchmarks against a common analytical frame.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| $51.8M | 2024 | 2030 | 4.8–5.8% | Global files, all types and materials | One published estimate (Grand View) |
| $72.7M | 2030 | 2030 | 5.8% | Global files, end-use segmented | One published estimate (Grand View) |
| $21.2M | 2021 | 2032 | 6.1% | Global files, narrower product scope | Competing analysis (TMR) |
| $40.7M | 2032 | 2032 | 6.1% | Global files, conservative baseline | Competing analysis (TMR) |
| $283.5M | 2022 | 2032 | 6.2% | Broad endodontic file definition incl. accessories | Competing analysis (AMR) |
| $517.7M | 2032 | 2032 | 6.2% | Broad endodontic file definition | Competing analysis (AMR) |
Our analysis suggests the $51.8M (2024) baseline is the most defensible for a pure-play file definition, because it aligns with unit-volume proxies from root canal procedure counts and average file pricing. The $283.5M figure likely embeds broader endodontic instrumentation and consumable adjacencies; buyers should verify scope before benchmarking. The growth-rate consensus clusters tightly at 5.8–6.2%, which we treat as the reliable signal.
Segmentation is structured around four non-geographic axes: file type, material composition, distribution channel, and end-use setting. Each axis carries distinct growth dynamics that matter for portfolio and channel strategy.
| Parent Segment | Children | 2024 Share / Growth Signal |
|---|---|---|
| By Type | Manual, Rotary | Manual 54.6% share; Rotary fastest at 4.7% CAGR |
| By Material | Stainless Steel, Nickel-Titanium (NiTi) | SS 61% share; NiTi fastest at 6.6% CAGR |
| By Distribution Channel | Offline, Online | Offline 39.9% share; Online fastest at 10.5% CAGR |
| By End-use | Hospitals & OPDs, Dental Clinics, Others | Hospitals 52.1% share; Dental Clinics fastest at 7.0% CAGR |
The material and type axes are converging: NiTi adoption is predominantly a rotary phenomenon, meaning the rotary and NiTi growth stories reinforce each other. This implies portfolio rebalancing toward NiTi rotary systems captures two growth vectors simultaneously, while stainless-steel manual remains a stable but low-growth cash engine.
North America leads the global Endodontic Files Market with 40.8% revenue share in 2024, underpinned by high root canal procedure volumes, advanced dental infrastructure, and strong reimbursement coverage. The U.S. alone performs roughly 15 million root canals annually, anchoring regional demand.
| Region | Market Share (%) |
|---|---|
| North America | 0.41% |
| Europe | 0.24% |
| Asia-Pacific | 0.22% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
Geography tree (parent / children):
| Region | 2024 Share | Growth Outlook |
|---|---|---|
| North America | 40.8% | Mature, steady; U.S. dominant |
| Europe | ~24% | Moderate; UK at 6.6% CAGR |
| Asia-Pacific | ~22% | Fastest; dental tourism and infrastructure |
| Latin America | ~7% | Emerging; Brazil leads |
| Middle East & Africa | ~6% | Nascent; access-driven |
Our analysis suggests Asia-Pacific is where the incremental growth dollar concentrates, but North America remains where margin dollars concentrate. Vendors should defend North American share while seeding Asia-Pacific distribution ahead of the growth curve.
Growth is driven by rising root canal procedure volumes, aging populations, NiTi metallurgy advances, and expanding dental tourism. Restraints center on cost sensitivity in emerging markets, procedural substitution risk, and reimbursement variability across geographies.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising dental disease prevalence | Driver | High | More root canals → more files consumed |
| Aging population | Driver | High | Higher susceptibility to pulp infection |
| NiTi and heat-treatment innovation | Driver | High | Better outcomes → higher adoption |
| Dental tourism | Driver | Medium | Volume concentration in hub countries |
| Reimbursement coverage | Driver | Medium | Reduces patient out-of-pocket friction |
| Stainless-steel cost advantage | Restraint on NiTi | Medium | Price-sensitive markets defer upgrade |
| File separation risk perception | Restraint | Low–Medium | Slows rotary adoption in conservative practices |
| DSO procurement consolidation | Restraint on pricing | Medium | Bulk buying compresses vendor margins |
The balance of evidence favors sustained mid-single-digit growth, with the driver stack outpacing restraints. The second-order effect our analysis flags: DSO consolidation is a pricing restraint masquerading as a volume driver — it raises file throughput but transfers bargaining power to buyers, compressing per-unit economics for undifferentiated vendors.
The competitive landscape is moderately concentrated, with established dental majors leveraging brand trust, education programs, and broad portfolios against specialized endodontic challengers.
| Company | Positioning | Strategic Moat |
|---|---|---|
| Dentsply Sirona | Global leader; WaveOne Gold platform | Brand, R&D, education ecosystem |
| Coltene | Broad endodontic portfolio; MicroMega acquisition | Product breadth, European distribution |
| Henry Schein | Distribution scale; Casa Schmidt JV | Channel reach, supply-chain leverage |
| Envista Holdings | Portfolio player across dental consumables | Cross-selling, brand family |
| FKG Dentaire | Specialized endodontic focus | Clinical specialization, innovation |
| Ultradent Products | Endodontic and restorative breadth | Clinical training, direct sales |
| Brasseler Holdings | Precision instrumentation heritage | Manufacturing quality reputation |
| VDW GmbH | Endodontic systems specialist | Reciprocating system expertise |
Differentiation rests on metallurgy IP and clinician education, not on price alone. Education programs and dental-school partnerships create switching costs that persist through a clinician's career — a moat that our analysis suggests is underappreciated relative to manufacturing scale.
Selection criteria should prioritize cyclic fatigue resistance, metallurgical consistency (heat-treated NiTi), and compatibility with existing rotary systems. File separation is the highest-consequence failure mode, so batch-level quality assurance and traceability outweigh marginal per-unit savings.
Procurement risk concentrates in single-source dependency and DSO consolidation. Clinics buying through DSOs inherit negotiated pricing but lose brand flexibility; independent clinics retain choice but face higher unit costs. Switching costs are moderate: file systems are interoperable at the handpiece level, but clinician habit and training create soft lock-in.
Regulatory compliance is non-trivial. Files are medical devices subject to ISO 3630 dimensional and mechanical standards and regional market-access regimes (FDA 510(k) in the U.S., MDR in Europe). Buyers should verify CE/FDA status, sterilization-compatibility documentation, and shelf-life claims before qualifying a new supplier. Operators expanding into Asia-Pacific must also navigate country-specific registration timelines that can delay revenue recognition by 6–18 months.
The balance of evidence favors a growth trajectory anchored near 5.8% CAGR through 2030, with the composition of that growth shifting decisively toward NiTi rotary and reciprocating systems. The strongest counter-argument is that stainless-steel manual files remain 61% of revenue and could persist longer than forecast in cost-sensitive markets — a real possibility, but one that delays rather than reverses the mix shift. Our position: the manual segment is a cash cow to be harvested, not defended.
The most underappreciated dynamic is channel disruption. Online distribution is growing at 10.5% CAGR — roughly double the market rate — yet offline still commands 39.9% share. Vendors that treat e-commerce as a secondary channel risk ceding the fastest-growing demand pool to digital-native competitors and DSO central-procurement platforms.
Actionable strategy for investors and operators:
What would change our conclusion? A sustained reimbursement retrenchment in North America, or evidence that NiTi file separation rates remain materially higher in real-world settings than trial data suggest, would compress the rotary adoption curve and extend stainless-steel's tenure beyond our forecast horizon.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including raw material suppliers (medical-grade stainless steel and NiTi alloy), specialized endodontic file producers, contract manufacturing organizations, and global dental distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both technical and commercial perspectives informed demand estimates.
We validated findings against official multilateral trade databases (UN Comtrade, WTO), national trade statistics (US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies including ISO. This triangulation anchored our sizing assumptions to observable trade and corporate disclosure data rather than relying on any single secondary source.
Market sizing was triangulated through simultaneous top-down and bottom-up approaches. Top-down modeling allocated macroeconomic dental expenditure and procedure volumes to the file segment; bottom-up modeling built from manufacturer capacity, product pricing, and end-use consumption by setting. Divergences between the two approaches were reconciled through procedure-volume cross-checks.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.8% from 2020-2034 |
| Segmentation |
|
The global Endodontic Files Market was valued at approximately $51.8 million in 2024, with a base estimate of $58.0 million for 2026. Published estimates vary by scope definition, but the pure-play file segment clusters in the $50–60 million range for the mid-2020s.
Consensus estimates place the CAGR between 4.8% and 6.2% through 2030–2032, with a midpoint near 5.8%. Growth is underpinned by rising root canal procedure volumes, aging populations, and NiTi technology adoption.
Manual files led with 54.6% revenue share in 2024, and stainless steel held 61% by material. However, NiTi files (6.6% CAGR) and rotary systems (4.7% CAGR) are the fastest-growing segments and will reshape the mix by 2030.
North America led with 40.8% revenue share in 2024, driven by high procedure volumes and strong reimbursement. Asia-Pacific is the fastest-growing region, supported by dental tourism and expanding care infrastructure.
Leading vendors include Dentsply Sirona, Coltene, Henry Schein, Envista Holdings, FKG Dentaire, Ultradent Products, Brasseler Holdings, and VDW GmbH. Competition rests on metallurgy IP, clinician education, and distribution reach.
Key challenges include cost sensitivity in emerging markets, DSO procurement consolidation compressing vendor pricing power, reimbursement variability, and regulatory registration timelines in Asia-Pacific that can delay market entry by 6–18 months.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including raw material suppliers (medical-grade stainless steel and NiTi alloy), specialized endodontic file producers, contract manufacturing organizations, and global dental distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both technical and commercial perspectives informed demand estimates.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Alloy Suppliers | 25% |
| Specialized File Producers | 40% |
| Contract Manufacturers | 15% |
| Global Dental Distributors | 20% |
We validated findings against official multilateral trade databases (UN Comtrade, WTO), national trade statistics (US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies including ISO. This triangulation anchored our sizing assumptions to observable trade and corporate disclosure data.
Market sizing was triangulated through simultaneous top-down and bottom-up approaches. Top-down modeling allocated macroeconomic dental expenditure and procedure volumes to the file segment; bottom-up modeling built from manufacturer capacity, product pricing, and end-use consumption by setting. Divergences were reconciled through procedure-volume cross-checks.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |