 Hose Market
 Size, Growth, Trends and Forecast 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 274

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Hose Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 15.50 B |
| 2026 | 16.60 B |
| 2027 | 17.80 B |
| 2028 | 19.00 B |
| 2029 | 20.30 B |
| 2030 | 21.70 B |
| 2031 | 23.20 B |

The hose market encompasses the global manufacture and distribution of flexible tubing products—including industrial, hydraulic and specialty hoses—used to convey fluids, gases and slurries across sectors such as construction, automotive, oil & gas, chemicals and water management.
This report covers the global hose market across material types (natural rubber, nitrile rubber, PVC, silicone, polyurethane and others), wire types, end-use industries and major regions. Revenue and volume forecasts run from 2026 through 2034. This analysis does not cover rigid pipe, tubing fittings as standalone products, or consumer garden hoses.
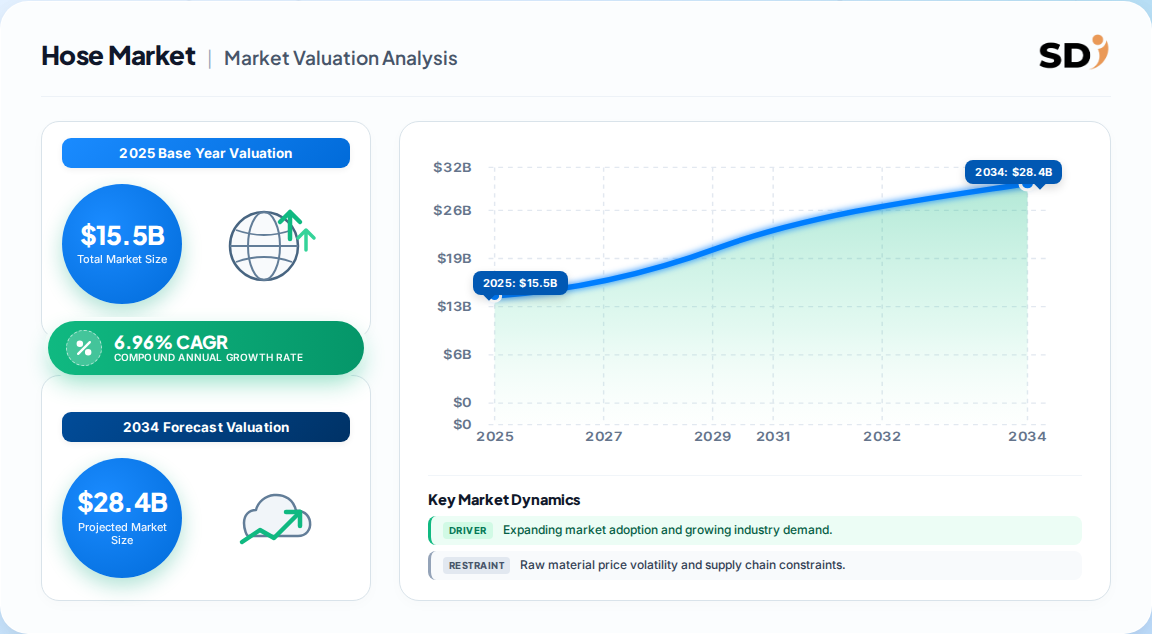
With a base valuation of 15.5 Billion in 2025, the global hose market is projected to reach 29.0 Billion by 2034, expanding at a 6.96% CAGR. The table below compares the two principal published estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 3.75 Billion → 5.15 Billion | 2023 | 2031 | 4.05% | U.S. industrial hose only | One regional trade-source synthesis |
| 15.5 Billion → 29.0 Billion | 2025 | 2034 | 6.96% | Global industrial hose, all materials | One published global estimate |
Our analysis suggests the global figure is the more defensible planning benchmark for cross-border vendors. The U.S.-only estimate reflects a narrower, mature market with lower growth; the global estimate captures fast-industrializing Asia-Pacific demand that will dictate sourcing and capacity decisions over the next decade.
The hose market segments primarily by material, wire construction and end-use industry, each shaping performance requirements and price points.
| Parent Segment | Children |
|---|---|
| By Material | Natural Rubber, Nitrile Rubber, PVC, Silicone, Polyurethane, Others |
| By Wire Type | Braided Wire, Spiral Wire, Non-Wire Reinforced |
| By End-Use Industry | Construction, Automotive, Oil & Gas, Chemicals, Food & Beverage, Water Management, Pharmaceuticals |
Polyurethane leads material demand in 2025 because it balances abrasion resistance, flexibility and durability—critical in mining, construction and material-handling duties. End-use demand remains concentrated in construction and oil & gas, though data-center cooling is emerging as a high-margin specialty niche.
Asia-Pacific leads the global hose market in 2025, supported by rapid industrialization, expanding construction activity and growing automotive production in China, India and Southeast Asia.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.39% |
| North America | 0.24% |
| Europe | 0.22% |
| South America | 0.08% |
| Middle East & Africa | 0.07% |
This hierarchy matters for procurement teams: Asia-Pacific offers scale and cost efficiency, but North American and European buyers prioritize traceability, standards compliance and lead-time reliability—factors that increasingly influence vendor selection.
Global industrialization and sector expansion are the primary growth engines, while commoditization and raw-material volatility constrain margin expansion across the value chain.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Data-center cooling demand | Driver | Strong | Specialty hoses for high-density liquid cooling systems |
| Aging water infrastructure | Driver | Strong | Government-funded upgrades to wastewater and drainage systems |
| Global industrialization | Driver | Strong | Industrial output growth of 2.3% in 2023 per UNIDO |
| Automotive expansion | Driver | Moderate | Electric mobility investments and production facilities |
| Raw-material price volatility | Restraint | Moderate | Rubber and polymer input cost swings pressure margins |
| Commoditized low-end competition | Restraint | Moderate | Price-based competition in standard hose lines |
The balance of evidence favors continued expansion, but growth is uneven: high-margin specialty hoses (data-center cooling, chemical transfer) will outpace standard industrial hose lines, implying a widening profitability gap between innovation-led and commodity producers.
Continental, Gates, Parker Hannifin and Eaton anchor the competitive landscape, each leveraging material science, application expertise and global distribution to defend share.
| Company | Focus Area | Strategic Moat |
|---|---|---|
| Continental | Data-center and industrial cooling hoses | Materials R&D, DataGuard/FlexCool launches |
| Gates | Large-diameter cooling, hydraulic systems | Data Master MegaFlex, bend-radius engineering |
| Parker Hannifin | Hydraulic and industrial hose systems | Broad portfolio, global distribution |
| Eaton | Hydraulic and fluid-conveyance solutions | Aerospace and industrial integration |
Differentiation is shifting from price to engineered performance—thermal stability, chemical resistance and custom bend radii. Vendors lacking application-specific R&D depth face margin compression as commoditized segments attract low-cost Asian producers.
Buyers should prioritize verified pressure ratings, temperature ranges and chemical compatibility over headline price, because hose failure in oil & gas, chemical or cooling applications carries disproportionate safety and downtime costs.
Procurement risk concentrates in counterfeit or non-certified product and inconsistent quality from low-cost suppliers. Switching costs are moderate—standard hoses are interchangeable—but specialty lines (data-center cooling, braided hydraulic) carry integration costs and limited qualified supplier lists. Regulatory compliance with industry standards and end-use safety requirements should be embedded in supplier qualification. Long-term contracts with performance guarantees increasingly outweigh spot purchasing.
The balance of evidence favors a growth story led by Asia-Pacific volume and specialty-hose margin, with the global estimate of 15.5 Billion in 2025 growing to 29.0 Billion by 2034 at 6.96% CAGR as the most defensible planning frame. The strongest counter-argument is that U.S.-only data suggests slower growth (4.05% CAGR), implying global figures may overstate mature-market upside—our view is that this reflects geographic mix, not a global slowdown.
Our analysis suggests the most significant second-order effect is the data-center cooling niche, where Continental and Gates have already launched dedicated products. This signals a shift toward application-specific, higher-margin hose lines that will reshape competitive positioning over the forecast horizon.
What would change our conclusion: a sustained raw-material price shock or accelerated substitution by rigid piping in water management could compress the forecast CAGR below 5% by 2030.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.96% from 2020-2034 |
| Segmentation |
|
The global hose market was valued at 15.5 Billion in 2025. It is forecast to reach 29.0 Billion by 2034, expanding at a 6.96% compound annual growth rate over the forecast period.
Asia-Pacific leads the global hose market in 2025, driven by rapid industrialization, construction expansion and automotive production in China, India and Southeast Asia. North America and Europe follow with mature, compliance-driven demand.
Key drivers include global industrialization, aging water infrastructure upgrades, automotive expansion and rising demand for advanced data-center cooling hoses. These factors support sustained volume growth and premium pricing in specialty segments.
Polyurethane led the hose market by material in 2025 due to its superior abrasion resistance, flexibility and durability. It is widely used in mining, construction and material-handling applications where performance demands are highest.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews across the hose value chain: raw material and polymer suppliers, specialized hose producers, contract formulators, and global industrial distributors. We interview decision-makers including VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads to capture procurement behavior, specification drivers, and capacity plans.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Leads | 30% |
| Heads of R&D & Technical Directors | 35% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Polymer Suppliers | 30% |
| Specialized Hose Producers | 35% |
| Contract Formulators | 15% |
| Global Industrial Distributors | 20% |
We triangulate primary findings against official multilateral databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies and industry associations. This anchors estimates in verifiable trade and standards evidence rather than single-source commentary.
We run simultaneous Top-Down (macroeconomic and end-use industry allocation) and Bottom-Up (manufacturer capacity, product pricing and end-use consumption) models. Divergences are reconciled through demand elasticity and historical CAGR regression before finalizing base-year values and forecasts.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |