Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
High Pressure Die Casting Equipment Market 2025
High Pressure Die Casting Equipment Market
High Pressure Die Casting Equipment Market 2025
High Pressure Die Casting Equipment Market by Machine Type (Hot Chamber, Cold Chamber), by Category (Semi-automatic, Automatic), by Capacity (Low Tonnage, Medium Tonnage, High Tonnage, Giga Press), by Process (Conventional, Vacuum-assisted, High-vacuum, Squeeze, Giga-casting), by Application (Automotive, Aerospace, Electronics, Industrial Machinery, Consumer Goods), by Alloy (Aluminum, Magnesium, Zinc, Others), by North America (USA, Canada, Mexico), by Europe (Germany, Italy, France, UK, Slovakia, Spain), by Asia Pacific (China, Japan, India, South Korea, Taiwan, Thailand), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 203
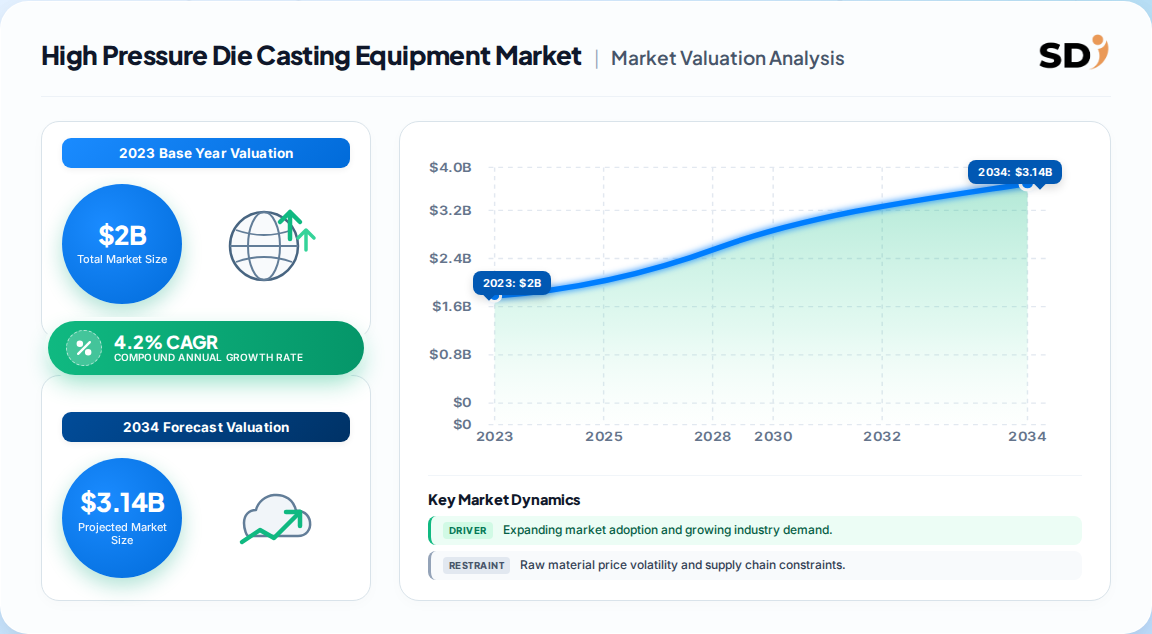
The global high pressure die casting equipment (HPDCE) market was valued at roughly USD 2.0 billion in 2023, the tightest supported base figure in the current evidence set.
Forecasts diverge sharply: one published estimate puts the equipment market at USD 2.6 billion by 2030 (4.2% CAGR), while broader casting-output figures reach USD 57–122 billion by 2031–2035 — a definitional gap, not a demand conflict.
Cold chamber machines held 71.5% of equipment revenue in 2023, reflecting aluminum's dominance of structural and powertrain casting.
Asia-Pacific leads, at roughly 47% of global casting value and the fastest growth (7.6%+ CAGR), anchored by Chinese and Japanese giga-press installations.
Automotive accounts for about 42–61% of demand depending on the definition, with EV structural parts growing fastest at ~9–10% annually.
Why this matters for decision-makers: equipment demand is shifting from tonnage to "tonnage plus vacuum plus automation" — vendors that cannot bundle porosity-free process control for 6,000–9,000-ton presses will lose share in the only high-growth demand pocket.
High Pressure Die Casting Equipment Market Size (In Billion)
3.0B
2.0B
1.0B
0
2.080 B
2024
2.170 B
2025
2.260 B
2026
2.360 B
2027
2.460 B
2028
2.560 B
2029
2.670 B
2030
High Pressure Die Casting Equipment Market Size (In Billion)
Year
Market Size
2024
2.080 B
2025
2.170 B
2026
2.260 B
2027
2.360 B
2028
2.460 B
2029
2.560 B
2030
2.670 B
What is the High Pressure Die Casting Equipment Market?
High pressure die casting equipment comprises the machines, dies, injection systems and automation cells that force molten non-ferrous metal — chiefly aluminum, magnesium and zinc — into a steel die at high pressure and speed to produce precise, thin-walled parts at volume. The market covers hot and cold chamber machines plus peripherals.
Scope: what this report covers and excludes
This analysis covers capital equipment: hot and cold chamber die casting machines, giga-press platforms, vacuum and squeeze casting cells, dosing and peripheral equipment, and integrated automation. Geographic scope is global, with regional breakdowns for equipment revenue and installed capacity. This analysis does not cover cast component production (foundry output value), die-tooling-only markets, gravity or low-pressure casting equipment, and scrap recycling services.
How big is the market for High Pressure Die Casting Equipment Market?
The most defensible base figure is about USD 2.0 billion for 2023 equipment revenue; the most defensible forecast is a mid-single-digit CAGR of roughly 4–6% through 2030, with the higher end contingent on giga-press capex staying concentrated rather than expanding.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 2.0B → 2.6B
2023
2030
4.2%
Casting machinery revenue only
One published estimate
USD 42.5B → 57.4B
2026
2031
6.19%
Casting output / component value
A competing analysis
USD 67.4B → 121.6B
2026
2035
6.1%
Casting output, all processes
Another published analysis
USD 66.0B → 121.6B
2025
2035
6.3%
Casting output, incl. giga-casting
A third published analysis
The spread is a scope artifact, not analytical error: machinery revenue and cast-part revenue differ by roughly an order of magnitude. Our inference is that "equipment" sizing at USD 2.0–2.6 billion is the only figure relevant to CapEx decisions, while the USD 57–122 billion figures should be read as the downstream demand pool that equipment vendors sell into. Buyers sizing a single 6,000–9,000-ton line should budget USD 30 million for the press and a further USD 5–10 million for large-structure dies, with 12–18-month tooling lead times.
Year
Equipment revenue (derived)
2024
2.08 Billion
2025
2.17 Billion
2026
2.26 Billion
2027
2.36 Billion
2028
2.46 Billion
2029
2.56 Billion
2030
2.67 Billion
Series derived from the stated 2023 base value and 4.2% CAGR.
How is the market segmented?
Segmentation turns on three axes: machine type (hot vs. cold chamber), process sophistication (conventional, vacuum-assisted, squeeze or giga-casting), and end-use application, with aluminum-dedicated cold chamber platforms dominating revenue.
Parent
Children
By Machine Type
Hot chamber; Cold chamber
By Category
Semi-automatic; Automatic
By Capacity
Low tonnage (below 800t); Medium (800–2,500t); High (2,500–6,000t); Giga (6,000t+)
Two structural notes. First, vacuum-assisted HPDC already accounts for roughly 56% of process value, per one analysis, which means "standard" machines are now a declining share of new orders. Second, magnesium equipment grew more than 400% at one Chinese vendor in 2025 — evidence that alloy diversification, not unit volume, is where incremental margin sits.
Which region leads in High Pressure Die Casting Equipment Market?
Asia-Pacific leads the equipment market, accounting for roughly 47% of global casting value and the fastest forecast growth, followed by North America and Europe, which lead on vacuum and giga-casting sophistication rather than unit volume.
High Pressure Die Casting Equipment Market Regional Market Share
Loading chart...
High Pressure Die Casting Equipment Market Regional Market Share
Region
Market Share (%)
North America
0.26%
Europe
0.21%
Asia-Pacific
0.47%
South America
0.03%
Middle East & Africa
0.03%
Parent
Children
North America
USA, Canada, Mexico
Europe
Germany, Italy, France, UK, Slovakia, Spain
Asia Pacific
China, Japan, India, South Korea, Taiwan, Thailand
Latin America
Brazil, Mexico, Argentina
Middle East & Africa
Saudi Arabia, UAE, South Africa, Turkey
Regional shares below are directional: Asia-Pacific 47%, North America 26%, Europe 21%, South America 3%, Middle East & Africa 3%. The commercially relevant nuance is that China drives volume while Germany, Italy and Japan drive high-value vacuum and giga-casting lines. EU carbon-border tariffs staged from 2026 are pushing offshore suppliers to localize casting capacity, which is a regional equipment demand signal, not just a trade one.
What is driving growth — and what is holding it back?
The dominant driver is EV-driven lightweighting combined with giga-press consolidation, which raises per-machine revenue faster than unit volumes; the dominant restraint is capex and tooling cost, which narrows the buyer pool to well-capitalized Tier-1s and OEMs.
Factor
Direction
Evidence strength
Mechanism
Giga-press installations
+1.6% CAGR
High
170 stampings → <5 castings; 6,000–9,000t cells
Lightweighting / EV shift
+1.3% CAGR
High
30–50% weight saving vs. stamped steel
Thermal management (battery housings)
+1.1% CAGR
Medium-high
Cooling channels cast in; <0.2mm flatness
Near-net-shape demand
+0.8% CAGR
Medium
±0.1mm accuracy; up to 70% less machining
Carbon-border tariffs
+0.5% CAGR
Medium
Localization of casting capacity
High capex and tooling
−0.7% CAGR
High
USD 30M line + USD 5–10M dies
Weld-line / porosity quality
−0.4% CAGR
Medium
Scrap and rework on large structures
ESG mandates and energy cost
−0.3% CAGR
Medium
Greener melting, emissions controls
Skilled operator shortage
−0.2% CAGR
Medium
Automation offsets but raises integration cost
Our analysis suggests the net effect is a market that grows slower in units than in value: fewer, larger, more instrumented machines. That is bullish for Buhler, UBE, Yizumi and L.K. and neutral-to-negative for vendors of standard sub-1,000-ton hot chamber units.
Who are the leading vendors?
The vendor field splits into three tiers: European and Japanese premium integrators (Buhler, UBE, Shibaura, Frech, ItalPresseGauss, Toyo), Chinese scale players (L.K. Technology, Yizumi) and specialist cold-chamber builders (Zitai, Colosio), with giga-press capability now the primary differentiator.
Vendor
HQ
Position
Notable 2025 evidence
Buhler Group
Switzerland
Premium giga-casting (Carat)
Carat 610 supplied to Honda for North American EV output
UBE Machinery
Japan
Ultra-large UH series
UH7300/UH4500 added; 4,500–9,000t range
L.K. Technology
Hong Kong/China
Volume + magnesium
Machine business +39.5% YoY; magnesium sales +400%
Yizumi Holdings
China
Two-platen LEAP series
LEAP9000 deliveries; NEXT² platform
Oskar Frech
Germany
Cold chamber, full cells
Al/Mg/Zn integrated casting cells
ItalPresseGauss
Italy
Integrated systems
Independent via management buyout, April 2025
Shibaura Machine
Japan
Precision, high-speed injection
India market expansion at GDC Tech 2025
Toyo Machinery & Metal
Japan
Stable injection, automation
High-volume light-alloy focus
Zitai Precision
Taiwan
Cost-effective cold chamber
Al and Mg, multiple clamping ranges
Colosio
Italy
Automated work islands
Specialized industrial components
The moat is no longer the press. It is process know-how bundled with die design, vacuum control, real-time monitoring and aftermarket service. A single giga-press failure halts a final-assembly line, so redundancy software and predictive maintenance have become procurement conditions — a structural advantage for incumbents with installed service networks.
What do buyers and operators need to know?
Selection now hinges on five criteria that outweigh headline clamping force. First, porosity performance under vacuum or high-vacuum: leak-free battery housings and structural parts cannot tolerate the weld-line and gas-entrapment defects that undermine crash certification. Second, flatness and dimensional repeatability below 0.2 mm on large trays, which determines gasket integrity and downstream scrap rates. Third, automation readiness — trimming, X-ray inspection and robotic deburring integrated at the cell, not bolted on later, since labor inflation makes manual finishing uneconomic in North America and Europe.
Procurement risks are concentrated in three areas. Tooling lead times of 12–18 months create schedule exposure if EV programs shift; contracts should carry volume-flex and die-ownership clauses. Capex intensity means financing structure and residual-value assumptions matter as much as machine specification. And switching costs are high: dies are program-specific, operators require re-certification, and control-software ecosystems are sticky across a plant's life.
Regulatory compliance is now a purchasing criterion. EU carbon-border tariffs staged from 2026 reward localized, low-embodied-carbon casting; Euro 7 particulate limits favor lighter vehicles; and OEM ESG audits increasingly require documented alloy recycling loops. Buyers should ask vendors for energy-per-shot data and closed-loop scrap capability, not just cycle time.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a value-over-volume thesis: equipment revenue grows at a respectable but unspectacular ~4–6% CAGR, yet the mix is rotating decisively toward 6,000-ton-plus, vacuum-assisted, highly automated cells. Anyone modeling this market on unit shipments will understate the opportunity and misprice the risk. Our analysis suggests the equipment market is best read as a narrow, capital-gated oligopoly serving a much larger USD 40–60 billion casting-output pool.
The strongest counter-argument is that giga-casting is a bubble: if EV programs slip or OEMs revert to mixed-material bodies, a handful of very large press orders could evaporate and leave overcapacity in the 4,500–9,000-ton bracket. That risk is real, and it is concentrated in a small number of buyers. But it argues for contract structure and diversification, not for abandoning the segment — magnesium, thermal-management and aerospace castings provide the hedge.
For vendors: prioritize integrated vacuum-plus-automation packages and aftermarket service contracts; standalone press sales will compress as buyers demand guaranteed porosity and uptime outcomes.
For operators: lock die ownership and volume-flex terms before committing to a giga-press line, and model energy and scrap-recycling economics explicitly — they increasingly determine total cost of ownership.
For investors: weight exposure toward vendors with installed service networks and magnesium capability; those are the positions that convert a 4–6% market CAGR into double-digit earnings growth.
What would change our conclusion: sustained sub-5,000-ton order intake across two consecutive years, or a credible shift by major OEMs back toward mixed-material assembly, would signal that the giga-casting premium is deflating.
High Pressure Die Casting Equipment Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
High Pressure Die Casting Equipment Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.2% from 2020-2034
Segmentation
By Machine Type
Hot Chamber
Cold Chamber
By Category
Semi-automatic
Automatic
By Capacity
Low Tonnage
Medium Tonnage
High Tonnage
Giga Press
By Process
Conventional
Vacuum-assisted
High-vacuum
Squeeze
Giga-casting
By Application
Automotive
Aerospace
Electronics
Industrial Machinery
Consumer Goods
By Alloy
Aluminum
Magnesium
Zinc
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
Italy
France
UK
Slovakia
Spain
Asia Pacific
China
Japan
India
South Korea
Taiwan
Thailand
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Turkey
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Machine Type
5.1.1. Hot Chamber
5.1.2. Cold Chamber
5.2. Market Analysis, Insights and Forecast - by Category
5.2.1. Semi-automatic
5.2.2. Automatic
5.3. Market Analysis, Insights and Forecast - by Capacity
5.3.1. Low Tonnage
5.3.2. Medium Tonnage
5.3.3. High Tonnage
5.3.4. Giga Press
5.4. Market Analysis, Insights and Forecast - by Process
5.4.1. Conventional
5.4.2. Vacuum-assisted
5.4.3. High-vacuum
5.4.4. Squeeze
5.4.5. Giga-casting
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Automotive
5.5.2. Aerospace
5.5.3. Electronics
5.5.4. Industrial Machinery
5.5.5. Consumer Goods
5.6. Market Analysis, Insights and Forecast - by Alloy
5.6.1. Aluminum
5.6.2. Magnesium
5.6.3. Zinc
5.6.4. Others
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Machine Type
6.1.1. Hot Chamber
6.1.2. Cold Chamber
6.2. Market Analysis, Insights and Forecast - by Category
6.2.1. Semi-automatic
6.2.2. Automatic
6.3. Market Analysis, Insights and Forecast - by Capacity
6.3.1. Low Tonnage
6.3.2. Medium Tonnage
6.3.3. High Tonnage
6.3.4. Giga Press
6.4. Market Analysis, Insights and Forecast - by Process
6.4.1. Conventional
6.4.2. Vacuum-assisted
6.4.3. High-vacuum
6.4.4. Squeeze
6.4.5. Giga-casting
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Automotive
6.5.2. Aerospace
6.5.3. Electronics
6.5.4. Industrial Machinery
6.5.5. Consumer Goods
6.6. Market Analysis, Insights and Forecast - by Alloy
6.6.1. Aluminum
6.6.2. Magnesium
6.6.3. Zinc
6.6.4. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Machine Type
7.1.1. Hot Chamber
7.1.2. Cold Chamber
7.2. Market Analysis, Insights and Forecast - by Category
7.2.1. Semi-automatic
7.2.2. Automatic
7.3. Market Analysis, Insights and Forecast - by Capacity
7.3.1. Low Tonnage
7.3.2. Medium Tonnage
7.3.3. High Tonnage
7.3.4. Giga Press
7.4. Market Analysis, Insights and Forecast - by Process
7.4.1. Conventional
7.4.2. Vacuum-assisted
7.4.3. High-vacuum
7.4.4. Squeeze
7.4.5. Giga-casting
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Automotive
7.5.2. Aerospace
7.5.3. Electronics
7.5.4. Industrial Machinery
7.5.5. Consumer Goods
7.6. Market Analysis, Insights and Forecast - by Alloy
7.6.1. Aluminum
7.6.2. Magnesium
7.6.3. Zinc
7.6.4. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Machine Type
8.1.1. Hot Chamber
8.1.2. Cold Chamber
8.2. Market Analysis, Insights and Forecast - by Category
8.2.1. Semi-automatic
8.2.2. Automatic
8.3. Market Analysis, Insights and Forecast - by Capacity
8.3.1. Low Tonnage
8.3.2. Medium Tonnage
8.3.3. High Tonnage
8.3.4. Giga Press
8.4. Market Analysis, Insights and Forecast - by Process
8.4.1. Conventional
8.4.2. Vacuum-assisted
8.4.3. High-vacuum
8.4.4. Squeeze
8.4.5. Giga-casting
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Automotive
8.5.2. Aerospace
8.5.3. Electronics
8.5.4. Industrial Machinery
8.5.5. Consumer Goods
8.6. Market Analysis, Insights and Forecast - by Alloy
8.6.1. Aluminum
8.6.2. Magnesium
8.6.3. Zinc
8.6.4. Others
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Machine Type
9.1.1. Hot Chamber
9.1.2. Cold Chamber
9.2. Market Analysis, Insights and Forecast - by Category
9.2.1. Semi-automatic
9.2.2. Automatic
9.3. Market Analysis, Insights and Forecast - by Capacity
9.3.1. Low Tonnage
9.3.2. Medium Tonnage
9.3.3. High Tonnage
9.3.4. Giga Press
9.4. Market Analysis, Insights and Forecast - by Process
9.4.1. Conventional
9.4.2. Vacuum-assisted
9.4.3. High-vacuum
9.4.4. Squeeze
9.4.5. Giga-casting
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Automotive
9.5.2. Aerospace
9.5.3. Electronics
9.5.4. Industrial Machinery
9.5.5. Consumer Goods
9.6. Market Analysis, Insights and Forecast - by Alloy
9.6.1. Aluminum
9.6.2. Magnesium
9.6.3. Zinc
9.6.4. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Machine Type
10.1.1. Hot Chamber
10.1.2. Cold Chamber
10.2. Market Analysis, Insights and Forecast - by Category
10.2.1. Semi-automatic
10.2.2. Automatic
10.3. Market Analysis, Insights and Forecast - by Capacity
10.3.1. Low Tonnage
10.3.2. Medium Tonnage
10.3.3. High Tonnage
10.3.4. Giga Press
10.4. Market Analysis, Insights and Forecast - by Process
10.4.1. Conventional
10.4.2. Vacuum-assisted
10.4.3. High-vacuum
10.4.4. Squeeze
10.4.5. Giga-casting
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Automotive
10.5.2. Aerospace
10.5.3. Electronics
10.5.4. Industrial Machinery
10.5.5. Consumer Goods
10.6. Market Analysis, Insights and Forecast - by Alloy
10.6.1. Aluminum
10.6.2. Magnesium
10.6.3. Zinc
10.6.4. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Buhler Group
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. UBE Machinery
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. L.K. Technology Holdings
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Yizumi Holdings
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Oskar Frech
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. ItalPresseGauss
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Shibaura Machine
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Toyo Machinery & Metal
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Zitai Precision Machinery
11.1.9.1. Company Overview
12. Research Methodology
List of Figures
Figure 1: High Pressure Die Casting Equipment Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America High Pressure Die Casting Equipment Market Revenue (Billion), by Machine Type 2026 & 2034
Figure 3: North America High Pressure Die Casting Equipment Market Revenue Share (%), by Machine Type 2026 & 2034
Figure 4: North America High Pressure Die Casting Equipment Market Revenue (Billion), by Category 2026 & 2034
Figure 5: North America High Pressure Die Casting Equipment Market Revenue Share (%), by Category 2026 & 2034
Figure 6: North America High Pressure Die Casting Equipment Market Revenue (Billion), by Capacity 2026 & 2034
Figure 7: North America High Pressure Die Casting Equipment Market Revenue Share (%), by Capacity 2026 & 2034
Figure 8: North America High Pressure Die Casting Equipment Market Revenue (Billion), by Process 2026 & 2034
Figure 9: North America High Pressure Die Casting Equipment Market Revenue Share (%), by Process 2026 & 2034
Figure 10: North America High Pressure Die Casting Equipment Market Revenue (Billion), by Application 2026 & 2034
Figure 11: North America High Pressure Die Casting Equipment Market Revenue Share (%), by Application 2026 & 2034
Figure 12: North America High Pressure Die Casting Equipment Market Revenue (Billion), by Alloy 2026 & 2034
Figure 13: North America High Pressure Die Casting Equipment Market Revenue Share (%), by Alloy 2026 & 2034
Figure 14: North America High Pressure Die Casting Equipment Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America High Pressure Die Casting Equipment Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Machine Type 2020 & 2034
Table 2: High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Category 2020 & 2034
Table 3: High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Capacity 2020 & 2034
Table 4: High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Process 2020 & 2034
Table 5: High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Application 2020 & 2034
Table 6: High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Alloy 2020 & 2034
Table 7: High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Machine Type 2020 & 2034
Table 9: North America High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Category 2020 & 2034
Table 10: North America High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Capacity 2020 & 2034
Table 11: North America High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Process 2020 & 2034
Table 12: North America High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Application 2020 & 2034
Table 13: North America High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Alloy 2020 & 2034
Table 14: North America High Pressure Die Casting Equipment Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA High Pressure Die Casting Equipment Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the high pressure die casting equipment market?
Equipment revenue was about USD 2.0 billion in 2023 and is forecast near USD 2.6 billion by 2030. Broader casting-output figures of USD 42–122 billion measure cast parts, not machines, and should not be used for equipment sizing.
2. What is the fastest-growing segment in high pressure die casting equipment?
EV structural and battery-housing casting is the fastest-growing application, expanding at roughly 9–10% annually. Magnesium equipment and vacuum-assisted machines are the fastest-growing product categories, driven by lightweighting and porosity requirements.
3. Which region dominates high pressure die casting equipment demand?
Asia-Pacific leads with roughly 47% of global casting value, led by China, Japan and India. North America and Europe follow, and lead instead on high-tonnage vacuum and giga-casting sophistication.
4. Why are giga-presses changing this market?
Giga-presses of 6,000–9,000 tons consolidate more than 170 stamped parts into fewer than five castings, cutting welding stations and assembly time. This raises per-machine revenue and shifts competition toward process control and uptime guarantees.
5. What are the main risks for equipment buyers?
High capex of around USD 30 million per line, die lead times of 12–18 months, porosity and weld-line quality issues, and tightening EU carbon-border and emissions rules. Contract terms on volume flex and die ownership are critical.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 split between primary and secondary evidence. In-depth interviews were conducted across the die casting value chain, including aluminum and magnesium alloy suppliers, specialized machine builders, contract foundries and Tier-1 automotive casting suppliers, and global capital-equipment distributors. Within these organizations we engaged decision-makers holding titles including VP of Sourcing, Head of Manufacturing Engineering, Technical Director, and Commercial Operations Lead. Interviews probed installed-base economics, replacement cycles, tonnage requirements, porosity tolerances, automation integration costs and procurement timelines for 6,000-ton-plus platforms.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Manufacturing & Technical Directors
38%
Procurement & Sourcing Leads
32%
Quality & Compliance Managers
18%
Plant Operations Heads
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Machine Builders & OEMs
40%
Tier-1 Casting Suppliers
30%
Alloy & Material Suppliers
18%
Distributors & Integrators
12%
Secondary Benchmarking & Public Trade Validation
Findings were benchmarked against UN Comtrade and Eurostat trade flows for die casting machines and non-ferrous castings, US ITC tariff schedules, corporate 10-K and annual investor filings from listed machine builders and foundries, patent databases covering vacuum-assisted and squeeze casting, and technical standards published by recognized industry associations. Carbon-border and emissions timelines were validated against official EU regulatory publications.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous top-down and bottom-up models. Top-down allocated macroeconomic automotive, electronics and industrial output to casting intensity and then to equipment replacement and expansion spend. Bottom-up modeled manufacturer capacity, average selling price by tonnage class, and end-use consumption at the plant level. Divergences were reconciled against trade data and disclosed order books.
 High Pressure Die Casting Equipment Market