 Us Ent Endoscopy Market
U.S. ENT Endoscopy Market Size & Forecast 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 231

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Ent Endoscopy Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 305.0 M |
| 2026 | 327.0 M |
| 2027 | 344.0 M |
| 2028 | 362.0 M |
| 2029 | 381.0 M |
| 2030 | 401.0 M |
| 2031 | 422.0 M |

The U.S. ENT endoscopy market covers flexible and rigid endoscopes, video processors, and visualization systems used by otolaryngologists to diagnose and treat ear, nose, and throat disorders. It spans hospital operating rooms, ambulatory surgery centers, and physician offices, with revenue driven by sinus, laryngology, and otology procedure volumes.
This report covers U.S. revenue for flexible and rigid ENT endoscopes, associated video towers, processors, and single-use devices across hospital, ASC, and office-based settings. It segments by product type, setting, and sub-region. This analysis does not cover hearing screening devices, surgical navigation capital equipment, general dental scopes, or veterinary endoscopy.
Published estimates converge on a low-hundreds-of-millions base, but they diverge on horizon and scope. The table below isolates the competing figures and their definitions so buyers can judge comparability before committing capital.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 305.1 million | 2025 | 2033 | 5.2% | U.S. ENT endoscopes and visualization, all settings | One published estimate |
| USD 326.9 million | 2026 | 2033 | 5.2% | Same U.S. scope, forward base year | Derived from stated base and CAGR |
| USD 466.8 million | 2033 | 2033 | 5.2% | Terminal forecast, same scope | One published estimate |
Our analysis suggests the 5.2% figure is the most defensible U.S. planning number because it reconciles procedure growth, office-based migration, and modest capital replacement cycles. Global figures near USD 6.36 billion reflect a much broader device definition and should not be used for U.S. budgeting.
Segmentation splits primarily by product flexibility and care setting, and the mix matters because office-based migration rewards compact, lower-cost systems over full tower installations.
| Parent Segment | Children | 2025 Share Signal |
|---|---|---|
| Product Type | Flexible endoscopes, Rigid endoscopes | Flexible 73.5% |
| Setting | Hospital, Ambulatory surgery centers, Physician office/office-based | Office-based 50.8% |
| Usability | Reusable, Single-use, Limited-use | Reusable dominant; single-use fastest-growing |
| Application | Rhinology, Laryngology, Otology, Pediatric ENT | Rhinology largest |
This divergence implies vendors must maintain two commercial motions: premium reusable platforms for hospitals and disposable or compact systems for offices. A single portfolio strategy will lose share at one end of the market.
The Southeast leads with 28.79% of 2025 revenue, followed by the Southwest and Northeast, reflecting population density, ENT practice concentration, and outpatient surgery capacity.
| Region | Market Share (%) |
|---|---|
| Southeast | 0.29% |
| Southwest | 0.21% |
| Northeast | 0.19% |
| Midwest | 0.17% |
| West | 0.15% |
Our analysis suggests the Southeast's lead is structural, not cyclical, because outpatient sinus and laryngology volume continues migrating there. Vendors should weight service coverage toward this region before expanding elsewhere.
Minimally invasive migration and chronic sinus disease burden are the primary demand engines, while capital cost and reprocessing risk constrain adoption at smaller practices.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Minimally invasive and office-based ENT procedures | Driver | High | Shifts procedures out of ORs, expanding scope demand |
| Chronic sinusitis and upper-airway disease burden | Driver | High | Sustains rhinology procedure volume and repeat scopes |
| HD/4K and digital visualization upgrades | Driver | Medium-High | Triggers replacement of older scope and tower fleets |
| ASC and outpatient ENT expansion | Driver | Medium | Creates compact-system and single-use demand |
| High capital and recurring cost | Restraint | High | Delays purchase decisions at low-volume practices |
| Reprocessing and cross-contamination risk | Restraint | Medium-High | Raises compliance burden for reusable fleets |
The balance favors growth, but the restraint is not trivial: a reusable scope plus tower can exceed USD 33,000 before servicing, while single-use devices run up to roughly USD 170 per procedure. Our analysis suggests the crossover point sits at moderate-to-high procedure volume, making volume forecasting the single most important pre-purchase calculation.
Competition is medium-concentrated, with established visualization leaders defending installed bases against compact-system and single-use entrants.
| Company | Primary Strength | Portfolio Position |
|---|---|---|
| Medtronic | Broad ENT and surgical portfolio | Incumbent reusable base |
| Olympus | 4K/3D visualization platforms | Premium imaging leadership |
| KARL STORZ | Rigid optics and OR integration | Hospital stronghold |
| FUJIFILM | Flexible endoscopy and imaging | Diagnostic scope depth |
| Stryker | Surgical workflow and visualization | Cross-portfolio bundling |
| Emerging compact entrants | Office-based towerless systems | Niche disruption |
Differentiation is shifting from optics alone to workflow integration: connectivity, documentation, and service footprint now decide renewals. Moats are built on installed-base lock-in and reprocessing support, not on individual device specifications.
Selection should start with procedure volume, not device features, because volume determines whether reusable or single-use economics prevail. Buyers should require total-cost-of-ownership modeling covering acquisition, reprocessing labor, repair frequency, and downtime, then stress-test it against realistic case growth.
Procurement risk concentrates in service coverage and turnaround time; a failed scope between procedures costs more than its repair invoice. Switching costs are substantial for tower-based fleets, so contract terms should include upgrade paths to HD/4K platforms rather than locked configurations. Regulatory compliance around reprocessing and infection control is non-negotiable and should be validated in vendor audits, not assumed from marketing claims.
The balance of evidence favors a volume-tiered procurement strategy over a single-platform commitment. The 5.2% U.S. growth rate is credible because it rests on structural procedure migration and disease burden, not on a technology refresh cycle alone. The strongest counter-argument is that single-use conversion could compress reusable revenue faster than forecasts assume, but per-procedure costs still cap that shift at high-volume sites.
For vendors, the Southeast concentration and office-based majority mean service density and compact-system portfolios will decide share gains. For buyers, the reusable-versus-single-use decision should be revisited annually as procedure volumes change, because the crossover point moves.
What would change this conclusion: a sustained drop in single-use pricing below roughly USD 80 per procedure, or a major reprocessing safety incident, would accelerate reusable displacement and invalidate the volume-tiered thesis. Precise sub-segment forecasting beyond published scope requires the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.2% from 2020-2034 |
| Segmentation |
|
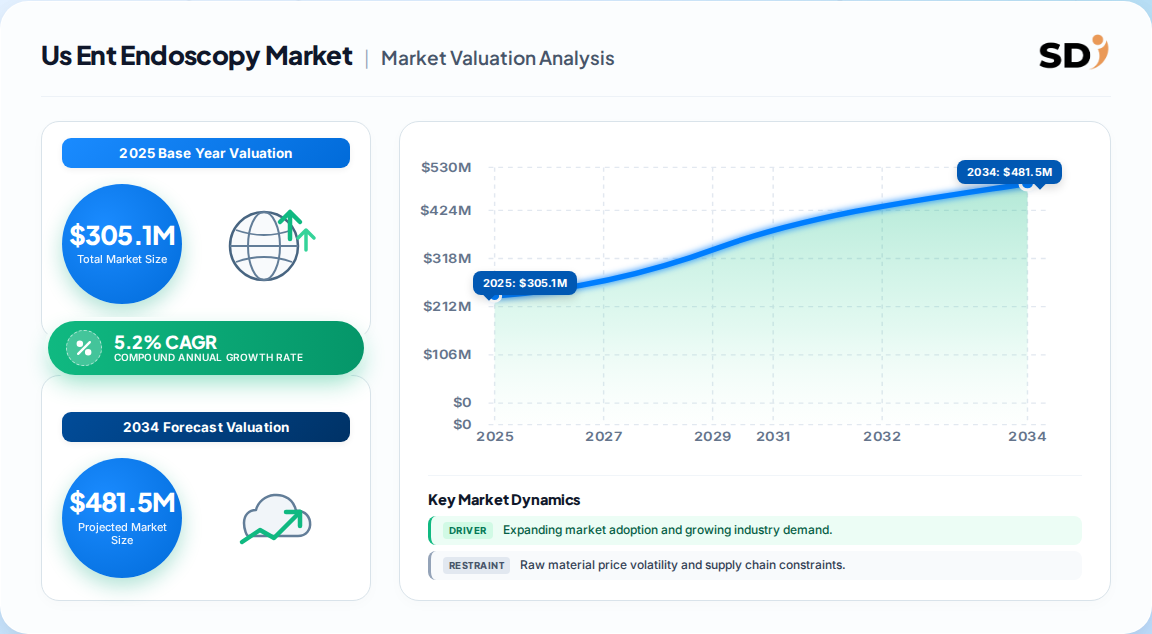
The U.S. ENT endoscopy market was valued at USD 305.1 million in 2025 and is estimated at USD 326.9 million in 2026, growing at a 5.2% CAGR toward USD 466.8 million by 2033.
Single-use ENT endoscopy devices are the fastest-emerging segment, driven by infection-control concerns and office-based care, though reusable platforms still hold the majority of installed base revenue.
The Southeast region led with 28.79% of 2025 revenue, supported by dense outpatient ENT practice concentration and ambulatory surgery capacity, followed by the Southwest and Northeast.
Leading vendors include Medtronic, Olympus, KARL STORZ, FUJIFILM, and Stryker, competing on visualization quality, workflow integration, and service coverage rather than device specifications alone.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the ENT endoscopy value chain, including optical component and scope manufacturers, video processor and visualization platform producers, single-use device specialists, and national medical-device distributors. Interview panels were stratified by decision-maker designation, covering VP-level sourcing executives, Heads of R&D and product engineering, Technical Directors for reprocessing and infection control, and Commercial Operations Leads responsible for U.S. territory coverage and service networks.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement | 35% |
| R&D and Product Engineering Heads | 30% |
| Reprocessing & Infection-Control Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Scope & Optics Manufacturers | 40% |
| Visualization Platform Producers | 25% |
| Single-Use Device Specialists | 20% |
| National Medical Distributors | 15% |
Secondary validation draws on official multilateral trade and standards databases, including UN Comtrade and WITS for cross-border flow direction, U.S. International Trade Commission filings for import classification, and FDA device registration and clearance records for product authorization timelines. Corporate annual filings, 10-K disclosures, and investor presentations were reviewed for capacity, revenue mix, and portfolio positioning. Patent databases and recognized technical standards bodies were used to benchmark imaging, reprocessing, and single-use design trends.
We run simultaneous Top-Down and Bottom-Up models. The Top-Down model allocates macroeconomic healthcare expenditure and ENT procedure volumes across settings and product types. The Bottom-Up model builds revenue from manufacturer capacity, scope unit pricing, replacement cycles, and end-use consumption by practice type. Divergences between the two are reconciled against interview evidence before any forecast is finalized.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |