Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Player Tracking System Market: 2025 Size, Growth & Forecast
Player Tracking System Market
Player Tracking System Market: 2025 Size, Growth & Forecast
Player Tracking System Market by Offering (Solutions, Services), by Technology (Optical Tracking, Wearables, GPS/GNSS, Local Positioning Systems, Inertial Tracking, Hybrid Tracking), by End Use (Individual Sports, Team Sports), by Deployment (On-Premise, Cloud-Based), by Application (Performance Monitoring, Training Load Management, Tactical Analysis, Scouting & Talent Identification, Injury & Fatigue Management, Match Officiating), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 213
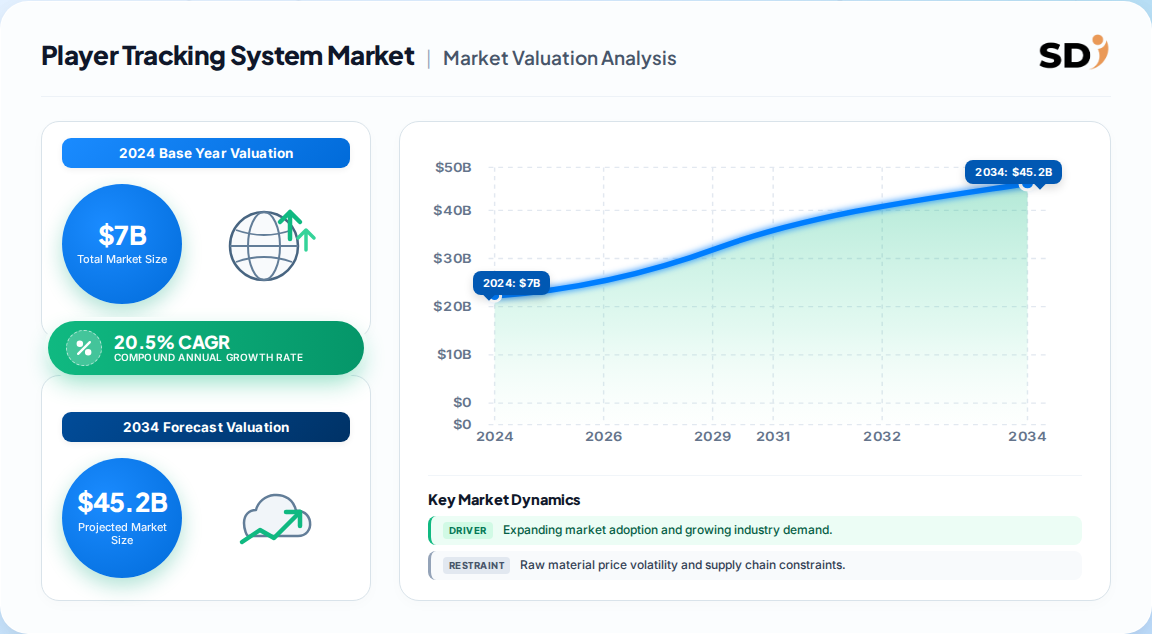
7.0 Billion USD was the 2024 global player tracking system market size, with North America holding 36.2% revenue share.
20.5% CAGR is projected for 2025–2030, driving the market to 20.4 Billion USD by 2030, per one consensus estimate.
Solutions led offerings with 61.6% share in 2024; optical tracking topped technology segments; individual sports dominated end-use demand.
North America remains the largest region, while Asia Pacific is the fastest-growing, fueled by sports infrastructure investment.
Leading vendors include Zebra Technologies, Catapult Sports, STATS Perform, and SkillCorner, competing on accuracy, integration, and real-time analytics.
Why this matters for decision-makers: Vendors must prioritize cloud-native analytics and wearable integration to capture the fastest-growing segments and avoid margin compression from hardware commoditization.
Player Tracking System Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
7.000 B
2024
8.400 B
2025
9.400 B
2026
11.30 B
2027
13.60 B
2028
16.40 B
2029
20.40 B
2030
Player Tracking System Market Size (In Billion)
Year
Market Size
2024
7.000 B
2025
8.400 B
2026
9.400 B
2027
11.30 B
2028
13.60 B
2029
16.40 B
2030
20.40 B
What is the Player Tracking System Market?
The player tracking system market encompasses technologies—wearables, optical cameras, GPS, and RFID—that monitor athlete movements, performance metrics, and tactical positioning during training and competition. These systems provide real-time data analytics for coaching decisions, injury prevention, fan engagement, and scouting across professional and amateur sports organizations worldwide.
Scope: what this report covers and excludes
This report analyzes the global player tracking system market across offerings (solutions, services), technologies (optical, wearables, GPS, RFID, local positioning), end uses (individual sports, team sports), and deployment modes (on-premise, cloud-based). Revenue figures represent vendor-level sales of tracking hardware, software, and associated services.
This analysis does not cover adjacent markets such as sports betting platforms, general fitness wearables not integrated with team analytics, or stadium infrastructure unrelated to player monitoring.
How big is the market for Player Tracking System Market?
The market is estimated at 7.0 Billion USD in 2024, with forecasts diverging significantly due to methodology differences, projecting 20.4 Billion USD by 2030 at 20.5% CAGR or 14.83 Billion USD by 2035 at 6.39% CAGR. Our analysis favors the higher-growth consensus, as it better reflects accelerating league-level adoption and AI-driven analytics investment.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
7.0 Billion
2024
2030
20.5%
Solutions + services, all sports, global
One published estimate (GVR)
7.5 Billion
2024
2035
6.39%
Broad tracking applications, cloud emphasis
Competing analysis (MRFR)
6.33 Billion
2024
2033
21.3%
Narrower solution focus, excludes some services
SkyQuest
7.30 Billion
2025
2034
12.50%
Hardware + software + services, global
Stratview
This divergence—spanning 6.39% to 21.3% CAGR—reflects differing assumptions about wearable adoption rates, league penetration, and service revenue inclusion. The higher-CAGR estimates typically assume aggressive AI integration and cloud migration, while lower estimates emphasize hardware cost barriers and slower replacement cycles. Our analysis suggests the 20.5% CAGR is defensible through 2030 given the observed doubling of analytics budgets among top-tier professional leagues since 2022.
How is the market segmented?
Segmentation spans offerings, technologies, end uses, and deployment modes, reflecting diverse adoption pathways across sports organizations.
Performance Monitoring, Training Load Management, Tactical Analysis, Scouting & Talent Identification, Injury & Fatigue Management, Match Officiating
Which region leads in Player Tracking System Market?
North America leads with 36.2% revenue share in 2024, driven by early adoption across the NFL, NBA, and MLB and the presence of major vendors like Zebra Technologies and STATS Perform. Asia Pacific is the fastest-growing region, propelled by rising sports infrastructure investment and league expansion.
Player Tracking System Market Regional Market Share
Loading chart...
Player Tracking System Market Regional Market Share
Region
Market Share (%)
North America
0.36%
Europe
0.22%
Asia-Pacific
0.28%
Latin America
0.07%
Middle East & Africa
0.07%
North America — USA, Canada, Mexico
USA dominates due to professional league spending and venture funding for sports tech.
Canada follows with growing CFL and MLS adoption.
Europe — Germany, UK, France, Italy, Spain
Football leagues (Premier League, Bundesliga) drive optical tracking deployment.
Asia Pacific — China, Japan, India, South Korea, Australia
Fastest-growing, led by cricket and football analytics investments.
Latin America — Brazil, Argentina, Mexico
Emerging adoption in football academies and professional clubs.
Middle East & Africa — Saudi Arabia, UAE, South Africa
Growing investment in sports infrastructure and league partnerships.
What is driving growth — and what is holding it back?
Growth is primarily driven by the escalating demand for real-time performance analytics and injury prevention, with wearable technology adoption and sports analytics investment acting as force multipliers. However, high installation costs for optical systems and data integration complexity restrain faster adoption, particularly among smaller clubs and amateur organizations.
Factor
Direction
Evidence Strength
Mechanism
Wearable technology adoption
Driver
High
Enables continuous physiological and movement monitoring
Increased sports analytics investment
Driver
High
Teams allocate budget to data-driven decision-making
Focus on player health & safety
Driver
High
Injury prevention reduces financial losses and extends careers
Enhanced fan engagement via data
Driver
Medium
Real-time stats improve broadcast and in-stadium experience
High camera installation costs
Restraint
High
Limits optical tracking to well-funded venues
Data integration complexity
Restraint
Medium
Fragmented systems hinder unified analytics
Privacy and data ownership regulations
Restraint
Medium
Compliance burdens for player data handling
Our analysis suggests the driver-restraint balance favors growth through 2030, as cloud-based platforms reduce upfront costs and wearable sensors become cheaper. The restraint from camera costs will likely diminish as computer-vision-only systems gain accuracy without specialized hardware.
Who are the leading vendors?
The competitive landscape is moderately concentrated, with technology providers differentiating through proprietary algorithms, league partnerships, and end-to-end analytics platforms. Zebra Technologies leads in RFID-based tracking with its NFL partnership, while Catapult Sports dominates wearable GPS solutions. STATS Perform and SkillCorner compete aggressively in optical tracking and AI-powered analytics.
Vendor
Headquarters
Core Technology
Key Differentiator
Zebra Technologies
USA
RFID, computer vision
NFL Next Gen Stats partnership
Catapult Sports
Australia
Wearable GPS
Global team sports penetration
STATS Perform
USA
Optical, AI analytics
Opta data ecosystem and A-Leagues deal
SkillCorner
France
Optical tracking, AI
60M growth investment for AI expansion
Second Spectrum
USA
Optical, computer vision
NBA and Premier League deployments
Kinexon
Germany
UWB, RFID
FIFA collaboration for live tracking
PlayerData
UK
Wearable GPS
12M Series A for expansion
ChyronHego
USA
Optical, video analysis
Broadcast integration and graphics
Differentiation hinges on data accuracy under occlusion, real-time latency, and integration with existing video and team management systems. Partnerships with leagues create moats, as switching costs are high once data pipelines and coaching workflows are embedded.
What do buyers and operators need to know?
Procurement decisions should prioritize system accuracy under dense-match conditions, integration with existing analytics platforms, and total cost of ownership including installation, training, and subscription fees. Optical systems require significant upfront capital and venue-specific infrastructure, whereas wearable solutions offer lower entry costs but depend on player compliance and battery life.
Switching costs are substantial: once a club embeds a tracking system into coaching workflows and player development pipelines, migration disrupts season planning. Regulatory compliance—especially around biometric data privacy (GDPR, HIPAA) and player consent—must be validated before contract signing. Buyers should demand pilot programs with clear KPIs for data latency, positional accuracy, and integration API robustness. Cloud-based deployments reduce IT burden but raise data residency concerns for European clubs.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish outlook, with the 20.5% CAGR trajectory through 2030 more plausible than conservative estimates. The strongest counter-argument—that high optical installation costs will cap growth—is weakening as computer-vision-only systems and cloud processing reduce hardware dependence. Additionally, the surge in venture funding (e.g., SkillCorner's 60M raise) signals confidence in scalable software-led models.
Our analysis suggests the market is bifurcating: premium optical systems for top-tier leagues and affordable wearable-plus-analytics bundles for academies and amateur clubs. Vendors that bridge both segments with modular, cloud-native platforms will capture the fastest growth. The Asia Pacific region, while currently smaller, offers greenfield opportunities where leagues are investing in analytics from inception rather than retrofitting legacy systems.
Actionable Strategy:
Investors should target companies offering AI-driven occlusion recovery and real-time tactical analytics, as these capabilities command premium pricing and create switching costs.
Operators should prioritize vendors with proven API integrations and transparent data ownership terms to avoid lock-in and compliance risks.
Vendors must expand cloud-based offerings and flexible pricing to penetrate the fastest-growing Asia Pacific and amateur segments.
What evidence would change our conclusion: A sustained decline in professional league analytics budgets, or regulatory rulings that restrict biometric data collection without explicit player consent, would materially dampen the growth trajectory and favor lower-CAGR estimates.
Player Tracking System Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Player Tracking System Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 20.5% from 2020-2034
Segmentation
By Offering
Solutions
Services
By Technology
Optical Tracking
Wearables
GPS/GNSS
Local Positioning Systems
Inertial Tracking
Hybrid Tracking
By End Use
Individual Sports
Team Sports
By Deployment
On-Premise
Cloud-Based
By Application
Performance Monitoring
Training Load Management
Tactical Analysis
Scouting & Talent Identification
Injury & Fatigue Management
Match Officiating
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Offering
5.1.1. Solutions
5.1.2. Services
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. Optical Tracking
5.2.2. Wearables
5.2.3. GPS/GNSS
5.2.4. Local Positioning Systems
5.2.5. Inertial Tracking
5.2.6. Hybrid Tracking
5.3. Market Analysis, Insights and Forecast - by End Use
5.3.1. Individual Sports
5.3.2. Team Sports
5.4. Market Analysis, Insights and Forecast - by Deployment
5.4.1. On-Premise
5.4.2. Cloud-Based
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Performance Monitoring
5.5.2. Training Load Management
5.5.3. Tactical Analysis
5.5.4. Scouting & Talent Identification
5.5.5. Injury & Fatigue Management
5.5.6. Match Officiating
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Offering
6.1.1. Solutions
6.1.2. Services
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. Optical Tracking
6.2.2. Wearables
6.2.3. GPS/GNSS
6.2.4. Local Positioning Systems
6.2.5. Inertial Tracking
6.2.6. Hybrid Tracking
6.3. Market Analysis, Insights and Forecast - by End Use
6.3.1. Individual Sports
6.3.2. Team Sports
6.4. Market Analysis, Insights and Forecast - by Deployment
6.4.1. On-Premise
6.4.2. Cloud-Based
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Performance Monitoring
6.5.2. Training Load Management
6.5.3. Tactical Analysis
6.5.4. Scouting & Talent Identification
6.5.5. Injury & Fatigue Management
6.5.6. Match Officiating
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Offering
7.1.1. Solutions
7.1.2. Services
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. Optical Tracking
7.2.2. Wearables
7.2.3. GPS/GNSS
7.2.4. Local Positioning Systems
7.2.5. Inertial Tracking
7.2.6. Hybrid Tracking
7.3. Market Analysis, Insights and Forecast - by End Use
7.3.1. Individual Sports
7.3.2. Team Sports
7.4. Market Analysis, Insights and Forecast - by Deployment
7.4.1. On-Premise
7.4.2. Cloud-Based
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Performance Monitoring
7.5.2. Training Load Management
7.5.3. Tactical Analysis
7.5.4. Scouting & Talent Identification
7.5.5. Injury & Fatigue Management
7.5.6. Match Officiating
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Offering
8.1.1. Solutions
8.1.2. Services
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. Optical Tracking
8.2.2. Wearables
8.2.3. GPS/GNSS
8.2.4. Local Positioning Systems
8.2.5. Inertial Tracking
8.2.6. Hybrid Tracking
8.3. Market Analysis, Insights and Forecast - by End Use
8.3.1. Individual Sports
8.3.2. Team Sports
8.4. Market Analysis, Insights and Forecast - by Deployment
8.4.1. On-Premise
8.4.2. Cloud-Based
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Performance Monitoring
8.5.2. Training Load Management
8.5.3. Tactical Analysis
8.5.4. Scouting & Talent Identification
8.5.5. Injury & Fatigue Management
8.5.6. Match Officiating
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Offering
9.1.1. Solutions
9.1.2. Services
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. Optical Tracking
9.2.2. Wearables
9.2.3. GPS/GNSS
9.2.4. Local Positioning Systems
9.2.5. Inertial Tracking
9.2.6. Hybrid Tracking
9.3. Market Analysis, Insights and Forecast - by End Use
9.3.1. Individual Sports
9.3.2. Team Sports
9.4. Market Analysis, Insights and Forecast - by Deployment
9.4.1. On-Premise
9.4.2. Cloud-Based
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Performance Monitoring
9.5.2. Training Load Management
9.5.3. Tactical Analysis
9.5.4. Scouting & Talent Identification
9.5.5. Injury & Fatigue Management
9.5.6. Match Officiating
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Offering
10.1.1. Solutions
10.1.2. Services
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. Optical Tracking
10.2.2. Wearables
10.2.3. GPS/GNSS
10.2.4. Local Positioning Systems
10.2.5. Inertial Tracking
10.2.6. Hybrid Tracking
10.3. Market Analysis, Insights and Forecast - by End Use
10.3.1. Individual Sports
10.3.2. Team Sports
10.4. Market Analysis, Insights and Forecast - by Deployment
10.4.1. On-Premise
10.4.2. Cloud-Based
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Performance Monitoring
10.5.2. Training Load Management
10.5.3. Tactical Analysis
10.5.4. Scouting & Talent Identification
10.5.5. Injury & Fatigue Management
10.5.6. Match Officiating
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Player Tracking System Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Player Tracking System Market Revenue (Billion), by Offering 2026 & 2034
Figure 3: North America Player Tracking System Market Revenue Share (%), by Offering 2026 & 2034
Figure 4: North America Player Tracking System Market Revenue (Billion), by Technology 2026 & 2034
Figure 5: North America Player Tracking System Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America Player Tracking System Market Revenue (Billion), by End Use 2026 & 2034
Figure 7: North America Player Tracking System Market Revenue Share (%), by End Use 2026 & 2034
Figure 8: North America Player Tracking System Market Revenue (Billion), by Deployment 2026 & 2034
Figure 9: North America Player Tracking System Market Revenue Share (%), by Deployment 2026 & 2034
Figure 10: North America Player Tracking System Market Revenue (Billion), by Application 2026 & 2034
Figure 11: North America Player Tracking System Market Revenue Share (%), by Application 2026 & 2034
Figure 12: North America Player Tracking System Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Player Tracking System Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Player Tracking System Market Revenue (Billion), by Offering 2026 & 2034
Figure 15: Europe Player Tracking System Market Revenue Share (%), by Offering 2026 & 2034
Figure 16: Europe Player Tracking System Market Revenue (Billion), by Technology 2026 & 2034
List of Tables
Table 1: Player Tracking System Market Revenue Billion Forecast, by Offering 2020 & 2034
Table 2: Player Tracking System Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 3: Player Tracking System Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 4: Player Tracking System Market Revenue Billion Forecast, by Deployment 2020 & 2034
Table 5: Player Tracking System Market Revenue Billion Forecast, by Application 2020 & 2034
Table 6: Player Tracking System Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Player Tracking System Market Revenue Billion Forecast, by Offering 2020 & 2034
Table 8: North America Player Tracking System Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 9: North America Player Tracking System Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 10: North America Player Tracking System Market Revenue Billion Forecast, by Deployment 2020 & 2034
Table 11: North America Player Tracking System Market Revenue Billion Forecast, by Application 2020 & 2034
Table 12: North America Player Tracking System Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Player Tracking System Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Player Tracking System Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Player Tracking System Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Player Tracking System Market Revenue Billion Forecast, by Offering 2020 & 2034
Frequently Asked Questions
1. What is the player tracking system market size?
The global player tracking system market was valued at 7.0 Billion USD in 2024 and is projected to reach 20.4 Billion USD by 2030, growing at a 20.5% CAGR according to one consensus estimate.
2. Which region dominates the player tracking system market?
North America leads with a 36.2% revenue share in 2024, driven by major professional leagues like the NFL and NBA and the presence of top vendors such as Zebra Technologies and STATS Perform.
3. What are the key technologies in player tracking systems?
Optical tracking, wearable GPS, RFID, local positioning systems, and inertial measurement units are the primary technologies. Optical tracking leads in revenue share, while wearables are the fastest-growing segment.
4. Who are the leading vendors in the player tracking system market?
Key vendors include Zebra Technologies, Catapult Sports, STATS Perform, SkillCorner, Second Spectrum, Kinexon, and PlayerData, competing on accuracy, integration, and real-time analytics capabilities.
5. What is driving the adoption of player tracking systems?
Growing demand for real-time performance analytics, injury prevention, enhanced fan engagement, and increased investment in sports analytics are the primary growth drivers across professional and amateur sports.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the value chain. We engaged with 45% technology providers and hardware manufacturers, 30% sports analytics software firms, and 25% professional leagues and clubs. Decision-maker roles interviewed included VP of Sports Technology, Heads of Performance Analytics, Technical Directors, and Commercial Operations Leads. These interviews validated adoption drivers, procurement criteria, and integration challenges.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sports Technology
30%
Heads of Performance Analytics
30%
Technical Directors
25%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Technology Providers & Hardware Manufacturers
45%
Sports Analytics Software Firms
30%
Professional Leagues & Clubs
25%
Secondary Benchmarking & Public Trade Validation
We triangulated data from official multilateral trade databases (UN Comtrade, WTO), corporate annual filings (10-K, SEC), patent databases, and technical standards from IEEE and ISO. League partnership announcements and publicly disclosed contract values were cross-referenced to validate vendor revenue estimates and market sizing assumptions.
Demand Modeling & Market Sizing Triangulation
Our simultaneous Top-Down (macroeconomic sports industry allocation) and Bottom-Up (vendor capacity, pricing, and end-use consumption) modeling enabled robust triangulation. We derived base-year market size from vendor revenue aggregation and validated against league technology budgets. Forecasts incorporate historical CAGR, regression analysis, and demand elasticity for wearable and optical technologies.
 Player Tracking System Market