 Europe Dog Dewormers Market
: Size, Growth & Outlook 2025
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 244

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Europe Dog Dewormers Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 503.0 M |
| 2025 | 543.0 M |
| 2026 | 586.0 M |
| 2027 | 633.0 M |
| 2028 | 684.0 M |
| 2029 | 738.0 M |
| 2030 | 797.0 M |

The Europe dog dewormers market comprises veterinary pharmaceutical products — tablets, chewables, liquids, spot-ons, and injectables — formulated to prevent and treat internal helminth infections in dogs, including roundworms, tapeworms, hookworms, and whipworms. It is regulated largely as prescription veterinary medicine and distributed through clinics, retail, and online pharmacies across European countries.
This report covers the Europe-focused dog dewormer market segmented by route of administration, dosage form, product type, distribution channel, and country. This analysis does not cover flea and tick treatments sold without an intestinal worm claim, standalone heartworm preventives, cat and horse dewormers, livestock anthelmintics, or veterinary diagnostics.
Estimates vary materially, so buyers should reconcile scope before adopting any single figure. The table below compares the leading published benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 242 Million | 2024 | 2030 | 7.76% | Core dog dewormers, oral/injectable/topical | One published estimate |
| 225 Million | 2023 | 2033 | 7.85% | Dog dewormers, route and dosage form | A competing analysis |
| 427 Million | 2023 | 2033 | 10.67% | Broad dog dewormers including premium formats | Another published estimate |
| 596 Million | 2026 | 2035 | 8.30% | Broader endectocide-inclusive definition | A third-party benchmark |
Our analysis suggests the most defensible 2025 base is approximately 543 Million, anchored between the 2026 and 2024 benchmarks and adjusted for the shift toward higher-priced monthly combination products. The wide spread between 242 Million and 596 Million reflects genuine definitional disagreement over whether isoxazoline endectocides and combined flea–worm products are counted — a methodological gap the full report resolves.
Segmentation reveals where value concentrates. The table below summarizes non-geographic parents and their children.
| Parent Segment | Children | 2025 Share |
|---|---|---|
| Route of Administration | Oral, Injectable, Topical | Oral ~70% |
| Dosage Form | Liquids, Tablets | Liquids ~54% |
| Product Type | Multi-ingredient broad-spectrum, Milbemycin oxime combinations, Isoxazoline endectocides, Benzimidazoles, Macrocyclic lactone spot-ons, Others | Broad-spectrum ~37% |
| Type | Prescription, OTC | Prescription ~64% |
| Distribution Channel | Veterinary clinics/hospitals, Retail/pet stores, E-commerce | Clinics ~50% |
The oral route dominates because it delivers drug directly to the gastrointestinal tract with high compliance. Liquids retain share due to ease of mixing with food, but tablets are gaining fastest as palatable chewables improve owner acceptance.
Germany leads the Europe dog dewormers market with roughly 19.6% share, driven by one of Europe's largest dog populations and high veterinary spending. The UK and France follow at 17.8% and 15.4% respectively.
Rising dog ownership, zoonotic disease awareness, and a shift to monthly combination products are the primary growth engines. However, generic competition and low owner compliance constrain volume expansion.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising dog ownership (~106M dogs) | Driver | High | Expands addressable population |
| Zoonotic disease awareness | Driver | High | Promotes routine deworming |
| Shift to monthly combination endectocides | Driver | High | Raises spend per dog |
| E-commerce and subscription models | Driver | Medium | Improves repeat purchase convenience |
| Generic broad-spectrum competition | Restraint | High | Pressures prices on routine tablets |
| Low owner compliance (8.6–16%) | Restraint | High | Caps volume growth |
| Prescription rules limiting OTC access | Restraint | Medium | Restricts channel reach |
The balance favors growth: the shift from twice-yearly to quarterly or monthly deworming and the premiumization toward combination products lift value even where dog numbers plateau. Generic price pressure is real but largely confined to the routine broad-spectrum tablet segment, which is losing relative share.
The competitive landscape is concentrated among global animal-health majors with broad portfolios, alongside regional specialists in Central and Eastern Europe.
| Company | Portfolio Strength | Geographic Footprint |
|---|---|---|
| Zoetis | Broad antiparasitic portfolio | Pan-European |
| Boehringer Ingelheim | Strong prescription and combination lines | Pan-European |
| Merck & Co. | Broad-spectrum and endectocide range | Pan-European |
| Elanco | Growing dewormer and parasiticide range | Pan-European |
| Virbac | Specialist parasiticide focus | Western and Southern Europe |
| Ceva | Veterinary-focused portfolio | France-centric, expanding |
| Dechra | Prescription dermatology and parasitology | UK and Northern Europe |
| Vetoquinol | Companion animal portfolio | France and Benelux |
| Bioveta | Regional broad-spectrum | Central and Eastern Europe |
Differentiation increasingly hinges on formulation palatability and combination breadth rather than active ingredient novelty. Moats are built through veterinary detailing relationships, regulatory dossiers for combination claims, and subscription-based online pharmacy reach.
Procurement decisions hinge on three mission-critical criteria: regulatory classification (prescription versus OTC) in each target country, demonstrated efficacy against locally prevalent parasites, and palatability that drives owner compliance. Switching costs are moderate for clinics but rising for online pharmacies locked into subscription models with specific manufacturers.
The largest procurement risk is regulatory divergence — EMA-level harmonization coexists with national prescription rules that restrict cross-border online sales. Buyers should verify country-specific dispensing rules before committing to distribution agreements. Compliance risks include resistance management requirements, which increasingly favor prescription-only protocols and limit the scope for blanket OTC launches.
The balance of evidence favors a premiumization-led growth thesis rather than a volume-led one. Dog numbers in Europe are broadly stable, yet market value is compounding well above GDP because treatment frequency is rising and owners are migrating toward higher-priced monthly combination products. Vendors anchored to commodity broad-spectrum tablets face structural margin pressure even as the overall market expands.
The strongest counter-argument is that generic competition and stubbornly low compliance (only 8.6% of UK dogs and 16% of Dutch dogs meet guidance) could cap volume growth below forecast. That risk is real, but it is offset by the pricing lever: a smaller treated population paying for premium combinations can still deliver 8% CAGR. The decisive variable is not dog count but the speed of conversion from intermittent to preventive protocols.
The evidence that would change our conclusion is a sustained acceleration in generic substitution or a regulatory tightening that restricts online pharmacy sales of prescription dewormers across major markets.
| Region | Market Share (%) |
|---|---|
| Germany | 0.2% |
| United Kingdom | 0.18% |
| France | 0.15% |
| Italy | 0.09% |
| Spain | 0.09% |
| Poland | 0.06% |
| Netherlands | 0.05% |
| Rest of Europe | 0.19% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.0% from 2020-2034 |
| Segmentation |
|
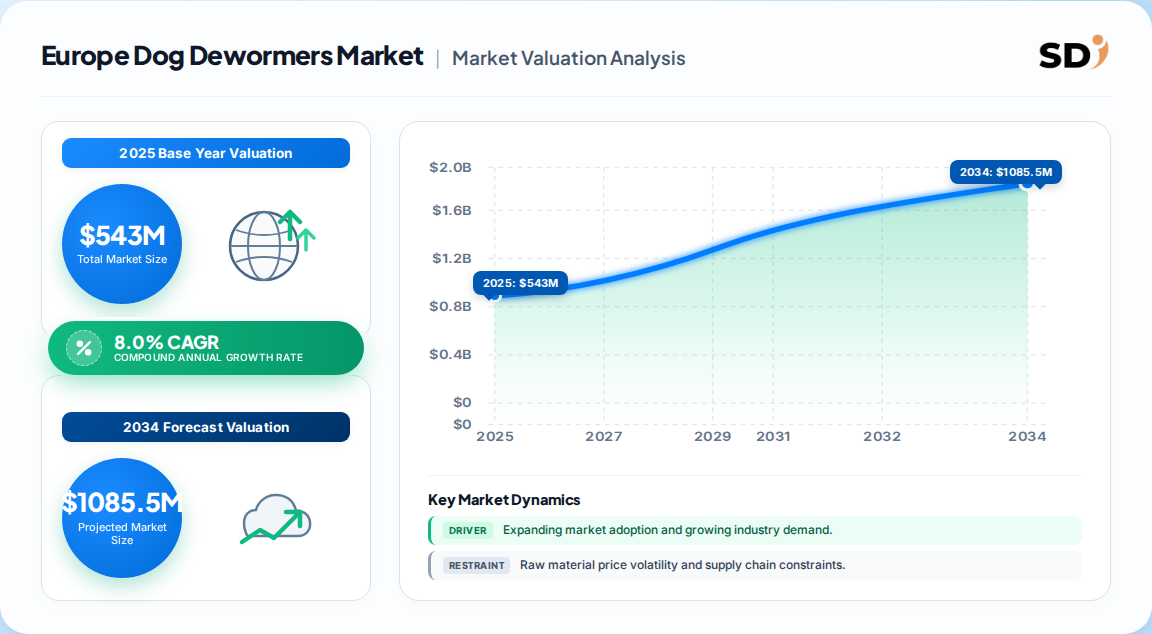
The market is estimated at approximately 543 Million in 2025, reflecting a mid-point reconciliation of published benchmarks that range from 242 Million to 596 Million depending on whether combination endectocides are included.
Growth is estimated at around 8.0% CAGR through 2032, driven primarily by rising treatment frequency and premiumization toward monthly combination products rather than growth in dog numbers.
Germany leads with approximately 19.6% share, supported by one of Europe's largest dog populations and high veterinary spending, followed by the United Kingdom at 17.8% and France at 15.4%.
Oral administration dominates with roughly 70% share because it delivers medication directly to the gastrointestinal tract, offers broad-spectrum action, and achieves higher owner compliance than injectable or topical alternatives.
Key players include Zoetis, Boehringer Ingelheim, Merck & Co., Elanco Animal Health, Virbac, Ceva Santé Animale, Dechra Pharmaceuticals, Vetoquinol, and Bioveta, with differentiation increasingly driven by formulation palatability and combination breadth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw material and active pharmaceutical ingredient suppliers, specialized veterinary formulation producers, contract formulators, and pan-European veterinary distributors. Interviewees included VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads at animal-health manufacturers and distributors. Fieldwork captured treatment-frequency behavior, pricing architecture for combination versus single-molecule products, and country-level dispensing rules.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP / Directors of Sourcing | 30% |
| Heads of R&D & Formulation | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 20% |
| Company Type | Representation (%) |
|---|---|
| Active Ingredient & API Suppliers | 30% |
| Veterinary Formulation Producers | 35% |
| Contract Formulators | 20% |
| Veterinary Distributors & Pharmacies | 15% |
Secondary validation draws on Eurostat trade statistics, UN Comtrade pharmaceutical flows, EMA regulatory product databases, national veterinary medicines registries, corporate annual filings and investor presentations (10-K, annual reports), and public guidance from the European Scientific Counsel for Companion Animal Parasites and FEDIAF pet population data.
We triangulate Top-Down allocation (macroeconomic pet-care spend, animal-health segment shares) against Bottom-Up modeling (dog population by country, treated share, treatments per year, and manufacturer price per dose by product type). The cross-check reconciled manufacturer revenues with published market estimates.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |