 Excavator Quick Coupler Market
 Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 268

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Excavator Quick Coupler Market
Srinwanti Kar
Senior Research Analyst

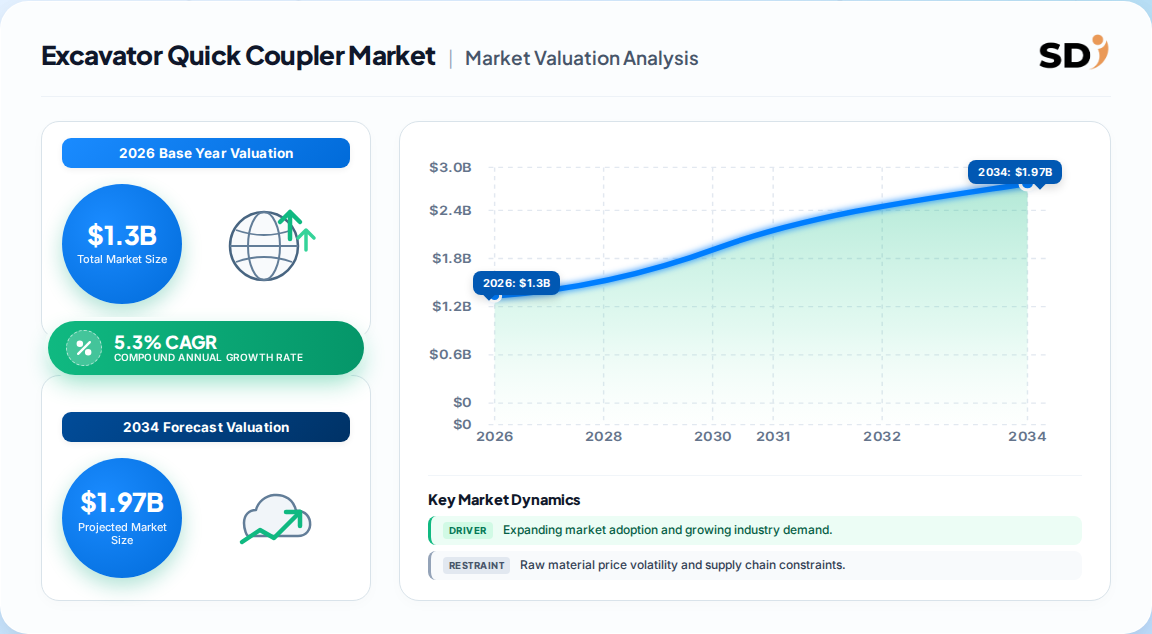
| Year | Market Size |
|---|---|
| 2025 | 1.200 B |
| 2026 | 1.300 B |
| 2027 | 1.370 B |
| 2028 | 1.440 B |
| 2029 | 1.520 B |
| 2030 | 1.600 B |
| 2031 | 1.680 B |

The excavator quick coupler market covers the design, manufacture and sale of attachment-coupling systems that let an excavator operator switch buckets, breakers, grapples and other tools in seconds rather than minutes. It spans mechanical, hydraulic and fully automatic couplers across mini to large excavator classes, sold through OEM and aftermarket channels.
This analysis covers the global excavator quick coupler market across mechanical, hydraulic and fully automatic types, all excavator size classes, and OEM versus aftermarket sales channels. It examines demand drivers, regulatory developments, vendor positioning and regional dynamics for the 2026–2033 forecast period. This analysis does not cover the broader excavator attachment market (buckets, hammers, grapples as standalone products) nor tiltrotator hardware itself, except where coupler compatibility is a direct demand driver.
The most defensible 2026 valuation is approximately USD 1.3 billion, growing to USD 1.9 billion by 2033 at a 5.3% CAGR. A competing analysis anchors the market at USD 1.28 billion in 2025 but forecasts to a 2030 horizon at the same 5.3% rate, implying a slightly more conservative near-term trajectory.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.2B → USD 1.9B | 2025 | 2033 | 5.3% | Global quick coupler revenue, all types and channels | One published estimate |
| USD 1.28B → USD 1.657B | 2025 | 2030 | 5.3% | Global quick coupler statistics, narrower horizon | A competing analysis |
| Quick couplers at 5.05% CAGR | 2025 | 2031 | 5.05% | Coupler segment within construction machinery attachment market | A third-party industry benchmark |
Our analysis suggests the divergence is primarily horizon-driven rather than definitional: both major estimates converge on a mid-single-digit CAGR, and the USD 1.9 billion 2033 figure is consistent with the 5.3% rate compounded over eight years from a ~USD 1.25 billion base. The 5.05% attachment-segment benchmark likely reflects a broader basket excluding standalone aftermarket coupler sales, which is why it sits modestly below the dedicated-market figures.
The market segments primarily by coupler type, excavator size class and sales channel, with type and size class being the most commercially decisive dimensions for vendors and buyers.
| Parent segment | Children |
|---|---|
| By Type | Mechanical, Hydraulic, Fully Automatic |
| By Application (Excavator Class) | Mini Excavator, Small Excavator, Medium-Sized Excavator (15–30t), Large-Sized Excavator |
| By Sales Channel | OEM, Aftermarket |
| By End-Use | Construction, Mining, Demolition, Road Construction, Utilities |
Mechanical couplers retain the largest share because of lower upfront cost and simplicity, but their share is eroding as safety regulations push buyers toward hydraulic and automatic locking systems. Medium-sized excavators dominate application share because they represent the highest-utilization, highest-attachment-change segment in urban and roadbuilding work.
North America leads the global excavator quick coupler market with 35.3% revenue share in 2025, while Asia Pacific is the fastest-growing region over the 2026–2033 forecast period. Europe remains a regulatory bellwether given its early adoption of ISO 13031 safety standards.
| Region | Market Share (%) |
|---|---|
| North America | 0.35% |
| Europe | 0.24% |
| Asia-Pacific | 0.3% |
| South America | 0.05% |
| Middle East & Africa | 0.05% |
North America's lead reflects strong rental-fleet penetration and mature infrastructure-replacement spending. Asia Pacific's growth is driven by China's Belt and Road construction, India's National Infrastructure Pipeline and Southeast Asian urbanization. Europe's trajectory is shaped more by replacement demand and safety-driven upgrades than by net new excavator volume.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Infrastructure development projects | Driver | High | Faster attachment changes reduce downtime on deadline-critical projects |
| Rental-fleet expansion | Driver | High | Multi-attachment compatibility improves fleet utilization and ROI |
| Safety regulation (ISO 13031) | Driver | High | Mandates secure locking and fail-safe design, forcing upgrades |
| Tiltrotator integration | Driver | Medium | Expands coupler value proposition and attachment compatibility |
| Maintenance and hydraulic reliability issues | Restraint | Medium | Downtime and repair costs deter price-sensitive buyers |
| Accidental attachment release risk | Restraint | Medium | Reputational and liability exposure, especially in older semi-automatic models |
| Skilled operator shortage | Restraint | Medium | Complex couplers require training and certified operators |
The balance of evidence favors the drivers. Infrastructure spending and rental-fleet standardization are structural, multi-year forces, while the restraints are largely addressable through product innovation — automatic locking, pressure-retention valves and digital engagement verification directly neutralize the safety concerns that could otherwise slow adoption. Our analysis suggests the highest-growth pocket sits at the intersection of hydraulic/automatic couplers and the rental channel, where utilization economics justify premium pricing.
| Company | Positioning | Notable strength |
|---|---|---|
| Caterpillar Inc. | OEM integrated | Dealer network and OEM-fit couplers |
| Komatsu Ltd. | OEM integrated | Global fleet presence and attachment ecosystem |
| Volvo Construction Equipment | OEM integrated | Safety and telematics integration |
| JCB | OEM integrated | Broad excavator range and aftermarket reach |
| Hitachi Construction Machinery | OEM integrated | Mining and large-excavator applications |
| Steelwrist AB | Specialist | Fully automatic couplers and tiltrotator compatibility |
| OilQuick | Specialist | Automatic coupler systems in European market |
| Miller UK | Specialist | Widely used hydraulic coupler range |
OEMs compete on integration and dealer service, while specialists compete on automatic-locking innovation and compatibility breadth. Moats are built on certification to evolving safety standards, attachment-ecosystem breadth (number of compatible tools) and service-network density. Our analysis suggests specialists hold an innovation edge in fully automatic systems, but OEMs are closing the gap by bundling couplers into new-machine sales and fleet telematics packages.
Coupler selection is a safety-critical decision, not a commodity purchase. Buyers should prioritize certified locking mechanisms, verified engagement indicators and pressure-retention valves, especially for hydraulic and automatic systems where failure modes are less visible to the operator. Regulatory compliance with ISO 13031 and its 2025 amendment should be a minimum tender requirement.
Switching costs are non-trivial: coupler pin dimensions, hydraulic flow ratings and electrical connectors must match the attachment fleet, so standardization decisions cascade across an entire equipment inventory. Rental operators should weight compatibility breadth and serviceability highest, while large fleet owners should demand telematics integration for usage tracking and predictive maintenance. Underestimating training requirements for complex couplers is a common procurement risk.
The balance of evidence favors a constructive outlook: mid-single-digit growth is well-supported by infrastructure pipelines and safety-driven replacement demand, and the 5.3% CAGR consensus across competing estimates is unusually tight for this segment. The strongest counter-argument is that mechanical couplers' 42.2% share could persist longer than expected in price-sensitive emerging markets, muting the premium-mix shift that vendors are banking on.
We judge that risk as manageable but real. The regulatory direction of travel — mandatory fail-safe locking and operator-verified engagement — structurally disadvantages older semi-automatic designs, and rental-fleet standardization amplifies the shift because fleet buyers optimize for utilization, not unit price. Vendors positioned at the hydraulic/automatic end of the spectrum with certified, telematics-ready products should capture disproportionate value through 2033.
Actionable strategy:
What would change our conclusion: a sustained slowdown in Asia Pacific infrastructure spending, or evidence that regulators delay enforcement of the 2025 ISO 13031 amendment, would push growth toward the lower end of the range and favor incumbent mechanical-coupler pricing.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including high-strength steel and hydraulic component suppliers, specialist coupler manufacturers, OEM attachment divisions, rental-fleet procurement teams and regional distributors. Interviewees included VP-level Sourcing leads, Heads of Product Development, Technical Directors and Commercial Operations Managers.
Secondary validation drew on UN Comtrade and WTO trade-flow databases, US ITC and Eurostat statistics, corporate 10-K and annual investor filings from listed OEMs, patent databases, and recognized technical standards bodies including ISO and national construction-equipment associations.
Market sizing combined top-down macroeconomic and construction-segment allocation with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Both approaches were reconciled to produce the base-year valuation and forecast series.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.3% from 2020-2034 |
| Segmentation |
|
The global excavator quick coupler market was valued at approximately USD 1.2 billion in 2025 and is estimated at USD 1.3 billion in 2026, projected to reach USD 1.9 billion by 2033 at a 5.3% CAGR.
The market is forecast to grow at a 5.3% CAGR from 2026 to 2033, driven by infrastructure spending, rental-fleet expansion and tightening safety regulations such as ISO 13031.
North America led with 35.3% revenue share in 2025, supported by rental-fleet penetration and infrastructure replacement spending. Asia Pacific is the fastest-growing region over the forecast period.
The market segments into mechanical, hydraulic and fully automatic couplers. Mechanical couplers held the largest share at 42.2% in 2025, but hydraulic and automatic systems are growing fastest on safety and efficiency grounds.
Leading vendors include Caterpillar, Komatsu, Volvo Construction Equipment, JCB, Hitachi Construction Machinery, and specialists such as Steelwrist AB, OilQuick and Miller UK.
Fully automatic couplers enable attachment changes from inside the cab in under 60 seconds, reducing downtime and manual handling while improving compliance with strict workplace safety regulations.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including high-strength steel and hydraulic component suppliers, specialist coupler manufacturers, OEM attachment divisions, rental-fleet procurement teams and regional distributors. Interviewees included VP-level Sourcing leads, Heads of Product Development, Technical Directors and Commercial Operations Managers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Product Development & Technical Directors | 30% |
| Commercial Operations Managers | 20% |
| Safety & Compliance Officers | 15% |
| Company Type | Representation (%) |
|---|---|
| Coupler & Attachment Manufacturers | 40% |
| OEM Attachment Divisions | 25% |
| Hydraulic Component Suppliers | 20% |
| Rental Fleets & Distributors | 15% |
Secondary validation drew on UN Comtrade and WTO trade-flow databases, US ITC and Eurostat statistics, corporate 10-K and annual investor filings from listed OEMs, patent databases, and recognized technical standards bodies including ISO and national construction-equipment associations.
Market sizing combined top-down macroeconomic and construction-segment allocation with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Both approaches were reconciled to produce the base-year valuation and forecast series.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |