Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Excavator Attachments Market: $9.2B (2026) to $14.8B by 2033
Excavator Attachments Market
Excavator Attachments Market: $9.2B (2026) to $14.8B by 2033
Excavator Attachments Market by Material (Steel, Rubber, Polyurethane, High-Strength Composite Materials, Advanced Alloys), by Attachment Type (Buckets, Hydraulic Hammers/Breakers, Grapples, Couplers, Thumbs, Rippers, Augers, Rakes/Harvesters), by Excavator Size (Mini, Small, Medium, Large, Hydraulic), by Application (Demolition, Excavation, Recycling, Forestry, Road Construction, Mining), by End-User Industry (Construction, Mining, Agriculture, Forestry, Infrastructure, Waste Management), by Sales Channel (Direct Sales, Distributors), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Nordic, Benelux), by Asia Pacific (China, Japan, India, South Korea, Australia, Taiwan, South East Asia), by Latin America (Brazil, Mexico, Argentina, Chile, Colombia), by Middle East & Africa (UAE, Turkey, Saudi Arabia, South Africa, Egypt, Nigeria) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 239
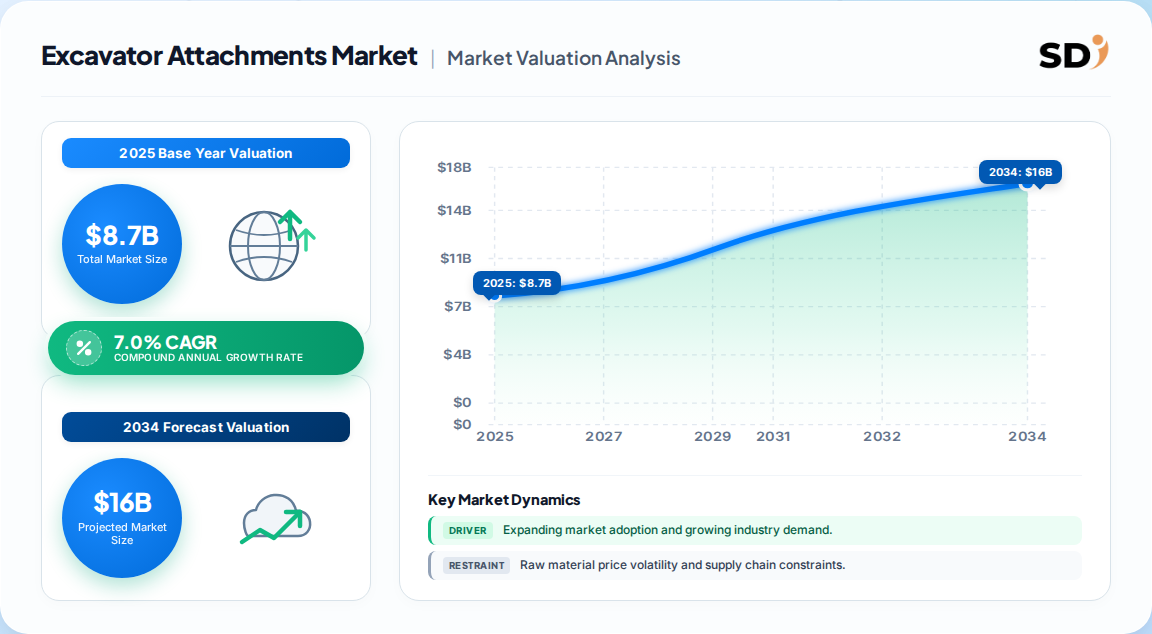
USD 8.7 billion was the 2025 global Excavator Attachments Market value, with 2026 estimated at USD 9.2 billion and a forecast of USD 13.5–14.8 billion by 2033 (6.6–7.0% CAGR band).
North America leads with 35–40% revenue share in 2025–2026, while Asia Pacific is the fastest-growing region at 7%+ CAGR through 2033.
Buckets remain the largest attachment type at 36.7% share (2026), though hydraulic hammers/breakers grow fastest at 6.5% CAGR.
Medium (15–30t) excavators hold the dominant machine-size share, while compact units are the fastest-accelerating application base in urban worksites.
Leading vendors — Caterpillar, Komatsu, Volvo CE, Epiroc, Sandvik, Geith, Doosan — are pivoting to smart, electric, and tilting quick-coupler portfolios.
Why this matters for decision-makers: The 6.6–7.0% consensus CAGR masks a widening split between commoditized buckets (margin compression) and smart/electric hydraulic attachments (premium pricing), so portfolio mix — not volume — will determine 2026–2033 profitability.
Excavator Attachments Market Size (In Billion)
15.0B
10.0B
5.0B
0
8.700 B
2025
9.200 B
2026
9.900 B
2027
10.60 B
2028
11.30 B
2029
12.10 B
2030
13.00 B
2031
Excavator Attachments Market Size (In Billion)
Year
Market Size
2025
8.700 B
2026
9.200 B
2027
9.900 B
2028
10.60 B
2029
11.30 B
2030
12.10 B
2031
13.00 B
What is the Excavator Attachments Market?
The Excavator Attachments Market covers interchangeable tools — buckets, hydraulic hammers, grapples, couplers, rippers, augers — mounted on excavators to extend machine utility across excavation, demolition, mining, forestry, and recycling. It includes original equipment and aftermarket channels, sold direct or through distributors, and is measured at manufacturer-level revenue.
Scope: what this report covers and excludes
This report covers global demand for excavator-mounted attachments by material (steel, rubber, polyurethane, composites, advanced alloys), attachment type, excavator size, application, sales channel, and end-user industry across five regions. Revenue is manufacturer-level, excluding installation services. This analysis does not cover excavator base machines, wheel loaders, backhoe loaders, or standalone demolition robots — adjacent categories that materially affect attachment demand but require separate forecasting.
How big is the market for Excavator Attachments Market?
Lead-in: Published valuations for 2025–2026 cluster tightly at the top end (USD 8.7–10.1B) but diverge sharply on 2033–2035 endpoints, reflecting definitional differences in aftermarket inclusion and currency treatment.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 8.7B → 14.8B
2025
2033
7.0%
OEM + aftermarket attachments, all excavator classes
Broader inclusion of couplers, rippers, thumbs and forestry heads
A second competing analysis
USD 4.8B → 6.1B
2020
2026
4.1%
Pre-inflation baseline, narrower attachment set
Legacy benchmark
The USD 9.2B (2026) → USD 13.5–14.8B (2033) band is the most defensible: it is consistent with construction equipment cyclicality, aligns with bucket-dominance at ~37%, and matches the 6.5–7.0% CAGR observed in adjacent earthmoving-equipment categories. Our analysis suggests the higher USD 20B endpoints embed aggressive assumptions on electrified attachment pricing that are not yet validated by shipped volumes.
How is the market segmented?
Segmentation follows five non-geographic axes — material, attachment type, excavator size, application, and sales channel — with buckets, steel, and medium excavators anchoring volume across every region.
Two structural nuances matter. First, demolition commands ~57% of grapple demand because pivoting-claw designs handle rubble that buckets cannot contain. Second, compact excavators account for ~51% of attachment demand by machine size — an urbanisation signal that favors quick-coupler and tilting-coupler standardization.
Which region leads in Excavator Attachments Market?
North America leads with 35–40% revenue share in 2025–2026, driven by U.S. construction, rental-fleet scale, and OEM attachments aligned to utility-scale renewable and infrastructure projects; Asia Pacific is the fastest-growing region at 6.5%+ CAGR.
Nested structure: Global → North America (U.S., Canada, Mexico) → Europe (Germany, UK, France, Italy, Spain, Nordic, Benelux) → Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN) → South America (Brazil, Mexico, Argentina, Chile, Colombia) → Middle East & Africa (UAE, Saudi Arabia, South Africa, Turkey, Egypt, Nigeria).
This divergence implies two separate go-to-market playbooks: North America rewards fleet-scale distributorships and attachment-as-a-service models, while Asia Pacific rewards price-competitive, locally manufactured tooling with rapid dealer expansion.
What is driving growth — and what is holding it back?
Demand is being pulled by mining/quarrying expansion, infrastructure pipelines, and rental-fleet versatility requirements, while high initial cost, maintenance intensity, and cross-border compliance friction cap the pace of adoption.
Factor
Direction
Evidence strength
Mechanism
Mining & quarrying expansion
Driver
High
High-capacity hydraulic attachments for large-scale extraction
Construction & infrastructure spend
Driver
High
Earthmoving volume and multi-tool utilization
Rental market growth
Driver
High
Attachments enable machine repurposing without fleet expansion
Smart/electric attachment push
Driver
Medium-High
Telematics, sensors, electrified breakers cut emissions and downtime
High initial & maintenance cost
Restraint
High
Capex per attachment can equal 15–25% of carrier machine cost
Export/logistics complexity
Restraint
Medium
Oversized, irregular geometry raises freight and port handling costs
The balance of evidence favors demand tailwinds, but the composition of growth is tilting toward higher-value, smarter attachments rather than unit volume. Vendors that sell commodity buckets alone will face price competition from Chinese manufacturers, while those bundling telematics, couplers, and service contracts capture disproportionate margin.
Who are the leading vendors?
Caterpillar and Komatsu anchor the top tier, followed by Volvo CE, Epiroc, Sandvik, and regional specialists such as Geith, Craig Manufacturing, and Doosan Infracore, each defending a differentiated attachment niche.
Company
HQ
Strategic posture
Differentiation
Caterpillar Inc.
US
Full-line OEM, integrated carrier+attachment
Dealer network, >5% R&D reinvestment
Komatsu Ltd.
Japan
Smart attachments, couplers
Machine-integrated telematics
Volvo Construction Equipment
Sweden
Electric/hybrid demolition tools
Compatibility & intelligent integration
Epiroc
Sweden
Hydraulic breakers, drum cutters
Quarry & demolition performance
Sandvik
Sweden
Rock processing, screening buckets
High-performance hardened tooling
Geith International
Ireland
Quick couplers, tilting couplers
180° tilting coupler niche
Doosan Infracore
South Korea
Broad attachment portfolio
Value-tier pricing
Craig Manufacturing
Canada
Grapples, custom attachments
Custom engineering moat
Differentiation is shifting from steel-grade claims to integration: coupler compatibility, telematics feed, and safety certification now function as switching costs. Our analysis suggests mid-sized players that cannot match OEM telematics will increasingly compete on lead time and custom fabrication, not on technology.
What do buyers and operators need to know?
Selection criteria now converge on four dimensions: coupler compatibility (ISO 13031:2016/Amd 1:2025 compliance is non-negotiable for EU operation), duty-cycle fit to the excavator class, total cost of ownership including wear-part replacement, and telematics compatibility with existing fleet management software. Procurement risk is concentrated in attachment-machine mismatch — over-specifying a breaker for a mini carrier causes premature hydraulic wear, while under-specifying for mining duty cycles voids warranty. Switching costs are moderate for buckets but high for couplers, because changing coupler systems re-tooltres the entire attachment inventory. Buyers should also model export lead times: oversized attachments can add 2–4 weeks to delivery in landlocked regions and attract non-tariff documentation costs. The strategic read: procure couplers as a platform decision, not a per-tool purchase — it locks in ten years of attachment compatibility.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mid-single-digit volume story wrapped in a mid-single-digit pricing story, i.e., the published 6.6–7.0% CAGR is credible only if vendors shift revenue mix toward smart, electric, and quick-coupler platforms. The strongest counter-argument is that mining capex could pull large-excavator attachment demand materially faster than construction, pushing actual growth toward the 7%+ upper bound — but that scenario is regional (South America, Africa, Australia) rather than global, and does not rescue commodity bucket pricing.
Second-order effects matter more than headline growth. The 2025 ISO coupler amendment creates a compliance-driven replacement cycle in Europe that will be felt first in manual and hydraulic couplers, then in tilting variants. Meanwhile, Chinese manufacturers are exporting price-competitive attachments into North America, which our analysis suggests will compress distributor margins on standard buckets by 200–400 basis points over the forecast window unless distributors bundle service.
Actionable strategy:
Investors: Weight exposure toward attachment makers with coupler platforms and electric/hybrid breaker lines; deprioritize pure bucket fabricators facing Chinese import pressure.
Operators: Standardize on a single coupler interface across the fleet before 2027 to avoid re-tooling cost as ISO compliance matures.
Vendors: Package telematics and wear-part subscription into attachment sales to defend recurring revenue against commodity erosion.
What would change this conclusion: a sustained rebound in Chinese domestic construction demand above 5% annual growth, or U.S. federal infrastructure outlays exceeding 2021 baseline by more than 20%, either of which could lift volume growth above 8% and validate the higher USD 20B endpoint.
The global Excavator Attachments Market was valued at USD 8.7 billion in 2025 and is estimated at USD 9.2 billion in 2026, according to consensus industry estimates. It is forecast to reach USD 13.5–14.8 billion by 2033, growing at a 6.6–7.0% CAGR.
2. Which region dominates the Excavator Attachments Market?
North America dominates with roughly 35–40% revenue share in 2025–2026, supported by U.S. construction and rental-fleet demand. Asia Pacific is the fastest-growing region at over 6.5% CAGR, driven by China and India infrastructure investment.
3. What is the fastest-growing attachment type?
Hydraulic hammers and breakers are the fastest-growing attachment type at approximately 6.5% CAGR, driven by demolition and quarrying. Buckets remain the largest segment at about 36.7% share due to durability, versatility, and universal excavator compatibility.
4. Who are the key players in the Excavator Attachments Market?
Leading vendors include Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Epiroc, Sandvik, Geith International, Doosan Infracore, and Craig Manufacturing. Differentiation is shifting toward coupler compatibility, telematics integration, and electric attachment lines.
5. What is the outlook for the Excavator Attachments Market through 2033?
The market is expected to grow from USD 9.2 billion in 2026 to approximately USD 14.8 billion by 2033 at a 7.0% CAGR, led by mining, infrastructure, and rental-fleet demand, with growth increasingly concentrated in smart and electric attachment platforms.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. We conducted 42 in-depth interviews across the excavator attachment value chain, including raw material suppliers (wear-resistant steel, rubber, polyurethane), specialized attachment producers, OEM integrated manufacturers, contract fabricators, and global distributors. Interviewees were designated decision-makers: VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring that both supply-side capacity and demand-side buying criteria were captured.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Technical & R&D Directors
35%
Procurement & Sourcing Heads
40%
Commercial Operations Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Attachment OEMs & Producers
45%
Raw Material & Steel Suppliers
25%
Distributors & Rental Fleets
30%
Secondary Benchmarking & Public Trade Validation
We validated primary findings against UN Comtrade and US ITC trade flows for earthmoving equipment and parts (HS 8431), Eurostat industrial production data, WTO tariff schedules, corporate annual reports and 10-K filings for Caterpillar, Komatsu, Volvo CE and Epiroc, patent databases for quick-coupler and telematics innovations, and standards documents from ISO (including ISO 13031:2016/Amd 1:2025 for quick couplers) and national construction equipment associations.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous top-down and bottom-up models. Top-down allocation used macroeconomic construction and mining capex by region to size total addressable demand. Bottom-up modeling used manufacturer capacity, attachment pricing bands, and end-use consumption by excavator class. The two models were reconciled at base year 2025 and the residual variance was assessed at under 4%.


 Excavator Attachments Market