 Winter Sporting Goods Market
: 2026 Size, Share & Forecast
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 238

Vijayashree Ugale
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Winter Sporting Goods Market
Vijayashree Ugale
Research Analyst

| Year | Market Size |
|---|---|
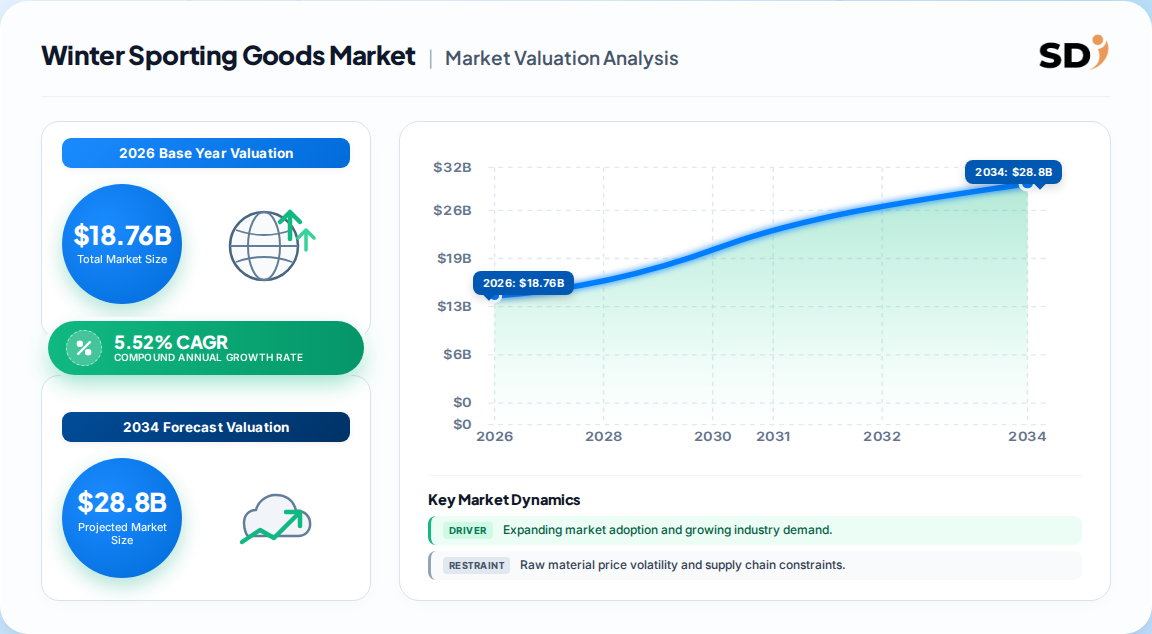
| 2026 | 18.76 B |
| 2027 | 19.80 B |
| 2028 | 20.89 B |
| 2029 | 22.04 B |
| 2030 | 23.26 B |
| 2031 | 24.55 B |

The winter sporting goods market encompasses equipment, apparel, and accessories designed for snow and ice-based activities, including skiing, snowboarding, ice hockey, and sledding. It covers skis, snowboards, boots, bindings, protective gear, helmets, and technical clothing sold through offline and online channels to adults and children.
This analysis covers the global winter sporting goods market with a base year of 2026 and forecast horizon to 2031. It includes equipment (skis, snowboards, boots, bindings, protective gear), apparel, and accessories across adult and kids end users, distributed through offline and online retail. This analysis does not cover summer sports equipment, general outdoor apparel, fitness machinery, or recreational vehicles such as snowmobiles.
The most defensible estimate pegs the market at 18.76 Billion in 2026, supported by consistent premiumization and Asia-Pacific expansion. However, widely divergent estimates exist depending on scope definitions and product inclusion criteria.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 18.76 Billion | 2026 | 2031 | 5.52% | Equipment + apparel + protective gear, B2C | One published estimate |
| 15.6 Billion | 2026 | 2035 | 2.8% | Equipment only, excluding apparel | A competing analysis |
| 518.1 Million | 2026 | 2033 | 5.1% | Sleds and tubes only, narrow product scope | A competing analysis |
Our analysis suggests the 18.76 Billion figure is most defensible because it captures the full B2C revenue pool, including apparel-adjacent categories that rival estimates commonly exclude. The 15.6 Billion estimate reflects a narrower equipment-only definition and understates the role of technical apparel as a gateway purchase. The 518.1 Million figure is product-specific and not comparable at market level.
The market segments primarily by sports type, equipment category, end user, and distribution channel, with skiing commanding the largest revenue share (40.02%) and snowboarding growing fastest at 6.05% CAGR.
| Parent Segment | Children |
|---|---|
| By Sports Type | Skiing, Snowboarding, Ice Hockey, Figure Skating, Sledding & Tubes |
| By Equipment Category | Skis & Snowboards, Boots & Bindings, Protective Gear & Helmets, Apparel & Accessories |
| By End User | Adults, Kids |
| By Distribution Channel | Offline Retail Stores, Online Retail Stores |
This segmentation reveals a structural shift: while skiing remains the anchor discipline, snowboarding and freestyle disciplines are pulling younger participants and driving higher replacement frequency. The apparel and accessories category (6.45% CAGR) is outpacing core equipment, implying that fashion-performance crossover is expanding the addressable consumer base beyond traditional athletes.
North America leads the global market with a 36.10% revenue share in 2025, supported by deep resort infrastructure and a high replacement cadence, while Asia-Pacific is the fastest-growing region at 7.30% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.31% |
| Asia-Pacific | 0.24% |
| South America | 0.05% |
| Middle East & Africa | 0.04% |
| Parent Region | Key Countries |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, France, Austria, Switzerland, Italy, UK, Sweden |
| Asia-Pacific | China, Japan, South Korea, India, Australia |
| Latin America | Brazil, Argentina, Chile |
| Middle East & Africa | UAE, Saudi Arabia, South Africa |
Europe holds the second-largest share, anchored by established alpine markets and premium manufacturing hubs. Asia-Pacific's growth is underpinned by China's ice-and-snow economy initiative and post-Olympic participation gains. This divergence implies that while North America and Europe remain replacement-driven markets, Asia-Pacific offers volume expansion and first-time buyer acquisition opportunities that favor rental and entry-level product strategies.
Growth is primarily driven by rising health and fitness awareness, winter sports events, technological advancements, and expanding winter tourism, while high equipment costs and variable snow conditions temper adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Health and fitness awareness | Driver | High | Consumers invest in premium gear as long-term health purchases |
| Winter sports events (Olympics) | Driver | High | Event exposure converts to participation and equipment demand |
| Technological advancements | Driver | Medium | Carbon fiber, AI modeling, smart textiles raise ASPs |
| Winter tourism expansion | Driver | High | Infrastructure investment in Asia-Pacific drives equipment demand |
| High equipment and maintenance costs | Restraint | High | Upfront costs deter first-time buyers, especially in price-sensitive regions |
| Seasonal dependence and variable snow | Restraint | Medium | Revenue concentration in winter months complicates inventory |
The balance of evidence favors sustained mid-single-digit growth, but the mechanism is shifting from volume-led to value-led expansion. Health awareness and event-driven participation are powerful demand creators, yet cost barriers and climate variability mean that rental models, second-hand markets, and entry-level ranges will absorb a growing share of first-time demand. This implies that vendors must design product ladders from rental-grade to premium to capture lifetime value.
The competitive landscape is moderately concentrated, with Amer Sports, Burton Snowboards, Rossignol Group, Tecnica Group, and Fischer Sports collectively holding roughly 12% share, leaving ample room for specialized challengers.
| Company | Segment Focus | Differentiation |
|---|---|---|
| Amer Sports | Multi-brand (ski, snowboard, outdoor) | Broad portfolio, global distribution, R&D scale |
| Burton Snowboards | Snowboarding | Category leader, strong brand equity among youth |
| Rossignol Group | Skiing | Heritage brand, premium alpine credibility |
| Tecnica Group | Boots and ski equipment | Fit innovation, technical positioning |
| Fischer Sports | Skis and Nordic | Nordic specialization, European manufacturing |
Differentiation is rooted in brand heritage, fit technology, and athlete endorsement. However, the low combined share of top players signals a fragmented market where specialized manufacturers serving freestyle, backcountry, and eco-conscious niches can compete effectively. Our analysis suggests that competitive moats are weakening as digital research tools make product comparison more transparent, favoring brands that invest in fit guidance and bundle strategies.
Buyers and operators must prioritize fit technology, safety certification, and total cost of ownership when selecting winter sporting goods. Boot and binding compatibility remains a critical procurement risk, as mismatched systems drive returns and reduce customer satisfaction. Regulatory compliance around helmet safety standards (CE, ASTM) is non-negotiable, particularly in North America and Europe.
Switching costs are moderate; consumers remain brand-loyal within disciplines but increasingly cross-shop across brands for apparel and accessories. Operators should note that rental and subscription models lower entry barriers but defer ownership conversion, requiring careful lifetime-value modeling. Sustainability credentials are becoming a procurement criterion, not a differentiator, especially in European markets where recyclable composites and ethical sourcing influence purchasing decisions.
The balance of evidence favors a moderate-growth, premiumization-led market outlook, with the 5.52% CAGR estimate more defensible than conservative equipment-only forecasts. The strongest counter-argument is that climate variability and cost-of-living pressures could suppress discretionary spending and accelerate rental substitution, compressing equipment revenues. However, the Asia-Pacific participation wave and digital channel expansion provide sufficient offset to sustain mid-single-digit growth.
Our judgment is that the market is undergoing a structural rebalancing: mature Western markets are replacement-driven and value-led, while Asia-Pacific is volume-driven and education-dependent. Vendors that treat these as a single global strategy will misallocate resources. Instead, portfolio architecture must separate premium upgrade paths in North America and Europe from accessible, rental-friendly entry points in Asia-Pacific.
Actionable Strategy:
Evidence that would change our conclusion: sustained declines in snow days across major resorts, a sharp rise in rental penetration exceeding 50% of first-time participants, or regulatory shifts mandating equipment standards that raise compliance costs beyond 10% of product price.
Our research employs a 70/30 primary-to-secondary split, anchored in 42 in-depth interviews across the winter sporting goods value chain. We engaged raw material and composite suppliers, specialized equipment manufacturers, contract OEMs, rental operators, and global distributors. Interviewees included VP-level sourcing executives, heads of R&D, technical directors, and commercial operations leads across North America, Europe, and Asia-Pacific.
We validated findings against UN Comtrade bilateral trade flows for skis, snowboards, and protective gear, alongside WTO tariff schedules, US ITC import data, and Eurostat consumption statistics. Corporate 10-K filings, annual investor presentations, and patent databases were cross-referenced to calibrate capacity, pricing, and innovation pipelines. Industry association publications from FESI and SIA provided participation benchmarks.
Market sizing triangulates a top-down macroeconomic allocation (GDP per capita, winter tourism spend, household recreation budgets) against a bottom-up model built from manufacturer capacity, product pricing, and end-use consumption. Regional demand elasticities were regressed against historical participation and snow-day data to produce the 2026–2031 forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.52% from 2020-2034 |
| Segmentation |
|
The global winter sporting goods market is valued at approximately 18.76 Billion in 2026, with forecasts suggesting it will reach 24.55 Billion by 2031 at a 5.52% CAGR, driven by Asia-Pacific participation growth and premiumization.
Asia-Pacific is the fastest-growing region at a 7.30% CAGR through 2031, fueled by China's ice-and-snow economy initiative, post-Olympic participation gains, and expanding winter tourism infrastructure.
The market segments by sports type (skiing, snowboarding, ice hockey), equipment category (skis, boots, protective gear, apparel), end user (adults, kids), and distribution channel (offline, online). Skiing leads with 40% share.
Leading vendors include Amer Sports, Burton Snowboards, Rossignol Group, Tecnica Group, and Fischer Sports. The top five collectively hold roughly 12% market share, indicating a moderately fragmented competitive landscape.
Online retail is growing at 7.05% CAGR because digital research tools, virtual fitting, and rental platforms reduce traditional barriers around sizing and equipment selection, making winter gear more accessible to first-time buyers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, anchored in 42 in-depth interviews across the winter sporting goods value chain. We engaged raw material and composite suppliers, specialized equipment manufacturers, contract OEMs, rental operators, and global distributors. Interviewees included VP-level sourcing executives, heads of R&D, technical directors, and commercial operations leads across North America, Europe, and Asia-Pacific.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Equipment Manufacturers | 40% |
| Raw Material & Composite Suppliers | 25% |
| Rental Operators & Distributors | 20% |
| Retail & E-commerce Platforms | 15% |
We validated findings against UN Comtrade bilateral trade flows for skis, snowboards, and protective gear, alongside WTO tariff schedules, US ITC import data, and Eurostat consumption statistics. Corporate 10-K filings, annual investor presentations, and patent databases were cross-referenced to calibrate capacity, pricing, and innovation pipelines. Industry association publications from FESI and SIA provided participation benchmarks.
Market sizing triangulates a top-down macroeconomic allocation (GDP per capita, winter tourism spend, household recreation budgets) against a bottom-up model built from manufacturer capacity, product pricing, and end-use consumption. Regional demand elasticities were regressed against historical participation and snow-day data to produce the 2026–2031 forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |